Despegue ← Catamarca OPPORTUNITY
11 more opportunitiesOther opportunities ▾
ESEN Where my company can get in
Catamarca · Puna salars · earthmoving and civil works
It is the category where Catamarca does have companies — and where the big packages still go elsewherethesis

Earthmoving and pond civil works in the Catamarca puna

Estimated entry range for a supplier
USD 1.5-5 M/year
in 2-3 years
Estimated market: USD 12-98 M/year
up to date · reviewed Sep 6, 2026
estim Jul 25, 2026midpoint ~USD 45 M/yearurgent demandour reading
At a glance
Who buys
The operator, directly — by private contracting, and today to an extra-provincial lead joint venture
the 3 doors →
In which projects
Fénix, Hombre Muerto Oeste, Salar Tres Quebradas
what each one invests →
When
Of the four construction fronts two are left, and the longest has a written date: Hombre Muerto Oeste until 31 December 2029. On the other, Tres Quebradas, stage 2 of the ponds is already under way. verif Jul 29, 2026 ↗
what to watch and where it stands →
The main barrier
There is equipment to spare and capability to spare. What is missing is position in the chain, because whoever wins a package is already an earthmover and does not subcontract it whole: they release items. The complete package asks for two years of domicile and the surety bond for a USD 13-24 M job. thesis
the whole entry map →
Where you get in
It is not that «the category does not exist»: it does, and there are Catamarca companies moving earth on Ruta 43, in the middle of the puna. The gap is a different one: the scale per package, the surety bond and the position in the chain. Four doors, from lower to higher capital:
the 4 routes →

A lithium pond is, first of all, a million cubic meters of soil moved at 4,100 meters. Tres Quebradas' contractor publishes the complete bill of quantities and there is the market with nobody's estimates: for each 200-hectare stage, 2.1 million m² of crust to break, 662,800 m³ of borrow excavation, 242,300 m³ of berms and 420,500 m³ of floor prob bill of quantities published by the contractor, in eight months that include winter, with winds of up to 120 km/h and temperatures of −30 °C. And here the diagnosis flips versus almost every other business in the province: this category does exist in Catamarca —31 construction companies and 12 equipment rental firms in the category map the provincial mining suppliers' chamber published in 2023— and there is a joint venture of three Catamarca companies in charge of 60 kilometers of road above 4,000 meters, with 15% progress as of February 2026 prob press; the award to that joint venture was published by the provincial press in August 2024 prob El Ancasti, 31-Aug-2024. The problem is not capability: it is that both pond packages tendered went to the same joint venture from outside, and the only open and proven door is to enter as a partner.

A window: the ponds and platforms are built 2026-2031 with four projects under construction at once; afterwards demand falls to road and civil maintenance in operation.

verif primary sourceestim our own calculationthesis our readingHow to read all five →

What the market is made of

The TAM is activity, not what you will invoice — but here the split has a peculiarity: a cubic meter is not imported. Zijin's Chinese chain brought the geomembrane from China and, to move the soil, hired an Argentine joint venture. So what is captive is not foreign trade: it is the contracting structure — what the head of the contract executes with its own fleet and what the operator prefers to buy as equipment rather than contract. Your gap is the items the lead releases (crust breaking, roads, rental with an operator), operating maintenance and the complete package if you enter via a joint venture.

How it splits, and against which total
The split divides the midpoint TAM of ~USD 45 M/year in two: ~60% captive and ~40% addressable. Careful with reading that 40% as your revenue: that band is everything the head of the contract does not keep, and inside it what a local entrant can really take centers on ~USD 13 M/year (it is the USD 8-18 M band of the funnel, further down). Our own estimate. estim
CaptiveUSD 27 M · 60%
Addressable (SAM)USD 18 M · 40%
CaptiveUSD 27 M60%non-addressable
what the extra-provincial lead executes with its own fleet (earthmoving IS its scope, not a sub-scope it subcontracts) + what the operator internalizes by buying equipment instead of contracting + the technical control of the EPCM firms, which write the geotechnical specification and the quality plan
Addressable (SAM)USD 18 M40%addressable
the items the lead does release: crust breaking (USD 2-4 M per stage), equipment rental with an operator, transport of equipment and material, internal roads, drainage and minor civil works + the operating maintenance retainer, which is local by nature + a complete pond package if you enter via a joint venture with a local partner. It is the whole band the lead does not keep: the market a local entrant can really address centers on ~USD 13 M/year within these 18
Non-addressable

~USD 27 M/year (~60% of the TAM): what the extra-provincial lead executes with its own fleet —the largest block and the key difference from geosynthetics, because earthmoving IS the scope of the contract leads, not a specialized sub-scope they subcontract entirely—.

See the full breakdown
what the operator internalizes by buying equipment instead of contracting (at MARA 'mine equipment' is 10.1% of capex against 21.6% for 'mine contractor'; Rio Tinto also buys its harvesting fleet); and the technical control the global EPCM firms capture (they do not move a m³ but they write the geotechnical specification and the QA plan). What this niche does NOT have as captive, and it is worth saying: a m³ is not imported — Zijin's Chinese chain brought the geomembrane but hired an Argentine joint venture to move the soil. Here the captive share is about contracting structure, not foreign trade.
Addressable share

~USD 8-18 M/year addressable by a local/domestic entrant (midpoint ~USD 13 M/year): the items the lead does release —crust breaking (USD 2.1-4.2 M per stage), equipment rental with an operator, transport of equipment and borrow material, mobilization, internal roads, drainage and minor civil works—, plus a complete pond package via a joint venture with a local partner (with a local precedent; local high-altitude capability proven on RP 43), plus almost the entire perpetual core of road and civil maintenance in operation, which is local by nature.

See the full breakdown
How the local content commitments play: Hmw's 95.34% and Fénix's 60% enlarge the SAM because this category is the largest line and the easiest to attribute as a local purchase, but they are percentages of what is paid to suppliers, with no quota by category: mistaking them for guaranteed demand in this category is the classic error.
Entry range for a supplier

USD 1.5-5 M/year for ONE entrant within 2-3 years (midpoint ~USD 3 M/year). Year 1: equipment rental with an operator on an open front plus a crust breaking sub-scope (USD 0.5-3 M). Year 2: internal roads and minor platforms plus a maintenance retainer at 1-2 operations (USD 1-3 M/year recurring — this is what survives 2031). Year 3: a 50-100 ha pond package via a joint venture (USD 3-12 M per contract). The complete 200 ha package (USD 13-24 M) is not won in year one: it is won with certified m³ and with a surety bond secured.

▸ Leverage, not a guarantee: Hombre Muerto Oeste's 95.34% and Fénix's 60% are the share of what each project pays suppliers that it declares goes to local suppliers, not quotas by category. What does play in favor is a peculiarity of this niche: earthmoving is the largest line and the easiest to attribute as a local purchase —labor in the province, equipment based there, material from the site itself—, so it is the most comfortable one for the operator to evidence the commitment with.

Who really pays?

In three of the four ways in, whoever signs the purchase order is not the mine but the contractor who won the package. There are three doors and they are quoted differently:

If you sellThe complete pond package (crust breaking, borrow excavation, berms, platform)
→
The operator, directly — by private contracting, and today to an extra-provincial lead joint venture verif 2025 ↗

At Tres Quebradas both stages were contracted by LIEX S.A. (Zijin) with a joint venture of companies from other provinces: 200 hectares executed and 200 under way, with the bill of quantities published in the project sheet. A figure that corrects the easy analogy: the Chinese operator did not bring a Chinese contractor — it hired an Argentine joint venture.

If you sellThe loose items: crust breaking, internal roads, equipment transport, rental with an operator — the lowest-capital entry
→
The lead contractor, by subcontract — NOT the operator verif 2023 ↗

Whoever wins the package is an earthmover and earthmoving is its scope: it does not subcontract it whole, it releases items. That is where the local firm comes in. The precedent of how it is done at a larger scale: a Catamarca partner came into the joint venture of two contractors from other provinces on the USD 130 M EPC for Sal de Vida's plant.

If you sellSite civil works and operating maintenance (platforms, foundations, roads, drainage, pipelines)
→
The operator, directly — and it is the only line that does not switch off in 2031 prob 2026 ↗

At Fénix it was done by a Rosario construction company in phases 1 and 2 of the expansion, on the salar: its published scope runs from site preparation earthmoving to concrete foundations, the brine pipeline, the roads and pavements and the earthmoving for the ponds. The subsequent maintenance —access roads cut off by snow, pond edges, platforms— is local by nature: it is answered in hours.

▸
The lesson: the big package is signed by the operator with a lead that has already done it, the items are paid for by that lead, and operating maintenance is paid for by the mine to whoever is nearby. The two doors that stay on this side are the item and the proximity.

Which projects move this demand

Tres Quebradas stage 2: plant and infrastructure for 40,000 t/year of lithium carbonate via direct extraction (DLE), per art…

see the project →

Lithium brine project in the Salar del Hombre Muerto (western zone), to produce 12,000 t/yr of lithium carbonate equivalent…

see the project →
USD 251 M Apr 6, 2026 ↗

Expansion (Phase 1B) of the historic Fénix lithium-carbonate project in the Salar del Hombre Muerto, operated by Rio Tinto via Minera del Altiplano…

see the project →

When the window opens

In earthmoving the warning arrives months ahead: the pond is quantified in a permit before it is tendered and it is the first job on the schedule. Two fronts are still live —Tres Quebradas stage 2 and Hombre Muerto Oeste— and two are winding down: Fénix Expansión closes construction in November 2026 and Sal de Vida Stage 1 is already in commissioning. And within each year there is a cut-off that is no longer a weather impression: since January 2026 a provincial resolution establishes a winter procedure from 1 May to 30 September (or earlier, if conditions in the area warrant it). The campaign does not stop, but it is planned differently. These four numbers are the ones that give notice.

What to watchWhat changes when it happensStatus
Hectares of pond with an environmental permit or with published bills of quantities
It is the variable that moves the number most, and it is known before the job goes to tender: environmental permits and technical reports publish pond surface (RIGI resolutions do not), and earthmoving is the first item contracted.
200 hectares of ponds under construction at Tres Quebradas, with the bill of quantities published by the contractor, which calls it its «second stage» with no date and without saying which stage of the project it belongs to prob.
See the evidence
Hombre Muerto Oeste's Phase 2 with a permit since 6 January 2025, with no pond surface published verif company announcement; some 900 hectares of design at Sal de Vida Stage 2 (850 of halite and 52 of muriate, according to the 2022 technical report), with no construction decision prob
prob Sep 6, 2026 ↗
The investment deadlines of the three Catamarca RIGI acts
They are the only construction dates that bind in writing. When a deadline approaches the front speeds up; when it expires, it winds down.
Fénix Expansión 1-Dec-2026; Tres Quebradas stage 2 30-Nov-2027; Hombre Muerto Oeste 31-Dec-2029 verif Jul 29, 2026 ↗
The direct lithium extraction pilot at Sal de Vida
Evaporation needs ponds; direct extraction needs far fewer. It is the only fact in sight that can shrink structural demand for this category — although site civil works, platforms, foundations and roads survive all the same.
authorised through an update to the environmental impact report, with ILiAD Technologies' technology.
See the evidence
the trade press published it on 13 March 2026 and the authority states it covers the pilot only, with no change to the project's design or production method
prob Mar 13, 2026 ↗
The turnover tax bracket the supplier falls into
It decides the margin and moves on its own with revenue: classified as earthmoving you pay a flat 2.50%; as a mining support service, 3.00% to 4.80% depending on how much you invoice.
code 431220, earthmoving and site preparation, 2.50%; code 99000, mining support services except oil and gas, 3.00% / 3.90% / 4.80% by bracket.
See the evidence
It is an annual series: it changes with each tax law
verif 2026 ↗
What signals the game has changed
Lithium carbonate price (2027-2031, continuous)

Sal de Vida Stage 2 is 5.98 M m³ = 41% of the volume ceiling, and it is a 'very preliminary' Class 4 estimate for years 3-40 of the mine plan, not sanctioned. It is the largest block and the most fragile: if the price does not cooperate, the TAM ceiling collapses on its own. The floor of the range already assumes it is not done.

Delay or cancellation of stages (6-24 months)

3Q Phase 2 already has its RIGI resolution published —29-Jul-2026, with USD 594,136,000 verif of computable investment—, so the risk is no longer that the act will not come out.

See the evidence
what remains open is how many hectares it actually calls for, because the act approves it as a direct-extraction plant. There are 2.65-5.30 M m³ at stake. HMW Phase 2 (250 ha of pond unconf) depends on Galan's financing; the company raised USD 20 M to start up 4 ktpa prob. And Fénix 1B closes construction in Nov-2026 with a minimum-investment deadline on 1-Dec-2026: that front shuts down by calendar, not by decision.
The lead releasing nothing / the operator's own fleet (permanent, structural)

It is the local equivalent of 'direct import': a m³ is not imported, but the lead contractor can execute everything with its own fleet and the operator can buy equipment instead of contracting (at MARA, 10.1% of capex in own equipment against 21.6% in mine contractor).

See the evidence
It is the most likely killer of the SAM and it is not solved with price: it is solved by being inside the joint venture.
Ninth clause of the Salta-Catamarca agreement (by event, no date)

The 50/50 split of the disputed Hombre Muerto strip is voided once Congress settles the boundary verif annex to Salta's Ley 8524.

See the evidence
If the strip falls on Salta's side, work counted today as Catamarca's changes jurisdiction — and with it the Re.P.E.M. and the 2 years of roots the entrant paid for. It is a domicile risk, not a demand risk.
See the remaining 6 risks
Social license and hydrology (by event, permanent exposure)

Here it bites harder than in any other niche: breaking the crust IS the physical intervention on the salt flat that is being challenged — 210 ha of broken crust per package.

See the evidence
The Mar-2024 injunction over the Río Los Patos sub-basin was lifted 5-2 in 2026 with the case open before the IACHR prob, and the Zijin-Liex brine spill into the Chaschuil river (25-Mar-2026) already happened: Catamarca's Ministry of Mining imposed a $254.1 million fine, with the impact declared limited and reversible prob converging provincial press — the sanctioning resolution could not be opened in the provincial official gazette.
Conflict over contracts — the specific risk of the category that DOES have local supply (live today)

It is the politically hottest segment precisely because there are local bidders: in Jun-Jul 2026 CAPROMITI denounced that Zijin-Liex hired a hauler from Córdoba and threatened road blockades in Fiambalá, with the Catamarca Transport Chamber and the Fiambalá Economic Chamber demanding compliance with the 70% local-purchase requirement prob provincial press.

See the evidence
An out-of-province entrant without a local partner is not buying only a commercial risk: it is buying a blockade risk.
End of the construction window (2031 — a certainty, not a risk)

Past the peak, demand falls to road and civil maintenance in operation: USD 2-10 M/year for the whole province.

See the evidence
A company built on construction has to amortize its fleet in 4-5 years. The perpetual core exists and is more solid than in geosynthetics —the road is maintained every year, snow cuts the access every winter— but it is small: 20-50 permanent jobs across the whole province.
The flowsheet: DLE needs less pond per tonne (2028+, structural)

Fénix is selective adsorption, Kachi is ion exchange, 3Q is hybrid and Rio Tinto states 'Design One, Build Many': every new tonne through DLE is pond that does not get built.

See the evidence
A FAVORABLE NUANCE for this niche: DLE still needs plant platforms, foundations, roads and wellfields, so the site civil works component is DLE-resistant — the pond component is not.
Overlap with MARA (by event, FID pre-2029) — A STATED INFERENCE, not a measurement

If MARA is sanctioned, it competes for the same base of 31 construction firms and 4 trucking companies: its initial capex allocates USD 601 M to 'mine contractor' and USD 341 M to Agua Rica infrastructure verif PFS(B), a multiple of the entire lithium pipeline.

See the evidence
It is demand upside and cost risk at the same time (shortage of fleet, drivers and operators, wage pressure). Caveat: this is an inference of ours about competition for the same supplier base, not a measurement — as of the Aug-2026 cutoff MARA was still pre-FID and with no exploitation IIA either filed or approved —what is in process is the advanced-exploration file—, with operational start-up estimated in 2032 prob. ⚠️ What changed after that cutoff: on 2 October 2026 Glencore announced that MARA received RIGI approval, still without a resolution published in the Boletín Oficial prob, and brought forward to the second half of 2027 the first production of the Alumbrera restart, with close to 2,000 people at work verif the company's statement. And in February 2026 the Supreme Court made final the ruling that struck down Andalgalá's ordinance banning open-pit mining prob prensa; we found no news on the environmental injunction or the glacier case.
Inflation, price redetermination and a fixed schedule (every contract)

RP 43 shows it: for Section I there was a single bid, of more than ARS 33,000 million against an official budget of ARS 24,353 million, 35% above it prob El Ancasti, 31-Aug-2024.

See the evidence
An 8-month fixed-price contract in the puna, with a weather window that can close —the storm of Jul 21-23, 2026 left RP 43 impassable, recorded -27 °C at the Tres Quebradas camp and forced a helicopter to be brought from Buenos Aires— is exactly where an entrant with no financial cushion goes bust.

The opportunity in depth

How to get inthe gap and the routes that open it
1

Equipment rental with an operator to whoever is already on site. The only door that does not require winning a tender — and the front of Tres Quebradas' stage 2 is open today, in equipment mobilization and crust breaking. That same chamber listed 12 rental firms in 2023, but what they offer is 4x4s, lighting towers and chemical toilets: heavy equipment suitable for 4,100 meters, with an operator and on-site maintenance, is a different product.

2

Crust breaking as a sub-scope. The perfect entry item: 2.1 million m² per stage (USD 2-4 M), low technology content, zero liner risk because it is executed before the geomembrane exists, it is the first item on the schedule —so it gets invoiced early— and the lead subcontracts it without resistance because it does not move the package's margin.

3

Internal roads, minor platforms and the maintenance retainer. USD 1-3 M a year, recurring. It is the only thing that survives 2031, and it is structurally local: an access cut off by snow or an eroded shoulder is solved in hours, not by mobilizing a fleet from Rosario. It is the line that turns a job into a client.

4

A pond package of your own, via a joint venture with a local partner. 50-100 hectares is USD 3-12 M; the complete 200 ha package, USD 13-24 M. The vehicle is the one the rule itself designs —a joint venture with at least 50% local suppliers— and it has two precedents: a Catamarca partner inside Sal de Vida's USD 130 M EPC, and a joint venture of three Catamarca companies on Section I of RP 43, at puna elevation, awarded in August 2024 with a bid of more than ARS 33,000 million prob. It is not a legal acrobatic: it is this market's normal route.

What you needcapital, certification, tax regime and who pays
It is paid against a monthly quantity certificate, with no dead gap. What you need in order to enter — the full map, in the open:
Capital
Tiered, and that is the beauty of it: USD 0.3-1.5 M to enter through equipment rental with an operator; USD 2-5 M for a crust breaking front of your own; USD 8-20 M of fleet plus working capital to bid a 200 ha package. What sinks the unprepared is not the equipment: it is sustaining an 8-month puna campaign invoicing against certificates, with the fleet immobilized by snow or wind.
Capability
Moving 6,600 m³/day and breaking 10,500 m²/day to deliver 200 hectares in 8 months. And the part that is not visible: survey control of elevations and compaction densities — the subgrade decides whether the liner lasts, and the EPCM certifies against its quality plan. Work from +26 to −30 °C, with winds of 20 to 120 km/h and an 8-month window including winter.
Regime
Re.P.E.M., the provincial mining suppliers' registry: domicile in Catamarca for 2 years, 50% local partners, 70% Catamarca payroll and a semi-annual sworn statement.
See the detail
The two years cannot be bought with capital: the route is a joint venture with at least 50% local suppliers. And the tax classification decides the margin: turnover tax 2.50% if you are classified as earthmoving and site preparation, against 3.00% in the first year and up to 4.80% in the top bracket if they classify you as a mining support service. On an USD 18 M package that is USD 90,000 estim of difference in the first fiscal year and up to USD 414,000 once you invoice in the top bracket.
Who pays
In the first three doors, almost never the mine: it is the lead contractor who won the package that pays. The operations maintenance retainer is paid by the operator.
▸ You tell us where to see what your company does and we tell you whether we see a sign that it fits this opportunity, with the evidence behind it. See if my company fits this opportunity →
When you get paid, and what blocks it
It gets paid today and there is an open front right now: 3Q's pond stage 2 is under way —'in the initial stage of equipment mobilization and surface crust breaking', verbatim from the contractor's project sheet, as of Jul 25, 2026—, HMW has its Phase 2 permitted since Jan-2025 (the 250 ha of pond, unconfirmed), Fénix 1B closes construction in Nov-2026 (minimum investment deadline Dec 1, 2026) and 3Q Phase 2 is announced. There is no dead waiting gap: there is work, and there are roads and ponds already built that need maintenance.Commercial model: a contract by bill of quantities and monthly certification against unit prices (m³ of excavation, m³ of embankment and berm, m² of crust breaking, m² of finished platform), with a mobilization advance of 10-20% [assumption], a warranty holdback and —if the client allows it— price redetermination. Variants: equipment rental with an operator by the hour or month (the fastest to invoice), a subcontract of an item inside the lead's package, and a monthly retainer for road maintenance and operating civil works. Tickets: USD 0.2-1.5 M/year (rental) · USD 2-4 M (crust breaking for one stage) · USD 3-12 M (a 50-100 ha package) · USD 13-24 M (a complete 200 ha package).The real bottleneck, in order of hardness: (1) Financial backing and guarantees, NOT equipment — a 200 ha package demands mobilizing a full fleet to 4,100 masl over 215 km of dirt and holding 8 months invoicing against certificates, and the administrative brake is concrete: the provincial chamber's 2023 category map lists ONE (1) member in insurance for the whole category, so with no surety bond you do not sign a large contract and getting one with an SME balance sheet is the filter nobody counts; (2) Re.P.E.M. (Res. SEM 498/2014): domicile in Catamarca for 2 years, 50% local partners, 70% of the professional/technical/administrative payroll from Catamarca, municipal license plus Rentas and a semi-annual sworn statement — for the outsider the route is a joint venture with ≥50% local suppliers (two proven precedents); for the local it is its most valuable asset and today it is not monetizing it in ponds; (3) homologation as the operator's vendor plus the EPCM's QA plan: the registry is not enough, the buyer asks for puna track record, HSE, altitude medical fitness and the ability to certify elevations and densities by survey — it is a technical door, not an administrative one; (4) a fleet suitable for that altitude and its on-site maintenance (power derating, spare parts 400+ km away, OTR tires, a field workshop and a hydraulics mechanic ON site: a machine standing idle in the puna costs more than its rental); (5) licensed labor with 70% Catamarca payroll, in a department of 2,022 inhabitants and 0.1 inhab./km²: the workforce is recruited in Belén, Santa María, Tinogasta, Fiambalá and the capital and rotated 7×7.The tax line that decides the margin in this category: Turnover tax 2.5% if the contract is classified as construction against 3.0/3.9/4.8% by bracket as mining support services (code 99000) — and here it weighs more than in any other niche because, given the size of the tickets, an earthmoving contractor crosses Bracket I almost from the start (the cap is ARS 3,255,000,000 of 2025 revenue ≈ USD 2.3-3.8 M depending on the exchange rate [assumption]), so the real alternative is 2.5% vs 4.8%: on an USD 18 M package that is USD 414,000. The classification is decided at registration, not at invoicing. Stamp tax: 1.5%, and here there is no classification to choose — art. 26 has two rows and the 2% is only the one in subsection 1, «acts […] linked to mining rights or mines in general». Mining infrastructure works contracts, works and services contracts and mining suppliers' purchase orders are all in subsection 2, at 1.5% verif. On USD 18 M that is USD 270,000. And whoever starts activity from Jan 1, 2026 pays Bracket I for their entire first fiscal year.Time to first invoice: 1-3 months (equipment rental with an operator to an already mobilized contractor: the site is open) · 3-6 months (a crust breaking or roads sub-scope) · 9-18 months (your own package with the Re.P.E.M./joint venture and homologation closed) estim.
Who you compete againstwho is already there and what share they take
Who is
already in
Market
split
Joint venture of companies from other provinces that won the pond packages~100% of the pond m³ contracted and documented in Catamarca (2 of 2 packages); at our prices, USD 25-48 M across the two stages

The two halite pond stages of Tres Quebradas for LIEX S.A. (Zijin): 200 ha executed + 200 ha under way, with a bill of quantities published by the contractor prob (4.18 M m² of crust breaking, 662,800 m³ of borrow, 404,300 m³ of berms, 794,500 m³ of floor and base course prob) and an 8-month schedule including winter.

See the evidence
It is the head of the contract: earthmoving IS its scope, not a sub-scope it subcontracts entirely — what it releases are items (crust breaking, roads, equipment rental).
Civil-works contractor from another province~100% of the site civil works documented at Fénix

Civil works for the Fénix expansion, phases 1 and 2, status 'Executed' in the Catamarca puna, with the verbatim scope the project declares: site preparation earthmoving, reinforced concrete foundations, brine pipeline and drainage, fire water network, earthing, drains and underground works, roads, pavements and fencing, an equalization pond with geomembrane, earthmoving for the 'Piletas Ponds', a biodigester and a nitrifying bed.

See the evidence
Plus Sal de Oro (Salta) and Rincón (Salta, SBDF, under way). It is the most complete contractor in the lithium NOA and the most obvious joint-venture partner — or the toughest rival.
Joint venture of two contractors from other provinces with a Catamarca partnerthe EPC of Sal de Vida's carbonate plant, USD 130 M

The only documented precedent of a local partner inside a large package, with an amount and with a clause giving priority hiring to residents of Antofagasta de la Sierra under a 70/30 policy. It is the niche's entry route.

Joint venture of three Catamarca construction companies100% of the province's largest puna civil works contract — an adjacent market, NOT counted in the TAM

Section I of RP 43: 60.3 km of earthworks and paving between Antofagasta de la Sierra and the border with Salta, with 15% physical progress as of February 2026 prob.

See the evidence
the Ministerio de Infraestructura of Catamarca awarded it in August 2024 to this joint venture, the sole bidder, with an official budget of ARS 24,353 million, a bid of more than ARS 33,000 million and a 24-month schedule prob; ~20 km paved up to the Cuesta de Paicuqui. It is THE proof that there are Catamarca construction companies capable of executing at scale in the puna thesis: this niche's gap is not one of raw technical capability. The works are paid for with the Mining Royalties Trust Fund, so lithium royalties are financing the road that gives access to the lithium.
See the remaining 6 players
Salta mining-services company offering the integral pond package0% documented in Catamarca unconf

A vertical integration threat: it sells the integrated pond package (geological and geotechnical assessment, design, grading, construction, geomembrane installation, containment berms and fill supervision) verif. If it comes in, it takes earthmoving and liner together and closes the subcontract door from both sides.

The 31 construction companies and 12 equipment rental firms of the CAPPROMIN registry (Catamarca)0% documented in pond packages

The 2023 registry (19 categories, exactly 123 memberships) declares 31 construction companies with 'modular housing, civil works, earthmoving and road maintenance' and 12 vehicle and equipment rental firms —whose declared description is 4x4s, lighting towers, aerial work platforms and chemical toilets, i.e. it does NOT evidence a heavy fleet—. None is named in a pond package. It is at once the entrant's competing base and its pool of joint-venture partners. A 2023 count: verified as a citation, out of date as a measurement of today's supply (the Re.P.E.M. went from 194 in May-2025 to 229 in May-2026).

Foreign EPCM engineering firms0% of the category, 100% of the gatekeeping

They do not execute a single m³: they write the geotechnical specification and the QA plan —pond floor elevations, tolerances, compaction densities, tests— and they decide what gets certified and who qualifies. Technical homologation goes through them, not through the provincial counter.

The operator's own fleet (the invisible competitor)not public, but quantified in the only available breakdown

At MARA, 'mine equipment' is 10.1% of the initial capex (USD 281 M) against 'mine contractor' at 21.6% (USD 601 M) verif: the buy-vs-contract decision is explicit and the supplier does not control it. Rio Tinto also buys its own salt harvesting fleet verif. Every m³ the operator does with its own equipment never reaches the market.

Chinese contractors in Zijin's chain0% documented in earthmoving

A figure that corrects the analogy with san juan: in the province's largest package, the Chinese operator did NOT bring in a Chinese contractor — it hired an Argentine joint venture. It did import the geomembrane (20 trucks via the Paso San Francisco). In earthmoving there is no importable m³: the risk of 'direct import through the operator's chain' exists but did not materialize in the measured case.

Catamarca mining-services and civil-works company with machinery rental (Andalgalá, Catamarca)undocumented in lithium works unconf

From Catamarca, from ANDALGALÁ -the department with 36 registrations in the Re.P.E.M., second after the capital-. Declared activities: construction, repair and restoration of transport infrastructure works; wholesale of construction materials; Rental of machinery AND equipment without an operator; road freight transport including specialized freight; and manufacture of non-metallic mineral products. It appears in the supplier registry of CAMYEN, the provincial State mining company. It is the exact profile of the equipment rental firm this niche identifies as the local leg of earthmoving. What is not proven: not a single work front was documented for it on the Salar del Hombre Muerto lithium projects; its presence is evidenced in the province and in the category, not on the salar.

The jobs it createsIt is the niche with the most direct employment per dollar billed in the whole Catamarca portfolio, and it arrives first: earthmoving is the first job on the schedule — before the plant, before the liner, before production. La lectura completa para el que busca trabajo, en la hoja de este nicho para la gente →

How we
calculate it

The number is our own estimate. The calculation, step by step, is below.

The full calculation, step by step
Annualization window: Catamarca's EXTENDED one, 2026 → 2031 (÷5 years). ⚠️ It is not the canonical window (2026-2029). The extended one is used for the same reason as in the geomembranes and ponds niche: what is counted is cubic metres of works, and part of that volume falls outside the ring committed by a RIGI act. Consequence: this TAM/year compares with the one from the geomembranes and ponds niche, which annualizes the same way, and NOT with the five that divide over 3.5 years. ⚠️ And block (C) —road and civil maintenance during operation— is a perpetual core and lives outside any window.TAM = (A) [m3 of pond earthmoving pay items ÷ years × USD/m3] + [m2 of crust breaking ÷ years × USD/m2] + (B) [non-pond site civil works: % of capex under construction] + (C) [perpetual core of road and civil maintenance in operation]. INTENSITIES derived from the province's only published bill of quantities (3Q stage 1, 200 ha, read in the contractor's published take-off): 6,628 m³ of pay items per hectare of pond (= 0.663 m³ per m² of pond) and 10,515 m² of crust breaking per hectare (= 1.05 m² per m² of pond).Volume (Catamarca alone, 2026-2031 window ≈ 5 years): 3Q stage 2 UNDER WAY 536,000-1,072,000 m³ (the borrow item is not published ⇒ a band) + 2,078,000 m² of crust breaking verif LPP project sheet · 3Q Phase 2 (a 40 ktpa plant; RIGI resolution published on 29-Jul-2026, with USD 594,136,000 of computable investment — the USD 709 M was the announcement. ⚠️ The act approves it as a DIRECT-EXTRACTION plant, which calls for less pond per tonne than the evaporation route this line is calculated with) 400-800 ha ⇒ 2.65-5.30 M m³ + 4.21-8.41 M m² [assumption: intensity of 20 ha/ktpa derived from 3Q, cut by up to 50% for a hybrid adsorption route] · Sal de Vida Stage 2 (850 ha halite + 52 ha muriate) 0-5.98 M m³ + 0-9.49 M m² [design verified in NI 43-101 §17.2.2, execution assumed: a 'very preliminary' Class 4 estimate for years 3-40, not sanctioned] · HMW Phase 2 (250 ha unconf: the announcement of the Jan-2025 permit does not publish a surface area) 1.66 M m³ + 2.63 M m² prob · Fénix pre-concentrate and 1B disposal ponds 0.13-0.40 M m³ + 0.21-0.63 M m² [assumption: it is selective adsorption DLE, surface not published] ⇒ window total floor 4.98 M · midpoint 9.68 M · ceiling 14.41 M m³ and floor 9.12 M · midpoint 16.17 M · ceiling 23.24 M m² ⇒ ÷5 years = 0.99/1.94/2.88 M m³/year and 1.83/3.23/4.65 M m²/year. Pace check: the only documented package did 200 ha (1.33 M m³ + 2.1 M m²) in 8 months including winter, so the midpoint equals ~1.5 simultaneous packages — consistent with 3-4 open fronts.Price, first triangulation: earthmoving USD 8-15/m³ (midpoint 11) and crust breaking USD 1-2/m² (midpoint 1.5), explicit assumptions triangulated by three independent routes (Sal de Vida's verified capex ⇒ 8-17/m³; the real RP 43 Section I contract ⇒ 6-16/m³; productivity physics with a puna derating ⇒ 7-15/m³); crust breaking is also cross-checked against the physics (scarifying 0.25-0.40 m of crust = 0.25-0.40 m³/m² at USD 4-6/m³ ⇒ 1.0-2.4 USD/m²). (A) Pond TAM at the starting price: floor 0.99×8 + 1.83×1.0 ≈ USD 9.8 M/year; midpoint 1.94×11 + 3.23×1.5 ≈ USD 26.1 M/year; ceiling 2.88×15 + 4.65×2.0 ≈ USD 52.5 M/year. With the price that governs (midpoint 8.5), which is the one behind the published band, the midpoint of (A) falls to 1.94×8.5 + 3.23×1.5 ≈ USD 21.2 M/year — and that is the figure that adds to (B) and (C) to give the midpoint of 45. (B) non-pond site civil works (the weak leg, declared): mining capex actually under construction in Catamarca USD 150-400 M/year over the window estim reading a single base — announced amounts: Fénix Exp. 1B USD 531 M with works Jul-2024→Nov-2026, HMW USD 292 M with a Phase 2 of USD 200 M, 3Q 2nd stage USD 709 M announced, with a resolution published on 29-Jul-2026 that computes USD 594,136,000; Sal de Vida Stage 2 not sanctioned × 7-12% of site civil works [assumption anchored in two real references: the EPC of Sal de Vida's carbonate plant = USD 130 M verified, whose civil portion runs 20-30% ⇒ USD 26-39 M in a single package; and Milicic's verbatim scope at Fénix] ⇒ USD 10-35 M/year, midpoint ~20 (the ceiling cut down from 48 because the projects' peaks are not simultaneous: adding them at maximum would be inflating). (C) perpetual core: maintenance of access and internal roads, repair of pond berms and edges, minor platforms, drainage and small operating civil works across 4-5 operations × USD 0.5-2.0 M/year ⇒ USD 2-10 M/year, midpoint ~5 [assumption; support: Fénix moves ~40 trucks/day over roads it maintains, the access is 215 unpaved km and RP 43 is 15% complete]. TAM: floor 9.8+10+2 ≈ USD 22 M/year; midpoint 26.1+20+5 ≈ USD 50 M/year; ceiling 52.5+35+10 ≈ USD 98 M/year.The band we publish, and why it is the conservative one: USD 12-98 M/year, midpoint ~USD 45 M/year, with the unit price cut back to 5-15 USD/m³ (midpoint 8.5) —at 11 the pair of niches consumed 115 % of Sal de Vida's pond line item— and Tres Quebradas' Phase 2 at zero in the floor: it has had a published resolution since 29-Jul-2026, but the act approves it as a direct-extraction plant, the route that needs fewest ponds. A hard variant, only what comes out of a bill of quantities: USD 5-63 M/year, midpoint ~USD 25 M. The extremes are not likely joint outcomes.What does not go into the number (no double counting): geomembrane and geotextile (supply, installation, seam CQC, liner integrity and halite harvesting = the neighboring geosynthetics and ponds niche; THE boundary is the platform — this number reaches up to the shaping of the floor and the subgrade, and the geosynthetics one starts at the geotextile upward, so the two TAMs can be added), well drilling, detailed engineering and inspection, reagents, laboratory, altitude health, camps and modules, RP 43 AND the provincial roads (public works with a different client and a different pot: they are used only as a price anchor and as proof of local capability), Sal de Oro (its pond contractor's project sheet —Milicic— places it in SALTA, its hydroxide plant is in General Güemes and the national study tabulates it as Salta's, even though Catamarca's Investor Manual claims it on the brine side: the asset is split and it was not added to either province), Diablillos (a Salta project with an interprovincial agreement), Rincón's SBDF (Salta, benchmark only), Kachi (pre-FID and ion-exchange DLE) and MARA/Agua Rica (pre-FID, with no approved exploitation EIA, estimated operational entry 2032). Sal de Vida does count even though it has wells in Los Andes Department (Salta): its ponds and its plant are in Catamarca.

Concentration High per package, low by category, and with an asymmetry that defines the whole route in.In ponds: 2 of 2 documented packages to the same extra-provincial lead joint venture, with a single buyer (LIEX/Zijin).In plant civil works: one contractor per operator and every one of them from outside (at Fénix and at Sal de Vida) — there is no visible competition per package, there is award by track record and relationship.In the category as such, concentration is low: 31 construction companies and 12 rental firms in the provincial chamber's 2023 category map and 229 active suppliers in the Re.P.E.M. (May-2026), but with 75 of 194 concentrated in the capital and only 12 in Antofagasta de la Sierra, the department of the three Hombre Muerto projects: the supply exists where the work is not.The asymmetry: the concentration is not one of technical capability —a joint venture of three Catamarca companies is in charge of 60.3 km of earthworks and paving in the middle of the puna, with 15% progress as of February 2026, awarded in August 2024 prob El Ancasti, 31-Aug-2024— but of position in the contracting chain. The big packages are awarded to whoever has already done them, and the only open, documented door is the joint venture with a local partner (the same local partner, twice). Conclusion: the market is not unserved and the local supply is not incapable — it is displaced from the head of the contract.

The rule that moves it

This niche has two rules pushing it and one that decides its margin. Pushing: the local-content commitments written into acts of State: Hombre Muerto Oeste declares that 95.34% of what it pays suppliers goes to local suppliers —the highest percentage among the resolutions of Catamarca and of the zone shared with Salta— and Fénix 60%, three times the regime's minimum; and this category is the easiest to attribute against those commitments, because the labor, the equipment and the borrow material are in the province. The key to collecting from that amount is the Re.P.E.M., which requires two years of domicile, half the partners local and 70% of the payroll from Catamarca — and admits the joint venture with a local partner as a shortcut, with two proven precedents. And the margin is decided by Ley Impositiva 5.927: the same contract pays 2.5% of Turnover tax if it is classified as construction and up to 4.8% if it is classified as a mining support service, plus 1.5% Stamp tax on the contract (art. 26 subs. 2) — and the Turnover tax classification is chosen at registration, not at invoicing.

See the underlying reading

The underlying policy that opens up this demand. It is the same inference declared by the rules and the program pillars pushing in this direction.

the RIGI promise is kept
enables
Re.P.E.M.: Catamarca's mining local-content rule is a resolution, not a law
See the rule →
It is the counter that turns the local-content commitment into a contract: with no Re.P.E.M. you do not collect from Hombre Muerto Oeste's 95.34% or Fénix's 60%.
See the full legal grounds
Its roots requirements (2 years of domicile, 50% local partners, 70% Catamarca payroll, semi-annual sworn statement) are a barrier for the outsider and an asset for whoever is already established — and here it weighs differently than in the rest of the portfolio, because in this category there are indeed 31 registered Catamarca construction companies that could use it and are not monetizing it in ponds. The joint venture with at least 50% local suppliers is the legal vehicle, with two documented precedents: a Catamarca partner on Sal de Vida's USD 130 M EPC and a joint venture of three Catamarca companies on Section I of RP 43.
pressures
Catamarca 2026: extracting pays 0.75% turnover tax; serving the mine, 3% to 4.8%
See the rule →
It decides the segment's margin: the same contract pays 2.5 % turnover tax if classified as construction and up to 4.8 % as a mining support service, plus 1.5 % stamp duty on the contract. The classification is chosen at registration.

Where the number comes from

the ponds alone give ~USD 21 M/year (1.94 × 8.5 plus 3.23 × 1.5) —with the price the audit set, not the starting assumption of 11—; adding the site civil works that are not pond (midpoint ~USD 20 M/year, almost half the niche) and operating maintenance (~USD 5 M/year), the midpoint reaches ~USD 45 M/year. The full band is USD 12-98 M/year depending on which stages get built and at what price. The hard variant —only what comes out of a published bill of quantities— is USD 5-63 M/year, midpoint ~USD 25 M

See the calculation, the variables and how it was validated

The TAM is built from four variables you can watch from outside: how many hectares of pond get built, how many cubic meters and square meters each hectare demands, how much each unit costs delivered to site and over how many years it is executed. Change one and the number is recalculated.

~1.94 M m³/year × ~USD 8.5/m³ + ~3.23 M m² of crust breaking × ~USD 1.5/m² + site civil works + operating maintenance=~USD 45 M/year at the midpoint; band USD 12-98 M/year
Hectares of pond in the window~670-2,210 ha (midpoint ~1,460)annual review
Tres Quebradas stage 2 (200 ha, under way today) + its Phase 2 + Sal de Vida Stage 2 (902 ha, the big piece and the most fragile: it is a preliminary estimate for years 3 to 40 of the mine plan) + Hombre Muerto Oeste Phase 2 (250 ha, unconfirmed) + Fénix's pre-concentrate ponds. It moves with every RIGI resolution and every permit published.
Intensity per hectare~6,628 m³ of pay items + ~10,515 m² of crust breakingstructural
It comes from the province's only published bill of quantities: Tres Quebradas' stage 1, 200 hectares with 1,325,600 m³ across borrow excavation, berms and floor, plus 2,103,000 m² of crust breaking. It can vary ±40% depending on topography, crust thickness and distance to the borrow pit.
Unit price in the punaUSD 5-15/m³ (midpoint 8.5) and USD 1-2/m² of crust breakingannual review
The one governing the published figure is the one corrected by the audit: 5-15 USD/m³ with a midpoint of 8.5. The starting assumption was 8-15 (midpoint 11), and it was cut when cross-checked against Sal de Vida's pond line item: at that price, the pair of niches consumed 115% of that line. There is no public Argentine price: it is an explicit assumption triangulated by three routes that share no inputs — Sal de Vida's pond capex (implies 8-17 USD/m³), the real contract for Section I of Route 43 above 4,000 masl (6-16 USD/m³) and the productivity physics of a fleet with altitude derating (7-15 USD/m³).
Years of execution~5 years (2026-2031)structural
It is a window niche: the work is concentrated while the four projects are under construction and afterwards falls to road and civil maintenance in operation (USD 2-10 M/year for the whole province). That is why the TAM is annualized over the window and not in perpetuity.

A robustness check by two independent routes. Top-down: Catamarca's portfolio under construction moves on the order of USD 1,500-2,400 M over the window, and earthmoving together with site civil works runs 12-20% of a lithium project's capex ⇒ USD 36-96 M/year, an interval our range contains with a more conservative floor. By pace: the only documented package did 200 hectares in 8 months including winter, so the midpoint equals ~1.5 packages running simultaneously — consistent with three or four open fronts and not with a single one. There is also a reading that can rarely be made: this niche and the geosynthetics one are the two halves of the same pond package, and it is worth looking at them together. It goes as context and not as a third confirmation, for method transparency: both rest on the same Sal de Vida capex line, so they back each other in a circle. The figure stands on the two routes above, which share no inputs.

The number rests on a few variables. The formula shows how it moves when each one changes; and each variable carries its freshness seal — how often it is worth revisiting. estim

How solid the number is estim

This is the niche with the best-measured demand in the province, and not because we calculate it: the contractor itself publishes the bill of quantities —cubic meters of excavation, of berms and of floor, and square meters of crust breaking— for the two Tres Quebradas pond stages, and we reopened those sheets to confirm every number. What does not exist is a public price for earthmoving on a high-altitude mining project, so the USD per cubic meter is an explicit assumption and we cross-check it by three routes that share no inputs: the pond capex declared in Sal de Vida's technical report, a real puna road contract in the same province (Section I of Route 43, with a published official budget) and the productivity physics of a fleet at 4,100 meters. All three give the same band. The annual total is our own estimate and we say so.

Coverage: CAPPROMIN's category map, the provincial chamber of mining suppliers (19 categories and 123 memberships, as of 2023: 31 construction firms and 12 equipment rental firms, with the detail of what each one declares it rents out), and the CASEMICA & ER member list · Sep 14, 2026 · not reviewed: the Re.P.E.M., which is the mandatory provincial registry, publishes the total number of registrants and their breakdown by department but never the names; and the provincial government's supplier register (COMPR.AR Catamarca) is queried one at a time and cannot be listed from outside

How to cite this figure: Despegue (2026). Earthmoving and pond civil works in the Catamarca puna · Catamarca. despegueargentina.com/en/catamarca/movimiento-suelo-obra-civil-puna · terms of use

Neighbouring markets2 markets in the same group, from USD 2,5 to USD 27 M a year

First step · free
The first read of your company

We look at what your company does and tell you whether we see a sign that it fits this market, with the evidence behind it. If we do not see one, we say so too and name the condition that would change it. One page as a dated PDF, within 48 working hours.
Not here for a company? Invest · Work (in Spanish) · Start a business (in Spanish) · Institutions
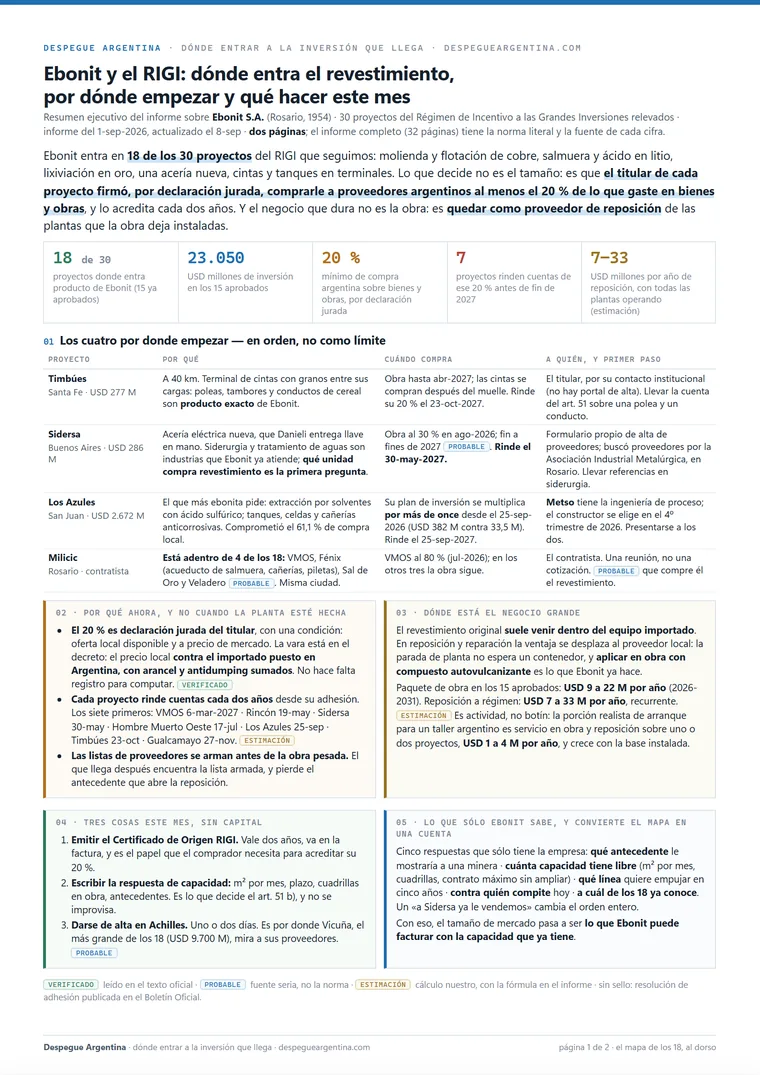
Page 1 of the example executive summaryOpen the report ↗A real analysis · a real company, open in full →
Ignacio Aredez
Analysis and curation: Ignacio Aredez
Head of Despegue
Method and track record →
  • 20+ years in technology, 15 of them in data and AI, for clients across Europe and the Americas
  • Certified in AI governance (ISO/IEC 42001)
  • Machine Learning (Google Cloud)
  • Registered expert with the European Commission
How to read the seals →
  verif primary source · prob primary source pending · unconf a source said it · estim our own calculation · thesis our reading · the date belongs to the datum, at the precision its source allows
This is not financial advice. The TAM is an estimate with a transparent method, not an official figure; the framing is labeled as thesis. Every figure carries its source. ← All opportunities in Catamarca