Despegue ← Catamarca OPPORTUNITY
11 more opportunitiesOther opportunities ▾
ESEN Where my company can get in
Catamarca · Salar del Hombre Muerto and Fiambalá · well drilling
The gap exists and is proven; the door is not the production well — and a local firm has already walked through itthesis

Brine and water well drilling (Catamarca)

Estimated entry range for a supplier
USD 0.5-2 M/yr
in 2-3 years
Estimated market: USD 4-18 M/year
up to date · reviewed Jul 29, 2026
estim Jul 25, 2026midpoint ~USD 10 M/yearwindow openour reading
At a glance
Who buys
The operator, directly — under a campaign contract
the 3 doors →
In which projects
Fénix, Hombre Muerto Oeste, Salar Tres Quebradas
what each one invests →
When
Construction has an end date and monitoring does not: Tres Quebradas until 30 November 2027 and Hombre Muerto Oeste until 31 December 2029, while water, monitoring and well servicing run through the forty years of mine life. verif Jul 29, 2026 ↗
what to watch and where it stands →
The main barrier
What is bought has no certificate: it is knowing how to case a well in salt crust, and it is not paid for with price but with track record. You do not get it by bidding for production wells, which are awarded by whole wellfield: you get it through water and monitoring. thesis
the whole entry map →
Where you get in
Do not start by fighting for the production well against the only firm that has already completed a wellfield on that salar. You come in through water and monitoring, with a tenth of the capital, and it bills every month:
the 5 routes →

Of the six drilling companies that made Sal de Vida's wells, only one is from Catamarca — and it is not the one drilling the production wells: the only firm that completed a wellfield on the salar came from Mendoza with head office in Vancouver. That does not weaken the gap, it locates it. The honest number is small —~USD 10 M a year— and the door is not the obvious one: the two wells a contractor attempted with air circulation could not be cased and were abandoned. On a salar the differentiator is not having the rig, it is knowing how to case in salt crust. Whoever really gets in comes through the water well, the monitoring well and well service —ten times less capital, monthly invoicing and the same school— and only then sits down in a joint venture for a wellfield. The Catamarca firm already inside came in through that door.

A double clock: the construction window of the four wellfields (2026-2029) is the one an entrant CANNOT capture; the core it can capture —monitoring, water and workover— is perpetual, with 40 years of mine life.

verif primary sourceestim our own calculationthesis our readingHow to read all five →

What the market is made of

The TAM is activity, not what you will invoice — and in this field the difference is brutal. The larger half of a «wellfield» budget is not drilling: it is the brine pipeline crossing the salar, the pumping station, the pumps, the generators, the pads and the roads, which builders and erection contractors charge for. And the well design is signed off by a foreign hydrogeological consultant. What is addressable by a local entrant is the rest: water, monitoring, well service and the site work the incumbent subcontracts.

How it splits, and against which total
Midpoint of the captive/addressable split (~50-65% captive, per the funnel) over the midpoint TAM of ~USD 10 M/year. Our own estimate. estim
CaptiveUSD 6.2 M · 62%
Addressable (SAM)USD 3.8 M · 38%
CaptiveUSD 6.2 M62%non-addressable
the production wellfield when the operator's chain brings its own driller + the well design, which belongs to the hydrogeological consultant and never becomes a drilling contract + the non-drilling half of the budget (pipeline, pumps, pads, roads)
Addressable (SAM)USD 3.8 M38%addressable
8-10" raw water wells, monitoring wells and piezometry (today a court-ordered obligation), workover and well service, shallow-to-medium boreholes and the site work and logistics the incumbent subcontracts
Non-addressable

USD 5-7 M/year (~50-65% of the midpoint TAM): three layers that are not contested. (i) The production wellfield when the operator's chain brings its own driller — the foreign driller's proven incumbency at Sal de Vida, the unidentified driller of HMW's 31 wells, Zijin's own chain.

See the full breakdown
(ii) The hydrogeology that defines the well, which belongs not to the driller but to the consultancies: a foreign consultancy (aquifer model and resource estimate: MODFLOW-SURFACT/USG, Leapfrog Hydro), another that signs the well technical reports and two more consultancies: it is the part of the 'wellfield' budget that never becomes a drilling contract. (iii) The non-drilling half of the capital line (HDPE/PEX pipeline, booster station, pumps, generators, pads, roads), which goes to builders and erection contractors.
Addressable share

USD 3-5 M/year addressable by a local/domestic entrant: raw water wells, monitoring wells and piezometry, workover and well service, shallow-to-medium exploration boreholes and site and logistics subcontracts to the incumbent.

See the full breakdown
Hmw's 95.34% and Fénix's 60% enlarge it — they force a look at the local registry and compliance is audited — but with a hard caveat not to be confused: they are the local share of what each project pays suppliers, not quotas by line of business; and without a Catamarca firm credentialed in 24" bore work (the only local firm documented on the salar plays in water and monitoring, not in the production wellfield), the well is bought outside, the operator declares 'no local offer available' and the percentage is met with catering, transport and construction.
Entry range for a supplier

USD 0.7-2 M/year for ONE new entrant within 2-3 years: one used water/monitoring rig (on the order of USD 0.6-1.2 M/year of billing per active rig [assumption]) + a workover book over the ~30-45 installed wells + site subcontracts to the incumbent. That is 7-21% of the TAM and ~25-40% of the SAM: this is the figure you sell, never the TAM.

▸ The clock that forces you to move even though the big prize is not today: the provincial registry requires domicile in Catamarca with 2 years of seniority. To be able to join an eligible joint venture when the 2027-2029 wellfields are awarded, you have to be established in 2026. Establishing yourself is cheap; arriving late to the registry cannot be fixed with price.

Who really pays?

Who signs depends on the well: the production field is contracted by the operator, the monitoring well is usually contracted by its hydrogeological consultancy, and site work is paid for by the incumbent driller. There are three doors:

If you sellThe complete production wellfield (24"/16" wells, 10" casing, pumping test and logging)
→
The operator, directly — under a campaign contract verif Mar 31, 2022 ↗

Sal de Vida made its 8 production wells with a foreign driller based in Mendoza between Dec-2020 and Nov-2021, and its earlier phases with a Salta driller, another one from Mendoza and other smaller drillers verif. It is the door an entrant does not cross alone: it is crossed in a joint venture thesis.

If you sellThe monitoring well, the piezometer and the hydrogeological test — the recurring entry
→
The project's hydrogeological consultant, or the operator against its monitoring obligation verif Mar 31, 2022 ↗

The aquifer model and the resource estimate belong to a foreign hydrogeological consultancy; the well technical reports of 2017 and 2018 and the hydrogeological study of the Los Patos river basin (2019) were signed by another consultancy, and the 2021 wetland monitoring by a third consultancy verif. That the second consultancy is a Salta firm is not stated in the report unconf. That is the link where local substitution is furthest along, and the one the court-ordered continuous monitoring obligation enlarges thesis.

If you sellThe raw water well, the site work and well service
→
The operator or the municipality for water; the incumbent driller by subcontract for the site prob 2023 ↗

Sal de Vida's two water wells (SVWF12_19/20, more than 20 L/s each) were drilled by a Salta driller in 2012, and Fénix has 6 pumping wells authorized at 130 m³/h on the Los Patos river. On the civil side: the Tinogasta Mining Suppliers Chamber already brokered a water well for Fiambalá with Zijin-Liex. It is the only door in this niche that also sells to a town.

▸
The lesson: the production well is bought from whoever has already drilled on that salar; the water well, the monitoring well and well service are the door that does stay on this side — and they are the ones that pay every month for the mine's 40 years.

Which projects move this demand

USD 251 M Apr 6, 2026 ↗

Expansion (Phase 1B) of the historic Fénix lithium-carbonate project in the Salar del Hombre Muerto, operated by Rio Tinto via Minera del Altiplano…

see the project →

Lithium brine project in the Salar del Hombre Muerto (western zone), to produce 12,000 t/yr of lithium carbonate equivalent…

see the project →

Tres Quebradas stage 2: plant and infrastructure for 40,000 t/year of lithium carbonate via direct extraction (DLE), per art…

see the project →

When the window opens

In drilling the warning arrives through the Boletín Oficial and through the environmental rule: every published act is a wellfield about to be tendered, and every monitoring obligation is invoicing that waits for no construction. The construction has dates in writing: Tres Quebradas until 30 November 2027 and Hombre Muerto Oeste until 31 December 2029, while Sal de Vida Stage 2 still has no investment decision. The monitoring obligation has none: since December 2020 the environmental impact report of a brine project is not processed without presenting, for each brine well and each observation well, its design, its hydrochemical analysis and its technical report, with the pumping tests notified to the authority in advance. That this page's number is held up by that recurring queue and not by new construction is our reading of how the market is composed, not a figure from a source. These five numbers are the ones that give notice.

What to watchWhat changes when it happensStatus
The published RIGI acts and what each one authorises
Every act turns an assumed wellfield into one with a date.
three acts published; the most recent, Tres Quebradas, on 29 July 2026, with construction from 1 June 2026 and operation from 1 April 2029.
See the evidence
counting the zone shared with Salta, the most recent is Sal de Oro II, of 31 July 2026. Sal de Vida Stage 2 and Hombre Muerto Oeste Phase 2 still have no act of their own
verif Jul 29, 2026 ↗
The process route, because it decides which kind of well gets drilled
Evaporation needs production and monitoring wells; direct extraction adds the reinjection of processed brine, a category of well this number does not count.
the Tres Quebradas expansion is approved as direct extraction, verbatim in the resolution.
See the evidence
and Sal de Vida has a direct-extraction pilot authorised since February 2026. ⚠️ No source publishes how many reinjection wells either case would need, and the article reporting the pilot speaks of reinjection as a generic property of the technology, not of this project
prob Mar 13, 2026 ↗
The monitoring wells the provincial rule requires
It is the recurring segment this page already identifies as the way in, and it now has two administrative obligations on top of the judicial one: it turns it from a contingency into a permanent obligation.
in force through two routes: a hydrochemical analysis and technical report for every observation well since December 2020, with the environmental impact procedure suspended if it is missing.
See the evidence
and piezometers plus multiparameter meters at every producing well since September 2023, with a 60-day deadline expired and a written sanction
verif Sep 29, 2023 ↗
The groundwater use levy
It is the cost of the water well, which is this page's lowest-capital door, and it is updated by resolution.
there are two 2024 resolutions in the provincial mining legislation index, one for groundwater and one for surface water.
See the evidence
⚠️ We did not open them: we only have their titles in the index
unconf 2024
The tax classification of the well
It decides the margin, and it has a written trap: the earthmoving code excludes by text the drilling of mine and hydraulic wells, so a mining drilling service cannot be classified there.
water-well drilling, code 422100, a flat 2.50%; mining support services except oil and gas, code 99000, 3.00% / 3.90% / 4.80% by bracket.
See the evidence
It is an annual series: it changes with each tax law
verif 2026 ↗
What signals the game has changed
Delay or cancellation of stages (the dominant risk)

The larger of Catamarca's two announced amounts ALREADY HAS ITS ACT: Tres Quebradas stage 2, with a resolution published on 29 July 2026 and USD 594,136,000 verif of computable investment — the USD 709 M was the announcement.

See the evidence
Sal de Oro II has had its own since 31 July 2026 as well, with USD 207,936,427 computable verif Resolución 1157/2026. Sal de Vida Stage 2 —the 15 wells that are the largest slice of this number— remains prior to the final investment decision, with Class 4 capex the technical report itself calls «very preliminary». If that front slips, the production-well segment empties out all the same. Timing: 12-36 months.
Lithium carbonate price

Today it is a tailwind, not a killer: the Q2-2026 average spot was USD 22,043/t (+125% y/y in the first half) and Rio Tinto realized USD 18,960/t against a C1 below USD 5/kg at Fénix verif Rio Tinto Q2-2026 filing with the SEC.

See the evidence
The killer is the reversal: exploration and voluntary monitoring are the first discretionary capex to be cut, hitting ~30-40% of the TAM within 6-12 months. Wellfields with RIGI in execution hold up better.
Direct import / the operator's chain

Permanent. Zijin imports part of its inputs through its own chain (20 trucks of Chinese geomembrane via the Paso San Francisco, a partial shipment prob) — although in site services the measured precedent runs the other way: it contracted the Tres Quebradas ponds with an Argentine UT (Pietroboni + ITALCA + BMI).

See the evidence
What remains open in this niche is the gap: the driller for HMW's 31 wells is not identified, and a crew brought in through the operator's chain would skip the entire local market. It is harder than in goods —drilling is intensive in logistics and local personnel— and today it is a killer with a pending name, not a measured case in drilling.
Ninth clause of the Salta-Catamarca agreement

Structural and with no date: the 50/50 split of taxes and royalties lapses when Congress settles the boundary, and the titular province remains the sole authority verif annex to Salta's Ley 8524.

See the evidence
Disputed strip: Salta claims at least 134 of the salar's 586 km²; in 1985 and 1987 the Supreme Court recognized the jurisdiction of Salta's judges in disputes over Diablillos and Hombre Muerto, and in 2015 it declared itself without jurisdiction and referred the boundary to Congress prob provincial press — the rulings were not opened in their original text. What this means for this niche: a heavy-drilling bet anchored in Catamarca's Re.P.E.M. local-roots status can wake up with its wellfield reclassified as Salta's and Salta's Ley 8.164 regime applying in its place. The water and monitoring bet, spread across the whole province, has no such exposure.
See the remaining 3 risks
Social license and water (with a stated double edge)

Román Guitián's amparo (Comunidad Atacameños del Altiplano) was PAUSED, not closed, as of the Aug-2026 cutoff: the injunction was lifted ~Apr-2026, the case on the merits was still running and there was a filing pending before the CIDH prob converging press.

See the evidence
The operational trigger has already happened: Zijin-Liex's brine spill on 25-Mar-2026 that reached the Chaschuil river, the third in seven months according to the neighbors quoted by the press, with a $254.1 million fine from the Ministerio de Minería de Catamarca prob converging provincial press — the sanctioning resolution could not be opened in the provincial BO. A new injunction stalls permits — and a water well IS a permit. DOUBLE-EDGED: more monitoring obligation is more demand for monitoring wells; the killer of heavy drilling is the accelerator of the wedge.
End of the construction window vs. the perpetual core (2029-2031)

A certainty, not a risk: once the four wellfields are built, new production wells drop to replacement rate (1-3/year).

See the evidence
What remains is perpetual and is precisely the wedge — workover, monitoring and water over 40 years of mine life at Fénix and at Sal de Vida. The entrant betting on the window arrives late; the one betting on the perpetual core has a 40-year client.
Weather, altitude and the global shortage of drillers

Operating variance: 4,000-4,300 masl, 26 to -30 C, winds of 20-120 km/h, a winter window (on Jul 21, 2026 five Fénix workers were trapped above 4,500 masl under 2 m of snow prob three outlets converging).

See the evidence
And a bottleneck that is not local: Major Drilling states driller retention as its main challenge and 'the pool of available experienced drillers drying up'. It raises the entrant's labor cost — and turns whoever trains local crews into an exporter of the field's most expensive input.

The opportunity in depth

How to get inthe gap and the routes that open it
1

The 8-10 inch raw water well for 20-40 liters per second: the lowest-capital door and the one with a double market. The mine needs it —Sal de Vida requires 20-40 L/s of process water, Fénix has 6 wells authorized at 130 m³/h on the Los Patos river— and the town needs it: the Tinogasta Mining Suppliers Chamber already brokered a water well for Fiambalá with Zijin-Liex. Same rig, same trade, and a flat 2.5% of Turnover tax.

2

The monitoring well and water-level measurement: an obligation with three origins at once, turned into a recurring contract. Since December 2020, the provincial brine guideline requires, for every observation well, its design, its hydrochemical analysis and its technical report —and without that the environmental impact report is not even processed—. Since September 2023, every pilot or producing plant must have piezometers and multiparameter meters at each producing well, with an expired deadline and a written sanction. And on top of that there is the Río Los Patos case, where the court lifted the injunction on the strength of a study acknowledging «the need for continuous monitoring» and the substance of the case remains open. In a salt flat an observation well is not a cheap piezometer: those at Sal de Vida were drilled at 17½, 12¼ and 8 inches.

3

Well service —pump replacement, descaling, screen cleaning— and the site subcontract to the incumbent: pads raised 1.5 m over the salar, roads, mud logistics, drilling water, crews. Low capital, monthly invoicing, and every intervention is a free lesson in the only thing the heavy segment pays for: how a casing behaves in salt crust.

4

With a track record of your own, year 3-5: the joint venture for a production wellfield. The provincial registry admits temporary unions with at least 50% local suppliers, and the precedent is in the province itself: a Catamarca builder entered the USD 130 M contract for Sal de Vida's plant that way. The entrant does not compete against the incumbent: it sells it the local half of the contract.

5

And there is a category that still has no number and is worth watching: the reinjection well. Direct extraction returns processed brine to the salt flat, and those are wells evaporation does not need. Tres Quebradas has a direct-extraction plant approved by resolution and Sal de Vida has an authorised pilot. No source publishes how many reinjection wells would be needed, so it is not counted in this page's number.

What you needcapital, certification, tax regime and who pays
The input is paid against progress, with no dead gap. What you need in order to enter — the full map, in the open:
Capital
The order-of-magnitude difference is the decision: an 8-10" water and monitoring rig down to 200-300 m costs on the order of USD 0.4-1.2 M; a rotary capable of a 24" bore with a mud plant and a high-altitude fleet, on the order of USD 3-8 M for two rigs. And the heavy market offers 5-19 wells a year across the whole province, awarded a whole wellfield at a time.
Capability
What is really being bought has no ISO seal: casing and gravel-packing in salt crust. It is proven by two lost wells —SVH09_01 and SVH09_02, with air circulation, «could not be cased and were abandoned»—. The key trade is the mud engineer. Add crews acclimatized to 4,000-4,300 masl, with 26 to −30 °C and winds of 20-120 km/h.
Regime
Registration with the Re.P.E.M. (Resolution SEM 498/2014): provincial domicile with 2 years of seniority, 50% local partners, 70% Catamarca payroll and a semi-annual sworn statement — plus homologation on the operator's supplier portal. And a tax classification that pays: a water well pays a flat 2.5% turnover tax; a brine well, 3.0-4.8% as a mining service, because «drilling and boring» excludes mine drilling.
Who pays
The operator contracts the wellfield directly; the monitoring well is usually contracted by its hydrogeological consultant; and the site work is paid for by the incumbent driller. They are three different doors.
▸ You tell us where to see what your company does and we tell you whether we see a sign that it fits this opportunity, with the evidence behind it. See if my company fits this opportunity →
When you get paid, and what blocks it
It gets paid today, but at two speeds. The heavy segment pays a lot and infrequently (wellfield contracts awarded in blocks: Sal de Vida's first wellfield campaign ran 12 continuous months, Dec-2020 to Nov-2021). The wedge segment —water, monitoring, workover— pays less and every month, and it waits for no FID: the monitoring obligation is already firm and the water wells are needed regardless.Commercial model: meter drilled BY diameter (not per meter of well: borehole meters are 2.30x the final depth, calculated on Table 10-2 of the NI 43-101 — it is the most important commercial figure in the field and nobody publishes it) + mobilization and demobilization + daily standby + pumping test by the hour (Sal de Vida's ran 36-72 h per well, with average flows of 17.8-35.0 L/s) + logging + casing and gravel pack by the meter. Contracts per well or per campaign; the client (a RIGI operator, a listed major, or its EPC/hydrogeological consultant) is among the best payers in the country.The real bottleneck, in order:(1) Re.P.E.M. (Resolution SEM 498/2014): domicile in Catamarca with 2 years of seniority, 50% of partners domiciled in the province, in a joint venture >=50% local suppliers, municipal license + Rentas registration, 70% of the professional/technical/administrative payroll from Catamarca with >=2 years of residence and a semi-annual sworn statement (the silent filter that de-registers suppliers). The 2-year seniority is the only barrier capital cannot buy.(2) Homologation in the operator's supplier registry: Rio Tinto runs its own portal and program (+50 suppliers trained, 800 hours of assistance, 290 improvement actions, +60% in requests for quotation, a 90% acceptance rate, 20-F 2025) — the very existence of the program proves the door exists and can be walked through.(3) Capital by route: the wedge (an 8-10" water/monitoring rig down to 200-300 m + support) on the order of USD 0.4-1.2 M; heavy (rotary with 24" bore capability, mud plant, high-altitude fleet, 2 rigs) on the order of USD 3-8 M [both explicit assumptions] — the order-of-magnitude difference IS the funnel argument.(4) Altitude and medical fitness at 4,000-4,300 masl, with a regulatory vacuum that is both risk and opportunity: we found no legislation setting fitness criteria above 3,500 masl unconf, and each company sets its own bar.(5) The certification that is actually bought —casing in salt crust— has no ISO seal: it is evidenced with wells delivered, hence the order water -> monitoring -> workover -> production in a joint venture.(6) TAX (Ley Impositiva 5.927, Annex I opened): the turnover tax differential is not a choice, it is decided by which well you drill. 'Water well drilling' (422100) pays a flat 2.5% across all three brackets; the brine well falls under 'mining support services' (99000), which pays 3.0/3.9/4.8% by bracket, against 0.75% for the party doing the extraction. 'Drilling and boring' (431220), which also appears at a flat 2.5%, is not an alternative: its own wording reads 'except the drilling of oil, gas, mine and hydraulic wells'. That is why the order water -> monitoring -> workover carries a tax consequence on top of the commercial one: the water leg bills between 0.5 and 2.3 points cheaper than the brine leg with the same rig, and the final classification is set by Rentas on the declared activity, not by the contract. Add Stamp tax from the dedicated mining chapter (art. 26): 1.5% on purchase orders, agreements, contracts for mining works and services and contracts for mining infrastructure works (subsection 2), and 2% only on acts tied to mining rights or mines in general (subsection 1) — on a USD 5 M contract that is USD 75,000-100,000 that almost nobody puts in the model; the classification between the two subsections is worth 0.5 points and is a sellable advisory service. Plus the art. 30 fee for bidding (0.1% public / 0.05% private) and art. 16, which puts anyone starting activity from Jan 1, 2026 in Bracket I for their entire first fiscal year (Bracket I up to ARS 3,255,000,000 of 2025 revenue).(7) Time to first invoice: 3-6 months via a subcontract to the incumbent (pads, roads, mud logistics, drilling water) or via a municipal or camp water well; 6-12 months via a monitoring/piezometry well contracted by the operator or its hydrogeological consultant; 18-36 months for the first production well of your own, and realistically through a joint venture estim.
Who you compete againstwho is already there and what share they take
Who is
already in
Market
split
Foreign driller based in Mendoza30-45%

HQ Vancouver, base in Mendoza. The ONLY firm with a complete production wellfield proven at the Salar del Hombre Muerto: 8 wells + 1 water well between Dec-2020 and Nov-2021, 24"/16"/8.75" boreholes, 10" PVC casing with gravel pack, logging (spontaneous potential, induction, nuclear magnetic resonance, spectral gamma) and a 36-72 h pumping test per well. This is the incumbency an entrant does not displace on price.

Salta-based driller, the most prolific on the asset15-25%

Base in Salta. The most prolific in the asset's history: the brine wells of phases 2, 3, 4 and 5 AND the two WATER wells SVWF12_19/20 (2012), which yield >20 L/s each. It is the one already covering the two segments that would be the entrant's wedge.

Mendoza-based driller5-10%

Base in Mendoza. Brine and reverse-circulation wells of Sal de Vida's phase 2.

HMW's unidentified contractor + Zijin's own chain10-20% unconf

Stated gap: HMW reports 31 wells / 9,043 m for its JORC resource (consultant WSP Chile) without naming a driller, and Zijin executes with its own chain (Chinese geomembranes via the Paso San Francisco) and installed >=3 water wells in Fiambalá. Some 10-20% of the map is assigned to an unknown player: it is the direct-import killer with a name still pending.

See the remaining 6 players
Driller based in Salta city (shallow wells)~5%

Salta city — the technical report describes it verbatim as 'a firm based in the city of Salta'. Wells SVH10_03A to SVH10_04B, conventional mud-rotary, 4.5" PVC casing with gravel pack: the shallow segment, the closest thing to what an entrant can do.

Regional driller from Salta with 300+ professionals0-10% unconf

Salta city, +300 professionals. The regional benchmark: it offers brine production wells and reserve estimation, with Sales de Jujuy, Ganfeng and First Quantum among its clients. With NO documented Catamarca contract: it is a latent threat and a natural joint-venture candidate, not an incumbent.

Catamarca driller of the salar (water and monitoring)0-5%

THE CATAMARCA DRILLER OF THE SALAR. Commercial and logistics base in the Capital verif -- plus a third base in San Juan. It states 40 years of track record, presence in 8 provinces and the four methods that matter on a salar: Rotary, Dual Rotary, RC and Diamond. It appears in the supplier registry of CAMYEN, the provincial State mining company verif. Sal de Vida's NI 43-101 attributes well SVWW18_26 to it. Where it plays and where it does not: it is the living proof of this niche's thesis -- a Catamarca firm IS inside, but through water and monitoring, not through the production wellfield. It does not state 24" bore capability or a complete brine wellfield. It is, exactly, the joint-venture partner profile that art. 5.3 of the Re.P.E.M. enables.

Driller with an unconfirmed location0-5%

The other firm that Sal de Vida's primary source does not locate geographically; no website of its own, official record or directory locating it was found unconf. It drilled SVH09_01 and SVH09_02 with conventional air circulation: 'could not be cased and were abandoned'. It is the documentary proof of the field's technical barrier -- on a salar the differentiator is not having the rig, it is knowing how to case in salt crust.

The 6 members under 'drilling services' of the Catamarca Mining Suppliers Chamber~0% of the heavy segment unconf

2023 registry (verified as a citation, not as a measurement of 2026 supply). Generic activity descriptions that do not evidence 24" bore capability. Plausible presence in water and monitoring, undocumented. Nobody audited rig by rig, and without that you cannot claim they are unable to.

NOA driller with a high-caliber fleetunconf

NOA, a fleet of large-calibre rigs; its role in Catamarca is undocumented.

The jobs it createsEmployment, measured in the only documented case: Sal de Vida's first production wellfield campaign ran 12 continuous months (Dec-2020 to Nov-2021) for 8 wells and one water well. La lectura completa para el que busca trabajo, en la hoja de este nicho para la gente →

How we
calculate it

The number is our own estimate. The calculation, step by step, is below.

The full calculation, step by step
Annualization window: Catamarca's CANONICAL one, 2026 → 2029 (~3.5 years). It comes from the shared table of provincial magnitudes and follows the legal deadlines of the three Catamarca RIGI acts — the furthest out is Hombre Muerto Oeste's 31-Dec-2029 — not an editorial choice. ⚠️ But it governs only half the figure: the window annualises the construction of the four wellfields; monitoring, water and workover are a perpetual core running the ~40-year mine life, with no window closing them. Both blocks are kept apart in the calculation, and that is why the TAM does not switch off in 2029: it shrinks.Units (wells and boreholes per year in Catamarca) x price per unit, with two independent methods that converge.Price: the only verifiable anchor in the field is the 'Wellfields & Brine Distribution' capital line of Sal de Vida's NI 43-101 (Table 21-1, read in the primary source): USD 13 M in Stage 1 (Class 2 +/-10%, the most precise estimate in the whole study) for 9 wells (8 operating + 1 standby, verbatim in §16.2) and USD 26 M in Stage 2 (Class 4 +30%/-20%) for 15 new wells of the Southwest Wellfield (verbatim in §15.2.7) -> USD 1.44 and 1.73 M per well ALL IN (brine pipeline, booster station, 3 booster pumps, a 115 m3/h pump and a diesel generator with a 72 h tank per well, pad raised 1.5 m, road, SCADA).What stopped being an assumption: the preliminary economic assessment of Hombre Muerto Norte, on the same salar, publishes the wellfield broken down, and there drilling and completion of 14 wells is USD 9.2 M out of a USD 22.1 M total, i.e. 41.6% (the rest is fluids and tooling 0.9, service roads 1.1, piping 2.9, labor 3.1 and indirect management and subcontracting 4.9). That same line, over the 280 m of average depth declared, gives USD 2,347 per meter of completed well. We publish the 41-50% band (the 41.6% measured as the floor; the ceiling is kept because the pump line does not appear in that table, and if pumps were inside 'drilling and completion' the 41.6% would be overstated). The part that hires a drilling contractor (telescoped drilling + 10" PVC casing + 1-2/1-3 mm gravel pack + bentonite and cement seal + development + logging + a 36-72 h pumping test) is therefore 41-50% of that line = USD 0.60-0.87 M per production well, or USD 2,150-3,100 per meter of completed well over the 280 m average depth (§16.2, verified), or USD 930-1,350 per meter of borehole applying the 2.30x ratio calculated on Table 10-2. Prices derived for the rest of the products, all flagged as an explicit assumption scaled by diameter: brine exploration/observation well (17.5"/12.25"/8", 130-300 m) USD 0.14-0.24 M; monitoring well/piezometer USD 0.06-0.15 M (and it is worth clarifying that on a salar a monitoring well is NOT a cheap piezometer: Sal de Vida's were drilled at 17.5"/12.25"/8"); 8-10" raw water well for 20-40 L/s USD 0.12-0.40 M (physical anchor: well SVFW21_21 was drilled at 16" and 8.75" with 10" casing; Fénix's at Los Patos were authorized at 130 m3/h each); workover intervention USD 0.03-0.08 M; diamond core drilling USD 400-600/m (industry range; stated assumption, with no public rate to anchor it). Units/year (2026-2029 window): brine production wells 5-19 (midpoint 10) adding up Sal de Vida Stage 2 (15 verified wells; the pre-FID schedule, unconfirmed), Fénix 1B, 3Q Phase 2, HMW Phase 2 and replacement of the installed stock at 5-8% -> every count other than Sal de Vida is a scale assumption, it is the most fragile input; exploration and observation wells 10-25 (Albemarle Antofalla stated a 2026 plan of >=10 wells, 5 pumping + 5 observation; scale reference: HMW drilled 31 wells / 9,043 m = 292 m/well for its JORC resource); monitoring wells and piezometers 8-20 (the Court lifted the Los Patos river injunction on the basis of an EGIA that acknowledges a 'need for continuous monitoring', with a PGIA of 7 programs and a case pending before the iachr: an obligation, not an option); raw water wells 2-6; core boreholes 5-15; workover interventions 8-20. Method A (bottom-up) = USD 5.7-30.9 M/year, midpoint 14.6. Method B (top-down cross-check) = the wellfield line is 4.2% of the capex of a brine project (13/308 = 4.2%, 26/594 = 4.4%, 38/902 = 4.2%, verified) applied without mixing bases to the Catamarca capex in flight (Fénix 1B USD 251,321,494 countable over 29 months; HMW USD 217,090,266 with year 1 at 31.1 M and year 2 at 51.5 M; 3Q Phase 2 with a resolution published on 29-Jul-2026, which computes USD 594,136,000 (the USD 709 M was the announcement); Sal de Vida Stage 2 pre-FID = 0 in the base case) x 35-50% of drilling = USD 5.5-8.3 M/year of construction + 2.5-8 M/year of exploration, monitoring, water and workover = USD 8-20 M/year.What does not go into the number (no double counting): the brine pipeline, the booster station, the pumps, the generators, the pads and the roads of the wellfield itself (they belong to the earthmoving and erection niche); the wells the primary source places in Los Andes Department, SALTA (SVWW17-22, SVWW17-23, SVWW18-24); Sal de Oro (a split asset, hydroxide plant in Gral. Guemes, Salta - including it would add on the order of USD 1-3 M/year, stated as a sensitivity); Rincón and Hombre Muerto Norte (Salta); Diablillos and MARA/Agua Rica (hard-rock diamond drilling, a different product - MARA is the largest uncounted upside); and the local-content commitment, which is a percentage of the investment amount going to suppliers and not a quota by line of business: it does not guarantee a single meter drilled by a Catamarca firm.

Concentration Extreme in the heavy segment and structurally extra-provincial: two firms (a foreign one based in Mendoza and one from Salta) cover on the order of 50-65% of all documented drilling on the best-documented asset in the province, and only one has a proven production wellfield on the salar. But the correct reading is not 'there is little competition, easy to enter': it is a market of FEW contracts and few players — on the order of 5-19 production wells a year across all of Catamarca, awarded a whole wellfield at a time, where the buyer systematically prefers whoever has already drilled there because every well is a 40-year reserve asset. The province has 229 suppliers in the Re.P.E.M. (May-2026) but 75 of 194 are in the capital and only 12 in Antofagasta de la Sierra, the department of the salar (2,022 inhabitants, 0.1 inhab./km2): the department that holds the lithium cannot supply it.

The rule that moves it

The driver of this niche is provincial and twofold: the Re.P.E.M. (Registry of Suppliers to Mining Companies) decides who can quote the mine —and its requirement of 2 years of domicile turns early establishment into an entry barrier favoring whoever arrived first—; and Ley Impositiva 5.927 gives the water well better treatment than the rest of mining services: a flat 2.5% turnover tax against the 3.0-4.8% a brine well pays as a mining support service.

See the underlying reading

The underlying policy that opens up this demand. It is the same inference declared by the rules and the program pillars pushing in this direction.

the RIGI promise is kept
enables
Re.P.E.M.: Catamarca's mining local-content rule is a resolution, not a law
See the rule →
The Re.P.E.M. is this niche's door and clock at once: it requires domicile in Catamarca with 2 years of seniority, 50% local partners, 70% Catamarca payroll, a semi-annual sworn statement and, in a joint venture, at least 50% local suppliers.
See the full legal grounds
With 229 active suppliers (May-2026) but only 12 in Antofagasta de la Sierra —the department of the salar—, the registry measures the gap exactly. And its seniority requirement explains why it is worth establishing yourself now even though the big contract is awarded in 2028: the only barrier capital cannot buy is time.
pressures
Catamarca 2026: extracting pays 0.75% turnover tax; serving the mine, 3% to 4.8%
See the rule →
A water well pays a flat 2.5 % turnover tax. The drilling and boring code excludes mine drilling, which pays as a mining support service, 3 % to 4.8 % depending on the bracket; on top of that comes 1.5 % stamp duty on the purchase order.

Where the number comes from

~USD 10 M/year at the midpoint, counting only the work fronts already open and the acts of State already published; the band is USD 4-18 M/year. It rises to USD 14-17 M/yr if the three expansion fronts get going. Tres Quebradas already has its act published, since 29 July 2026, with construction from June 2026 and operation scheduled for April 2029; Sal de Vida Stage 2 and Hombre Muerto Oeste Phase 2 still have no act of their own and no investment decision

See the calculation, the variables and how it was validated

The TAM is built from three variables you can watch: how many wells get drilled per year in the province, how much each well costs and what share of that cost the drilling contractor charges rather than the builder. Change one and the number is recalculated.

~10 production wells/year × ~USD 0.73 M of drilling contract + ~35 exploration, monitoring and water wells + workover=~USD 10 M/year at the midpoint; band USD 4-18 M/year
Brine production wells per year5-19 (midpoint ~10)annual review
Sal de Vida Stage 2 is 15 wells (a figure from the technical study) but it is pre-FID; Fénix 1B, Tres Quebradas Phase 2 and Hombre Muerto Oeste Phase 2 publish no well count: there the number is a scale assumption, and it is the most fragile input of the calculation. It moves with every FID and every RIGI resolution published.
Drilling contract per well~USD 0.66-0.87 M (USD 1,900-3,200 per meter of completed well, midpoint ~2,350)annual review
This is no longer an assumption. The preliminary economic assessment of Hombre Muerto Norte —the same salar— publishes the wellfield broken down: drilling and completion of 14 wells = USD 9.2 M out of a USD 22.1 M total, i.e. 41.6% for the drilling contractor; the rest is fluids and tooling, service roads, piping, labor and indirects. Over the 280 m of average depth the same report declares, that gives USD 2,347 per meter of completed well. It is direct cost and in 2024 dollars without escalation: it is not a 2026 price, and a stand-alone well is not quoted at the per-meter rate of a fourteen-well campaign.
Borehole meters per meter of well2.30×structural
Calculated well by well on the construction table: 4,082 borehole meters for 1,772 meters of completed well. The well is drilled telescoped —an 8¾" pilot to total depth, reamed to 16" in the aquifer, reamed to 17-24" up top for the casing—. It is the commercial figure that decides a quotation and nobody publishes it.

Robustness check: a fully independent second method —the wellfield line is 4.2% of the capital of a brine project (13/308, 26/594 and 38/902 all give 4.2-4.4%), applied to the Catamarca capex in flight without mixing bases— gives USD 8-20 M/year and converges with the midpoint. And there is an uncomfortable result worth stating: the ceiling of the construction portion lands at USD 6.5-9.3 M/year, below the midpoint. The TAM is not held up by new works: it is held up by exploration, monitoring, water and well service.

The number rests on a few variables. The formula shows how it moves when each one changes; and each variable carries its freshness seal — how often it is worth revisiting. estim

How solid the number is estim

The anchor for the figure is not a headline: it is the capital line «Wellfields & Brine Distribution» of Sal de Vida's technical study —USD 13 million for the 9 wells of the first stage and USD 26 million for the 15 of the second—, which we opened and read in full, together with the table listing well by well the 24, 16 and 8¾ inch boreholes and the 10 inch casing. On top of that we did two things nobody does: we separated what a drilling contractor charges from what the builders in the same budget charge (the pipeline, the pumps, the roads), and we counted the real borehole meters, which are 2.3 times the well's depth because it is drilled telescoped. The annual total is our own estimate and we say so: we multiply wells per year by price per well, and we cross-check it with a second method —what percentage of a brine project's capital the well is— which gives the same order. When there is no public price, we declare it: there is no published rate whatsoever of dollars per meter of brine well in Argentina.

Coverage: the six drilling companies that executed Sal de Vida's wells (seven names in its technical report, because one is a division of another): only one of them is from Catamarca —Hidroper, according to its own website—, and the one that completed the wellfield came from Mendoza with its head office in Vancouver · Sep 14, 2026 · not reviewed: the compulsory provincial registry does not publish a list of names; we found no published register of water-well drillers, provincial or national; and no universe of suppliers of slotted casing and graded gravel was reviewed

How to cite this figure: Despegue (2026). Brine and water well drilling (Catamarca) · Catamarca. despegueargentina.com/en/catamarca/perforacion-pozos-salmuera-agua · terms of use

Neighbouring marketsOne market in the same group, from USD 6 to USD 60 M a year

Who makes it · the incumbent

First step · free
The first read of your company

We look at what your company does and tell you whether we see a sign that it fits this market, with the evidence behind it. If we do not see one, we say so too and name the condition that would change it. One page as a dated PDF, within 48 working hours.
Not here for a company? Invest · Work (in Spanish) · Start a business (in Spanish) · Institutions
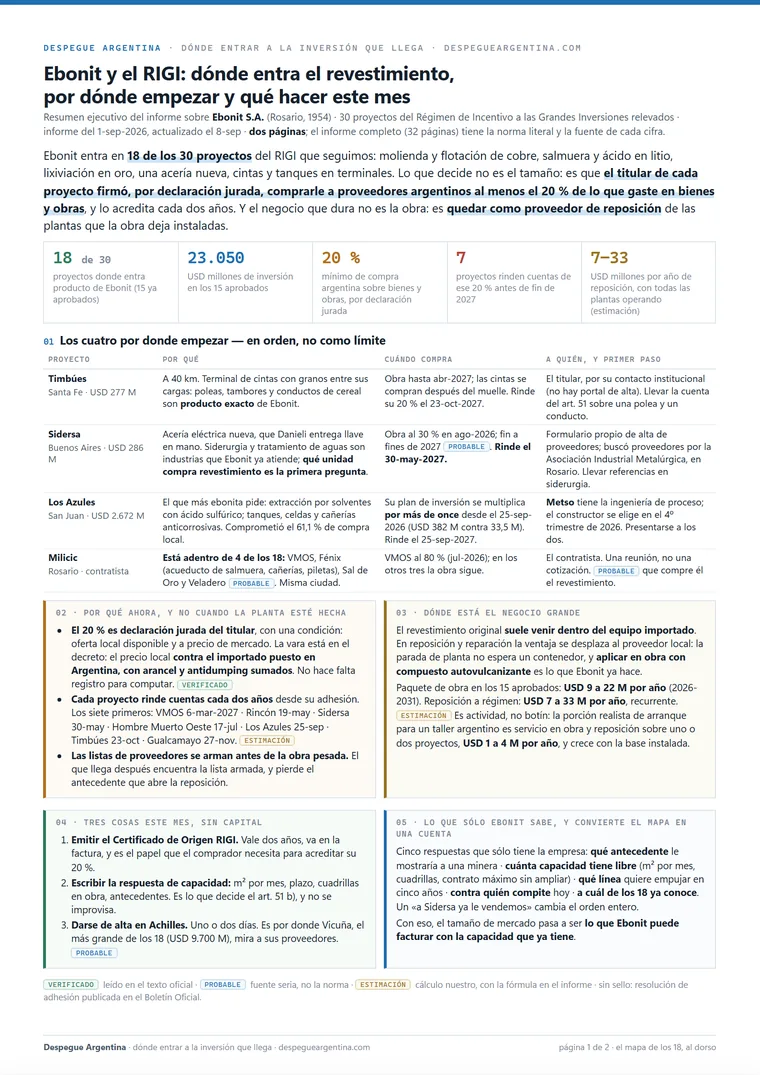
Page 1 of the example executive summaryOpen the report ↗A real analysis · a real company, open in full →
Ignacio Aredez
Analysis and curation: Ignacio Aredez
Head of Despegue
Method and track record →
  • 20+ years in technology, 15 of them in data and AI, for clients across Europe and the Americas
  • Certified in AI governance (ISO/IEC 42001)
  • Machine Learning (Google Cloud)
  • Registered expert with the European Commission
How to read the seals →
  verif primary source · prob primary source pending · unconf a source said it · estim our own calculation · thesis our reading · the date belongs to the datum, at the precision its source allows
This is not financial advice. The TAM is an estimate with a transparent method, not an official figure; the framing is labeled as thesis. Every figure carries its source. ← All opportunities in Catamarca