Detailed engineering, inspection and construction document control (Catamarca)
In Catamarca four lithium projects started up in twelve months and not one of them bought its engineering in the province. The names are in the primary sources: a global firm did Sal de Vida's capital estimate, a foreign one signed the technical report, another did Stage 2, and Hombre Muerto Oeste's nanofiltration plant was manufactured and tested in Sydney before being shipped. On the other side, only the construction is Argentine — and there is a precedent that defines the path: the EPC for Sal de Vida's carbonate plant, USD 130 M, was signed in Nov-2022 by a joint venture that included a Catamarca construction company. The business is not to replace the global firm: it is to sell it hours. Detailed piping and structural engineering, as-built, document control, fabrication inspection, weld control and assisted commissioning — the layer the EPCM subcontracts and that today arrives from Rosario, from Salta or from Sydney.
A double window: two plants entered commissioning in Q2-2026 (as-built and document close-out are being bought NOW) and the construction front closes in 2029; afterwards the perpetual operating core remains, smaller and recurring.
On this page
What the market is made of
The TAM is activity, not what you will invoice. The high layer —the EPCM, the basic engineering, the technical report signed by a Canadian, the vendor's technology package— is captive and will stay that way: it is not bought in Catamarca and it will not be. And there is a less obvious captive that is larger than it looks: the technical office the construction contractor includes in its price from Rosario, and the design the operator standardizes once and replicates. Your gap is the intermediate layer that gets subcontracted: piping and structural detail, as-built, document control, fabrication inspection, weld control and assisted commissioning.
~USD 5.7-6.7 M/year (60-70% of the midpoint TAM): the entire high layer (EPCM, basic engineering, FEED, capital estimates, NI 43-101/JORC, hydrogeology, technology vendors' packages); the engineering Rio Tinto centralizes and replicates under 'Design One, Build Many' — it owns 2 of the 4 assets, and a replicable design is paid for once and copied; Zijin's and POSCO's own chains, where the engineering travels with the equipment and with the contractor of origin; and the technical office that the extra-provincial contractor includes in its construction price.
~USD 2.9-3.8 M/year (30-40% of the midpoint TAM) addressable by a local or domestic entrant: detailed engineering by package, as-built, construction document control, fabrication inspection, weld quality control and NDT, assisted commissioning, surveying and construction planning.
See the full breakdown
USD 0.5-1.2 M/year for ONE entrant within 2-3 years = 11,000-25,000 h/year = a 6 to 13 person practice. A realistic composition: a document control + as-built contract on one site (year 1), an inspection/NDT package sold to two operators (year 1-2), a piping detailed engineering package via a joint venture with the EPC of the day (year 2-3). It is SME-sized, it is profitable and it is replicable to Salta and Jujuy — it is not a unicorn.
Who really pays?
The obvious name —«the mine»— is almost never the door in this line. Engineering is contracted in a chain, and each link buys something different:
Sal de Vida's Stage 1 capital estimate was prepared by a global engineering firm; the NI 43-101 was signed by a foreign studies firm; the Stage 2 capex, by another foreign firm. This door is closed and it is worth saying so: it demands a track record, a Qualified Person with a recognized license and professional indemnity insurance.
Sal de Vida's technical report says the works are executed under an EPCM model and that the estimate includes site technical staffing and third-party consultants. The entrant sells hours to that contractor: at Sal de Vida, the EPC joint venture (USD 130 M) is exactly the kind of client-partner you invoice.
It is the only door where the operator contracts directly and where having a local office plays in your favor thesis: Rio Tinto runs its own supplier development program in Catamarca (+50 suppliers trained, 800 hours of assistance, +60% in requests for quotation) verif and the 2nd Mining Suppliers Meeting of May 2026 drew more than 500 suppliers with Rio Tinto, POSCO, Galan and MARA seated as buyers prob.
Which projects move this demand
Expansion (Phase 1B) of the historic Fénix lithium-carbonate project in the Salar del Hombre Muerto, operated by Rio Tinto via Minera del Altiplano…
see the project →Lithium brine project in the Salar del Hombre Muerto (western zone), to produce 12,000 t/yr of lithium carbonate equivalent…
see the project →Tres Quebradas stage 2: plant and infrastructure for 40,000 t/year of lithium carbonate via direct extraction (DLE), per art…
see the project →Catamarca's largest copper project and the largest capital investment in the province. MARA integrates the Agua Rica deposit (Andalgalá)…
see the project →When the window opens
In this category engineering runs ahead of construction by 12 to 24 months, so what you watch is not the site: it is the act of state that authorises it, and the procedure that lets you bid for it. The three acts have already set the dates: Fénix Expansión Fase 1B until 1 December 2026, Tres Quebradas 2nd stage until 30 November 2027 (with 40 % of the minimum in the first two years) and Hombre Muerto Oeste until 31 December 2029. Tres Quebradas started construction on 1 June 2026 and its operation is scheduled for 1 April 2029. These four numbers are the ones that give notice.
See the evidence
See the evidence
See the evidence
Today it plays in favor: Q2-2026 averaged USD 22,043/t spot CIF Asia, +125% y/y in the first half, and closed the quarter at 19,400 verif Rio Tinto Q2-2026 filing with the SEC.
See the evidence
The specific killer and the most likely one. Rio Tinto states it wants to define the best-in-class DLE standard and standardize 'Design One, Build Many', and it owns 2 of the 4 Catamarca assets.
See the evidence
A done deal, not a threat: HMW's nanofiltration plant was built and tested IN SYDNEY before being shipped.
See the evidence
Tres Quebradas 2nd stage now has its act: the resolution was published on 29-Jul-2026 and it computes USD 594,136,000 in computable assets against the USD 709 M announced verif.
See the evidence
See the remaining 4 risks
The 50/50 split of royalties, taxes and levies on the disputed strip of the Salar del Hombre Muerto becomes void once Congress settles the boundary, and the winning province becomes the sole authority (Salta claims 134 of the salar's 586 km2; the boundary has been undefined since the National Territory of Los Andes was dissolved in 1943).
See the evidence
In Jun-2026 CAPROMITI (Tinogasta) claimed that Zijin-Liex had hired a trucking company from Córdoba and threatened road blockades in Fiambalá, with the Cámara de Transporte de Catamarca joining in and the Cámara Económica de Fiambalá demanding that local-content purchasing be enforced prob provincial press.
See the evidence
Past the peak, project engineering falls and the recurring core remains: live as-built, plant document control, integrity inspection of tanks and piping, NDT, plant turnarounds, de-bottlenecking and brownfield work.
See the evidence
Ley Impositiva 5.927: turnover tax on 'Mining support services' (code 99000) = 3.0% / 3.9% / 4.8% by bracket, against 0.75% for extraction (code 89120) verif art. 15 of the text published in the Official Gazette.
See the evidence
The opportunity in depth
The opportunity in depth
Document control and as-built. The document close-out, the as-built and the punch-list are end-of-construction work that cannot be deferred — with no quality report there is no plant acceptance. Entry capital is practically nil; the barrier is method, not money.
Fabrication inspection and weld control. The embryonic capability is already in the province: seven suppliers in the registry do hydraulic testing and thickness checks. What is missing is the inspector certified in non-destructive testing and the package sold as a third-party service. The demand is measured: Fénix's civil works contract alone includes 4, 6 and 8 inch above-ground and buried piping, a fire water network, earthing and a water pipeline.
With proven execution, the detailed piping and structural engineering — and the vehicle that makes it possible: the joint venture with a local partner. The provincial registry admits it with at least 50% local suppliers, and the precedent already exists: a Catamarca construction company entered the USD 130 M EPC for Sal de Vida's carbonate plant that way, in Nov-2022. It is the only documented one, so what it proves is that the vehicle works —not that there is an open package waiting for you. A Catamarca practice inside a joint venture does not compete with the global firm: it sells it hours.
See the detail
When you get paid, and what blocks it
already in
split
The primary source evidences that they prepared the capital estimate for Sal de Vida's Stage 1 (§21.2.1, verbatim). The EPCM contract is attributed to them by the press: the technical report speaks of 'the EPCM contractor' WITHOUT naming it and §25.16 treats it as a risk ('the EPCM approach is new to Galaxy'). EPCM role = prob, not verif. You do not compete with them: you sell them hours.
Author of the NI 43-101 (effective Mar 31, 2022) and co-author of the 2021 EIA with another consultancy. A barrier locked by a Qualified Person with a recognized professional license and professional indemnity insurance: this is not the gap.
A second foreign studies firm on the same asset: it confirms that even the estimate for a later stage is bought abroad.
Engineering + manufacture and testing of the nanofiltration plant IN sydney (99% sulfate removal), shipped containerized to Catamarca in early 2026; an offtake and operating partner since Apr-2025. It is the physical proof that vendor engineering travels with the equipment.
See the remaining 5 players
Rio Tinto states 'Design One, Build Many', 'early EPC engagement' and 'supplier led solutions' and owns 2 of the 4 assets (Fénix and Sal de Vida): a replicable design is paid for ONCE and copied. Zijin executes with its own chain (3Q's geomembranes in 20 truckloads from China via the Paso San Francisco). Regarding POSCO, some attendees at a plenary session of the Catamarca mining suppliers' chamber, in Belén in February 2026, said that POSCO brought its own suppliers from Korea for the construction of its plant and that, once it was finished, it turned them into service companies prob.
They bring their own site engineering, planning, surveying and QA-QC INSIDE the construction price. This is the incumbent the entrant actually displaces, not the global firm.
Local partner in the joint venture for the EPC of Sal de Vida's carbonate plant (USD 130 M, Nov-2022) alongside two contractors from other provinces, with a clause giving priority hiring to residents of Antofagasta de la Sierra under a 70/30 policy. It is the template of the entry vehicle, not an engineering competitor. It is the only documented local precedent of entry into a large package via a joint venture, and it is from 2022: it proves the door opens, not that there is a live contract today.
The category verbatim includes 'Planning, coordination, execution and control of projects', 'Plant maintenance' and 'Sampling, processing and analysis of samples'. Add PPE (7 members, which includes 'hydraulic testing of pressure equipment, thickness checks' = embryonic NDT). The registry has NO category of its own for EPCM engineering or construction management: the gap is one of scale, certification and capability, not of existence.
It offers the complete pond package with geological/geotechnical assessment, design and supervision; +300 professionals in its drilling division. A natural regional competitor — and a candidate partner for the Salta-Catamarca arbitrage.
The jobs it createsIt is the double-audience niche with the strongest argument in the whole chain, and the smallest in headcount — both things are true. La lectura completa para el que busca trabajo, en la hoja de este nicho para la gente →
calculate it
The number is our own estimate. The calculation, step by step, is below.
The full calculation, step by step
Concentration Two layers with opposite concentrations. THE high layer (EPCM, basic engineering, FEED, NI 43-101/JORC, hydrogeology, technology packages): total concentration and 100% foreign — an effective HHI tending to 1 per package, because each project has ONE EPCM and ONE technical report author, and there is not a single Catamarca or even Argentine firm documented signing basic engineering in the province.The middle layer (what the EPCM subcontracts: piping and structural detail, as-built, document control, fabrication inspection, weld control and NDT, assisted commissioning): fragmented and hollow — the Re.P.E.M. went from 31 (2022) to 229 active suppliers (May-2026) with 75 of 194 in the capital and only 12 in Antofagasta de la Sierra, and the professional services category declares 7 members against four simultaneous construction sites. The definitive share is NOT divided among incumbents: it is decided by whether the operator internalizes (the 'Design One, Build Many' doctrine) and whether the construction contractor keeps bringing its technical office from Rosario.
The rule that moves it
The driver of this niche is twofold and pulls both ways. In favor: the Re.P.E.M. —the provincial registry of mining suppliers— reserves the market for whoever has real roots in Catamarca and admits entry via a joint venture with at least 50% local partners, while the local-content commitments in the RIGI case files (95.34% at Hombre Muerto Oeste, the highest among the Catamarca projects that disclose it; 60% at Fénix) widen the door. Against: Ley Impositiva 5.927 charges 3.0% to 4.8% of Turnover tax on mining support services against 0.75% on extraction, and adds 1.5% of Stamp tax on the supplier's purchase order (art. 26 subsec. 2; the 2% of subsec. 1 taxes acts over mining rights, which are not the supplier's) — in an hours business, that eats a fifth of the bottom line.
See the underlying reading
The underlying policy that opens up this demand. It is the same inference declared by the rules and the program pillars pushing in this direction.
the RIGI promise is kept + without controls, supply responds to the boomSee the full legal grounds
Where the number comes from
~USD 9.5 M/year at the midpoint; the band is USD 8-11 M/year, equivalent to some 200,000 man-hours a year — on the order of 100 professionals and technicians across the four sites, and that count is a ceiling. And there is an option that changes the scale: MARA / Agua Rica —USD 4,000 M of capex, 77% of the province's announced portfolio— is not counted here because it has neither an FID nor an exploitation environmental permit. If it is unblocked, its engineering is worth on the order of USD 112 M, i.e. 22-28 M/year over 4-5 years: almost 3× this niche. It is copper and calls for a different specialty, so it is not the same client —but it is the ceiling worth looking at before sizing a practice
See the calculation, the variables and how it was validated
The TAM is built from three variables you can watch: how much capex has live construction in the province, what percentage of that capex goes to engineering and control, and over how many years it is executed. Change one and the number is recalculated.
A check on robustness and on fragility. Robustness: the 2.8% ratio is far more reliable than the absolute amounts, because numerator and denominator come from the same table and share a price base. Fragility, stated head-on: Tres Quebradas stage 2 is 63% of the capex still to execute, and since 29 July 2026 it has its resolution published: the risk hanging over this figure is closed. What remains is the base, and it is chosen: the act computes USD 594 million in computable assets and the announcement said 709 of total investment. They are different magnitudes —the computable one is the base of the tax benefit, not the spend on the works— and the basket uses total investment in its four rows.
The number rests on a few variables. The formula shows how it moves when each one changes; and each variable carries its freshness seal — how often it is worth revisiting. estim
We opened the anchor for the number ourselves: we downloaded Sal de Vida's technical report —289 pages— and read its capital cost table. Line by line, it says that the engineering and studies cost USD 25 million on a capex of USD 902 million: 2.8% of the works. We applied that real percentage to the Catamarca projects with live construction today, one by one and with the source of each amount —an Official Gazette resolution, the RIGI portal or the Mining Secretariat's official portfolio— and we state which base each figure uses so as not to add apples to oranges. The annual total is our own estimate and we say so. And we also say what we did not find: there is no public price for an engineering hour in Argentina —we looked, including at the professional councils— so the rate we use to translate dollars into jobs is an explicit assumption, not a figure. And on the act that weighs most in the number: as of 25 July 2026 the Tres Quebradas stage 2 resolution was not published —we checked it by sweeping 1,882 notices of the Boletín Oficial verif— and it came out four days later, on 29 July, computing USD 594 million in computable assets. That number does not contradict the USD 709 M of the announcement: it measures something else —computable assets are the base of the RIGI benefit, not the project's spend— and in this same basket Fénix 1B declares USD 531 M of investment against USD 251 M of computable.
Coverage: CAPPROMIN's category map, the provincial chamber of mining suppliers (123 memberships as of 2023, of which 7 declare hydraulic testing and thickness control and 1 insurance) · Sep 14, 2026 · not reviewed: the two provincial registers that rule here do not publish who is enrolled: neither the Re.P.E.M. —only the total— nor the Registro Único de Consultores Expertos Mineros y/o Ambientales, which mining companies are obliged to consult; and the engineering professional council's register of licensed members was not reviewed either
How to cite this figure: Despegue (2026). Detailed engineering, inspection and construction document control (Catamarca) · Catamarca. despegueargentina.com/en/catamarca/ingenieria-detalle-inspeccion-obra · terms of use
Neighbouring markets2 markets in the same group, from USD 0,8 to USD 95 M a year
We look at what your company does and tell you whether we see a sign that it fits this market, with the evidence behind it. If we do not see one, we say so too and name the condition that would change it. One page as a dated PDF, within 48 working hours.
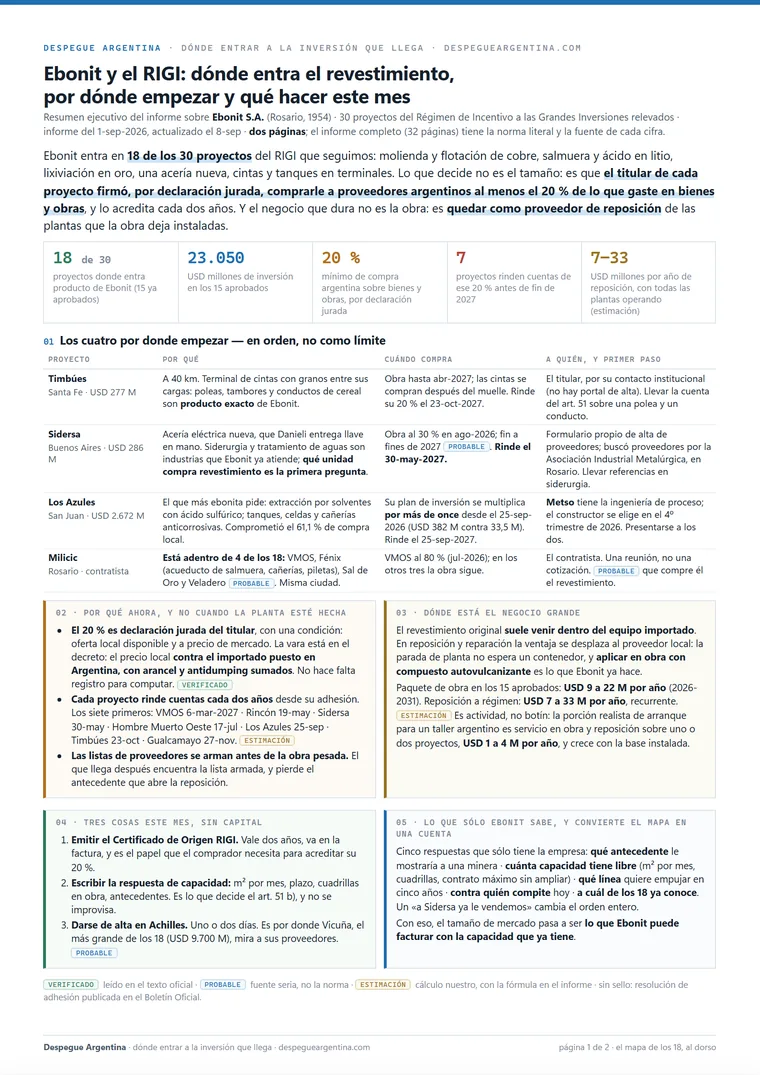 Open the report ↗A real analysis · a real company, open in full →
- 20+ years in technology, 15 of them in data and AI, for clients across Europe and the Americas
- Certified in AI governance (ISO/IEC 42001)
- Machine Learning (Google Cloud)
- Registered expert with the European Commission