Despegue TO INVEST · CATAMARCA ESEN
up to date · reviewed Aug 18, 2026 · for investors
NOA

What is being invested in Catamarca

USD5,177 million · RIGI portfolio announced across 4 projects · each amount with its source ↓
USD 1,177 M approved · 3 projectsUSD 4,000 M submitted/announced · under review

Every project in this portfolio, with its sponsor, where it stands under the RIGI and which tax regime applies to it. Below: the province’s indicators, the rules that affect it, what is still in the pipeline and our reading of where it is heading.

◣ NOA· PROVINCE PROFILE

Catamarca

Mining accounts for 96% of what it exports · in one of the two RIGI files the reported local-content commitment reaches 95%
ECON. RANKING
22nd
BY PROVINCE
Raúl Alejandro Jalil
● PROVINCIAL GOVERNOR
Raúl Alejandro Jalil verif ↗since Dec/2019
⚑ Producing lithium since 1997: one of the country's oldest direct-extraction operations still running
POPULATION verif ↗
429,562
inhabitants · 2022 Census
% OF NATIONAL GVA verif ↗
0.65%
22nd economy in the country · CEPAL data, 2024
MINING / GRP verif ↗
9.69%
3rd provincial sector · 2024 · the 1st is public administration (13.28%)
MINING / EXPORTS verif ↗
96.4%
April 2026 · the highest ratio of the five mining provinces
See the full Catamarca profile — how the economy is made up, alignment with the national government and tax regime
What the economy is made of· share of provincial GVA, 2024
Public administration13.3%
Retail, wholesale and repairs12.1%
Metal mining9.7%
Communications7.9%
Construction7.6%
Public education7.5%
Housing (imputed rent)5.5%
Agriculture and livestock4.2%
Public health4.0%
Private health3.2%
Rest of the economy (35 sectors)25.2%
Public administration13.3%
Retail, wholesale and repairs12.1%
Metal mining9.7%
Communications7.9%
Construction7.6%
Public education7.5%
Housing (imputed rent)5.5%
Agriculture and livestock4.2%
Public health4.0%
Private health3.2%
Rest of the economy (35 sectors)25.2%
Alignment with the federal government· our reading unconf Jul 25, 2026
Alignment by deeds / pro-RIGI peronismour own interpretation, anchored in the verified facts ↓

Alignment by actions, not by party label: Catamarca has a Peronist governor and still joined the RIGI through Ley 5863 in September 2024, with an express reservation of provincial jurisdiction in its article 2. On that basis the province today has three lithium projects with a RIGI resolution published in the Official Gazette -Fenix (Res 431/2026), Hombre Muerto Oeste (Res 1271/2025) and Tres Quebradas (Res 1153/2026, Official Gazette of Jul 29, 2026)-. It is the case that shows alignment with the national program is read in the acts —the accession, the resolutions, the tax regime— and not in the governor's political color.

Tax and resource-rent regime· Turnover tax, royalties and carry
UPSTREAM TURNOVER TAX verif Dec 19, 2025 ↗
0.75%
metalliferous extraction and lithium brine · all three brackets
SERVICES TURNOVER TAX verif Dec 19, 2025 ↗
3.00% to 4.80%
mining support services, by revenue bracket
MINING ROYALTIES verif Nov 12, 2024 ↗
3%
cap set by Ley nacional 24,196 · 30-year fiscal stability · how the province settles them: primary source pending
LOCAL CONTENT COMMITTED UNDER THE RIGI verif ↗
95.34% / 60%
Hombre Muerto Oeste / Fénix · of everything each project declares it will pay suppliers, the share that goes to local suppliers; under the RIGI «local» = Argentine, not from Catamarca

Catamarca levies no new taxes on the mine: extraction pays 0.75% turnover tax and royalties capped at the 3% of Ley nacional 24.196. It does tax the supplier: 3.00% to 4.80% turnover tax by revenue, plus 1.5% stamp tax on the purchase order (Ley Impositiva 5.927, section 26, subsection 2). And its local-content rule is not a law —it is Resolución SEM 498/2014, which created the Re.P.E.M. and can be repealed by another resolution—: today the most binding commitment travels in the RIGI filing, where Hombre Muerto Oeste declared that 95.34% of what it pays suppliers will go to local suppliers and Fénix 60%, against a legal minimum of 20%. Mind the small print: the resolution estimates that percentage (it does not set it as an obligation by line of business) and under the RIGI "local suppliers" means Argentine, not from Catamarca — a Catamarca firm competes inside that number against the whole country.

Fiscal regime & incentives in detail
Mining royalties: Ley provincial 4.757 is the parent statute and Ley 5.871 (passed 10-Oct-2024, official gazette 12-Nov-2024, adhering to art. 103 of Ley nacional 27.743) set the regime in force: a general rate of 3% and, for projects that had NOT started construction before it took effect, a percentage 'no lower than three per cent (3%) and no higher than five per cent (5%)'. The base is mine-mouth value, with an anti-avoidance floor: if the declared value is below the national or international market value, the market value applies. Art. 3: any Executive agreement setting a royalty below the maximum must be ratified by the Legislature. Distribution (Ley 5.642, passed 5-Jun-2020, official gazette 7-Jul-2020): 35% to the department where the deposit sits, 5% to the departments that supply water resources to deposits in other departments and 60% to the Province; all of the revenue must be channelled through trust funds reporting every six months to the Finance Committees, and municipalities PROPOSE works rather than deciding them. Real fiscal weight: the mining royalties line of the 2026 Budget is $7,256,897,984 = 0.28% of the province's total resources — mining does not fund Catamarca through royalties. verif Nov 12, 2024 ↗
Turnover tax 2026 (Ley Impositiva 5.927, Annex I): extraction of metalliferous minerals (codes 71000/72990) and extraction of minerals for the manufacture of chemical products —lithium brine— (code 89120) at 0.75% across all three brackets. Lithium concentrate industry (code 329099-1) and lithium compounds industry (code 329099-2) at 1.50%: these are codes the province created ad hoc. Support services for mining other than oil and gas (code 99000) at 3.00% / 3.90% / 4.80% depending on the bracket; rental of mining machinery and equipment without operators (code 773020), the same; wholesale of metals and metalliferous minerals (code 466200) at 2.50% / 4.00% / 5.00%; sales on commission or consignment of minerals, metals and industrial chemicals (code 461093) at 5.00% / 6.50% / 8.00%. Brackets by total gross income for 2025 (art. 15): Bracket I up to $3,255,000,000; Bracket II up to $26,970,000,000; Bracket III above that. Art. 16: any taxpayer starting activity from 1-Jan-2026 pays at Bracket I for its entire first financial year. The asymmetry that matters: whoever extracts pays 0.75% and whoever supplies services pays 3.00% to 4.80% — between 4 and 6.4 times more. verif Dec 19, 2025 ↗
Stamp tax 2026: Ley Impositiva 5.927 has a chapter of its own for the sector (art. 26, 'Acts, contracts and operations linked to non-renewable natural resources — mining sector'), with two subsections. Subsection 1 — 2%: acts, contracts, agreements, assignments of shares and rights, mining concessions and instruments and operations linked to mining rights or mines in general; loan contracts; leases and subleases of movable property and of mining infrastructure works; obligations to pay sums of money under mining legal acts; terminations of mining contracts by public instrument; creation, transfer or extinction of mining surface rights in rem; transfer of real property as a capital contribution to mining companies; and deeds creating, extending or renewing rights in rem over real property used for mining activity. Subsection 2 — 1.5%: total or partial cancellation of rights in rem in mining activities; purchase and sale of real property for mining activities; leases and subleases of movable and immovable property, works and services and their assignments linked to mining at any stage; and 'acts, contracts, purchase orders, agreements and operations in general for mining activities, their mining suppliers and any venture linked to the mining sector'. In other words: the mining supplier's purchase order pays 1.5%. By contrast: the general stamp regime for commercial and civil contracts was taken to 0% (art. 21), so mining and its chain are among the few operations still taxed. Bidding for a public tender also costs 0.1% of the amount bid, and 0.05% in a private tender, price competition or public works process (art. 30). verif Dec 19, 2025 ↗
RIGI accession: Ley provincial 5.863, passed on 19-Sep-2024 and published in the provincial official gazette on 27-Sep-2024. Art. 1: it adheres 'in all its terms' to Title VII of Ley Nacional 27.742. Art. 2: the accession is made 'reaffirming the competence, jurisdiction and legislation in force of the Province of Catamarca' — it is an accession with an express reservation of its own jurisdiction, not a delegation. The available text does not specify which provincial taxes it stabilizes, nor does it set a local-content or local-employment clause: in practice that lives in the Re.P.E.M. and in the commitments of each RIGI filing. verif Sep 19, 2024 ↗

Key indicators

Catamarca
thesiswhy these are the key indicators lowers country risk

The three indicators say the same thing from three angles. Catamarca is the country's 22nd-largest economy and mining is only its third sector —9.69% of output, behind public administration and commerce— and yet it accounts for 96.4% of what the province exports: the highest ratio among Argentina's five mining provinces. That gap between 9.69% and 96.4% is the whole province: every private dollar that comes in passes through a pipe that weighs less than a tenth of output, which is why whatever happens to that pipe shows up immediately and with no cushion. Antofagasta de la Sierra, the department that hosts the Salar del Hombre Muerto, grew 40.8% between censuses while the province grew 16.8%; mining employment already sustains 7,722 jobs —8.1% of private employment— with three quarters of the workforce hired locally. What the three numbers mark is not a mature mining economy: it is one that is plugging itself in right now, with four lithium operations starting up within the same twelve-month window.

What cools it downThe price of lithium carbonate and the environmental permit for Agua Rica. The entire portfolio under execution is brine lithium: a price sustained below the cash cost of evaporitic operations halts expansions first, and expansions are precisely the ones that buy services. And the province's largest capex —the USD 4,000 M of MARA/Agua Rica, filed under the RIGI in August 2025 and announced as approved by the company on 2-Oct-2026— is not waiting on geology or on tax terms: it is waiting on an exploitation environmental permit that has not yet been filed, with an open judicial front.
95.1%
of what Catamarca exports is mining (January-August 2026), the highest ratio among the five exporting mining provinces
the full data
In January-August 2026 mining accounted for 95.1% of Catamarca's total exports (90.3% in August): the highest share among the five exporting mining provinces (Jujuy 88.3%, Santa Cruz 87.8%, San Juan 87.6%, Salta 62.1% in the cumulative). Catamarca exported USD 419 M in minerals over those eight months, 6.9% of the country's mining total. Across the three NOA provinces together (Catamarca, Jujuy and Salta), August mining exports were USD 252 M (+79.3% year on year) and USD 2,281 M in the cumulative (+113.0%), with lithium accounting for 64.3% of the basket and China as the destination of 67.1%.
+40.8%
growth in Antofagasta de la Sierra, the department of the lithium salt flat — on a base of 1,436 people
the full data
Antofagasta de la Sierra, the department that hosts the Salar del Hombre Muerto (Fénix, Sal de Vida, Hombre Muerto Oeste, Sal de Oro), went from 1,436 inhabitants in 2010 to 2,022 in 2022: +40.8%, the largest relative change among Catamarca's 16 departments, against +16.8% for the province. It covers 28,108.7 km² —27.7% of the provincial territory— with a density of 0.1 inhabitants per km², the lowest in the province verif. At the other end, Andalgalá (home to Agua Rica, Glencore's copper project, which announced its RIGI approval on 2-Oct-2026 prob) grew by just 8.5%.
7,722
mining jobs in a province of 429,562 people — 8.1% of private employment
the full data
As of December 2025 mining sustained 7,722 jobs in Catamarca: 2,888 direct (37.4%) and 4,834 indirect (62.6%). Its weight in provincial private employment rose from 7.5% (2023) to 8.1% (2025). Local labor is 76.6% of the workforce and the sector's payroll exceeds $19,309 million per month, with an average wage of $2.87 million in direct employment against $1.73 million in indirect work — satellite jobs pay about 40% less. Territorial concentration: Belén 13.8%, Santa María 12.6% and Andalgalá 10.3%.

Investment climate

analyst reading

Catamarca has been producing lithium since 1997: one of the country's oldest direct-extraction operations still running sits in the Salar del Hombre Muerto.

What is new is not the mineral, it is the simultaneity. Within a single twelve-month window four operations started up —the Fénix Phase 1B expansion, Sal de Vida, Tres Quebradas and Hombre Muerto Oeste— and the province entered the RIGI with three resolutions of its own already published in the Official Gazette —Tres Quebradas closed its own, Resolución 1153/2026 of 29-Jul-2026—. It is a small portfolio in dollar terms compared with San Juan's copper or Neuquén's shale, and that is exactly why you enter differently here: the business is not the mega-project, it is supplying it.

See the full analysis

What makes this province unique is written into a national case file rather than a provincial law: the RIGI resolutions for Hombre Muerto Oeste and Fénix declare that 95.34% and 60% of what each project pays suppliers will go to local suppliers, against a regime minimum of 20%. That is demand for services put in writing before a national authority. On the other side, local supply does not exist in entire categories —metalworking and boilermaking, process chemistry, instrumentation, certified chemical laboratory, geomembranes, detail engineering, plant mechanical maintenance— facing four simultaneous construction sites at 4,000 meters of altitude. The provincial register of mining suppliers went from 31 in 2022 to 229 in 2026, and it still falls short of what is coming.

Two things need to be said head-on, because they change the play. The first is fiscal: the provincial Tax Law charges 0.75% turnover tax on extraction and between 3.00% and 4.80% on mining support services —4 to 6 times more— with 1.5% stamp tax on the mining supplier's purchase order, while the general regime for commercial contracts was taken to 0%. The second is about access: the provincial supplier register requires a domicile with two years of standing, and the door the rule itself leaves open is the joint venture with a local partner. Entering now means entering with construction already contracting and the supplier market still to be built.

What to watch

Confidence holds by facing head-on what tests it. The factors to follow closely:

  • The price of lithium carbonate. The province's entire portfolio under execution is brine lithium, and demand for services is generated by expansions before operations: a price sustained below the cash cost of evaporitic operations halts first what is being built. It is the most external vector of all —it is set by the global market, and China is the destination of 71.6% of the NOA mining basket— and it can be tracked month by month.
  • The boundary with Salta in the Salar del Hombre Muerto. In January 2026 the two provinces created inter-provincial authorities by law, together with a 50/50 split of royalties and taxes from the disputed area, but the ninth clause of the agreement lapses once Congress settles the boundary: at that point the winning province becomes the sole authority. In the meantime, the effective royalty rate per project is not public either —the provincial law sets 3% in general and 3% to 5% for projects that had not started construction—. It is the institutional risk of the entire salar, and it is settled outside the province.
  • The copper environmental license and the water front. Catamarca's largest capital —the USD 4,000 M of MARA/Agua Rica, with its RIGI approval announced by the company on 2-Oct-2026— is waiting on an exploitation environmental permit that has not been filed, with an open judicial front. And the injunction that suspended activity in the salar in March 2024 was lifted in April 2026 conditional on continuous monitoring and community participation: the conditionality is the new normal, and breaching it reopens the risk.

RIGI portfolio · Catamarca

4 projects · USD 5,177 M

This portfolio is the province’s engine: each megaproject drives years of demand for services, energy, water, sand and logistics. For most investors, the entry point is in that wake — the map below.

ProjectSectorStatusUSD M
Agua Rica / MARA — copper, gold, silver and molybdenum (Glencore)Mining - Copper (with gold, silver and molybdenum as by-products)submitted verif ↗USD 4,000 Mthe amount used in the RIGI application · midpoint of the declared USD 3,500-4,500 M range · It is NOT the project's capex: the latest capex figure declared by the company itself is USD 6,699 M May-2026, probable
see the project

Catamarca's largest copper project and the largest capital investment in the province. See the full project →

What this figure measuresThe amount announced by the company or the government.
Filing statusFiled and under review. The Comité Evaluador approved its admission according to the national Government's official statement of 2 October 2026 prob; as of 2 October 2026 the resolution had not appeared in the Official Gazette. The application was announced on 18 August 2025, the same day as El Pachón (San Juan), which as of 2 October 2026 was still under review prob. It is Catamarca's largest investment amount and the province's only copper project: once the resolution is published, it would more than triple Catamarca's RIGI portfolio estim. The environmental permit for exploitation was filed on 9 September 2026 and is under review at Catamarca's Ministry of Mining prob; that permit, the court challenges and the social license in Andalgalá are today the main brake thesis. prob Oct 2, 2026 ↗
CompaniesMinera Agua Rica LLC, Argentine Branch; 100% controlled by Glencore International AG since 31-Jul-2023 (previously Yamana Gold 56.25% / Glencore 25% / Newmont 18.75%). Pan American Silver retains a 0.75% NSR royalty on copper for the life of the mine.
Demand it drives
highmediumopportunityintensity = market size (estimate)
What it will need and has no supplier yetthesis 6 services this project will need and has no identified supplier for yet. Which ones, in the report →
Salar Tres Quebradas (3Q), stage 2 — lithium carbonate (LIEX/Zijin)Mining - Lithium (carbonate)approved prob ↗USD 709 M
see the project

Tres Quebradas stage 2: plant and infrastructure for 40,000 t/year of lithium carbonate via direct extraction (DLE), per art. 1 of Resolución 1153/2026 (all stages combined target 60,000-80,000 tpa, projected). See the full project →

What this figure measuresThe amount announced by the company or the government.
ApprovalResolución 1153/2026 of the Ministry of Economy (RESOL-2026-1153-APN-MEC), issued on Jul 27, 2026 and published in the Official Gazette on Jul 29, 2026 (notice 345075). verif Jul 29, 2026 ↗
Filing statusApproved and admitted into the RIGI by Resolución 1153/2026 of the Ministry of Economy, published in the Official Gazette on Jul 29, 2026 (Mining sector, potassium and lithium subsector). Article 2 sets the accession date at Jul 3, 2026. This is the 2nd expansion stage: a 40,000 t/yr lithium carbonate plant using direct extraction (the 1st stage has been operating since Sep 2025 at ~20,000 t/yr). verif Jul 29, 2026 ↗
CompaniesLiex S.A. Sucursal Dedicada, CUIT 30-71929244-1; according to the press, a subsidiary of China's Zijin Mining group
What it will need and has no supplier yetthesis 2 services this project will need and has no identified supplier for yet. Which ones, in the report →
Fénix — Phase 1B Expansion: lithium carbonate (Minera del Altiplano / Rio Tinto)Mining - Lithium (carbonate)approved verif ↗USD 251 Meligible assets of the Phase 1B Expansion, Res 431/2026 · Rio Tinto's broader expansion is announced at ~530 M
see the project

Expansion (Phase 1B) of the historic Fénix lithium-carbonate project in the Salar del Hombre Muerto, operated by Rio Tinto via Minera del Altiplano. See the full project →

What this figure measuresOnly the assets the regime counts. The project’s total investment may be higher.
ApprovalResolución 431/2026 of the Ministry of Economy (Official Gazette Apr 6, 2026, notice 340329) verif Apr 6, 2026 ↗
Filing statusRIGI accession approved by Resolución 431/2026 (Ministry of Economy). An expansion of a pre-existing project that is not itself an adherent: 'Phase 1B Expansion' — it adds 9,500 t/yr of lithium carbonate (28,500 → 38,000 t/yr). Construction status (Jul 2026): Phase 1B reached first production in the second quarter of 2026, ahead of plan, and remains in commissioning; Rio Tinto describes it as 10,000 t/yr of battery-grade carbonate. In the same salt flat and under the same owner, Sal de Vida (15,000 t/yr, conventional ponds) also reached first production ahead of schedule in Q2 2026. Base caveat: the resolution says 28,500 → 38,000 t/yr and the company says 20 → 30 ktpa from Phase 1A plus 10 ktpa from 1B = 40 ktpa: these are two different accountings of the same asset. verif Apr 6, 2026 ↗
CompaniesMinera del Altiplano S.A. Dedicated Branch (MDASD, CUIT 30-71906845-2); operated by Rio Tinto (formerly Arcadium/Livent)
What it will need and has no supplier yetthesis 2 services this project will need and has no identified supplier for yet. Which ones, in the report →
Hombre Muerto Oeste (HMW) — lithium carbonate (Galan)Mining - Lithiumapproved verif ↗USD 217 Mcomputable assets per Resolución 1271/2025 · the RIGI portal publishes 292 as committed investment = the total-investment base, not the computable one
see the project

Lithium brine project in the Salar del Hombre Muerto (western zone), to produce 12,000 t/yr of lithium carbonate equivalent. See the full project →

What this figure measuresOnly the assets the regime counts. The project’s total investment may be higher.
ApprovalResolución 1271/2025 of the Ministry of Economy (Official Gazette Aug 28, 2025; official summary at argentina.gob.ar/normativa, norma-416924) verif Aug 28, 2025 ↗
Filing statusRIGI accession approved by Resolución 1271/2025 (Ministry of Economy, issued Aug 27, 2025, Official Gazette Aug 28, 2025); accession filed Jul 17, 2025. Production of 12,000 t/yr of lithium carbonate equivalent. Minimum investment deadline: Dec 31, 2029. It commits that 95.34% of the investment amount EARMARKED FOR PAYING SUPPLIERS, goods and infrastructure works goes to LOCAL suppliers — not that this share of total investment goes to suppliers: it is the highest share among the approved projects that disclose the figure, against a regime floor of 20%. verif Aug 28, 2025 ↗
CompaniesGALAN LITIO SA (CUIT 30-71736364-3); RIGI vehicle: its Dedicated Branch (CUIT 30-71899846-4). Parent: Galan Lithium Ltd (ASX: GLN).
What it will need and has no supplier yetthesis 3 services this project will need and has no identified supplier for yet. Which ones, in the report →

The chain continues outside the province · 2 projects in Salta

RIGI works in Salta that build on Catamarca's resource: the value chain does not stop at the provincial border. They do not add to the provincial portfolio above.

ProjectSectorStatusUSD M
Diablillos — gold and silver (Salta/Catamarca)Mining - Gold and silverapproved verif ↗USD 764 Mtotal investment per the official RIGI portal · computable assets USD 481.7 M under Resolución 562/2026
see the project

Gold and silver mining in the puna, on the Salta/Catamarca border area: feasibility development, a 3.15 Mt/yr processing plant and full infrastructure. See the full project →

What this figure measuresThe amount announced by the company or the government.
ApprovalResolución 562/2026 of the Ministry of Economy (Official Gazette May 11, 2026; official summary at argentina.gob.ar/normativa, norma-425673) verif May 11, 2026 ↗
Filing statusRIGI accession APPROVED by Resolución 562/2026 (Ministry of Economy, Official Gazette May 11, 2026). Feasibility, a 3,150,000 t/yr gold and silver processing plant and associated infrastructure. verif May 11, 2026 ↗
CompaniesPACIFIC RIM MINING CORPORATION ARGENTINA S.A. (CUIT 30-67305977-1)
Demand it drives
highmediumopportunityintensity = market size (estimate)
What it will need and has no supplier yetthesis 3 services this project will need and has no identified supplier for yet. Which ones, in the report →
Sal de Oro II — lithium carbonate (POSCO)Mining - Lithium (carbonate)approved verif ↗USD 208 Min computable assets RIGI legal basis, Resolución 1157/2026 — do NOT mix with the total investment announced by the press, see note
see the project

Second stage of POSCO's Sal de Oro lithium complex in the Salar del Hombre Muerto, on the disputed Salta/Catamarca border strip: it adds a 23,000 t/yr lithium carbonate plant to the hydroxide plant opened in Oct-2024 in General Güemes (Salta). See the full project →

What this figure measuresOnly the assets the regime counts. The project’s total investment may be higher.
ApprovalResolución 1157/2026 of the Ministry of Economy (RESOL-2026-1157-APN-MEC), published in the Official Gazette on Jul 31, 2026, notice 345279 verif Jul 31, 2026 ↗
Filing statusApproved for RIGI by Resolución 1157/2026 of the Ministerio de Economía (Official Gazette of 31-Jul-2026): Single Project 'Sal de Oro II', Mining sector/Potassium and lithium subsector. Accession date: 12-Jun-2026. It is a 23,000 t/yr lithium carbonate plant; the hydroxide operation already running in the same project is described by the lender's environmental and social summary, not by the resolution. Jurisdiction: Resolución 1157/2026 does not assign a province (it is a federal act), but it confirms that the VPU's legal domicile is in Salta capital and that the project sits in the Salta/Catamarca border area of the Salar del Hombre Muerto — consistent with the 'Catamarca-Salta' attribution already carried by the Secretaría de Minería's 2025 Project Portfolio (probable, separate source). We count it only once, under Salta, so the amount is not double-counted in the portfolio, with its shared nature declared here. Local content: 21.02% of the investment amount earmarked for paying suppliers, goods and infrastructure works goes to local suppliers (verbatim from the recital; the base is NOT total investment). Milestone obligation (article 3): in the 1st and 2nd year counted from notification it must certify ≥40% of the minimum investment amount in computable assets. Deadline to reach the minimum amount (article 4): 31 July 2029. Background found only in the resolution: a first application dated 30-Oct-2024 was WITHDRAWN by Posco on 17-Nov-2025; the approved one is a new filing dated 15-Nov-2025, already under the dedicated-branch VPU. The declared object (carbonate by solar evaporation plus brine treatment with calcium oxide) is destined entirely for export. verif Jul 31, 2026 ↗
CompaniesPosco Argentina SAU SDE (dedicated special branch of Posco Argentina SAU), CUIT 30-71922048-3
Demand it drives
highmediumopportunityintensity = market size (estimate)
What it will need and has no supplier yetthesis 2 services this project will need and has no identified supplier for yet. Which ones, in the report →
🔧  To sell to the projectsWhat the projects in Catamarca are going to buy11 opportunities sizedUSD 227 M annual demand4 ecosystem companieseach with its USD TAM, its gap and its competitive map →

If you supply these projects rather than invest in them, we cross what your company does against them and tell you which ones it fits into: Where my company can get in →

Reforms that touch the province

26 in force · 1 in execution · 1 pending
The programme’s laws and deregulations that touch the province. A rule enters here once its text has appeared in the Boletín Oficial and we have read it: an announcement is not enough, not even from the government itself. Each one shows which rule it is and how much confidence we give it.
category
RIGI and investment7
▸RIGI: what paperwork you have to file afterwardsDecreto 749/2024in forceNATIONALAug 23, 2024
Impact on Catamarca: It concentrates three of the country's earliest accession dates (El Quemado, Fenix and Hombre Muerto Oeste), making it one of the first provinces where biennial certification stops being theory. The Re.P.E.M. register is what defines which local supplier counts. favorable stability → long-term investment thesis
in forceNATIONAL verif Aug 23, 2024 ↗
▸Re.P.E.M.: Catamarca's mining local-content rule is a resolution, not a lawRes. S.E.M. 498/2014in forcePROVINCIALJun 23, 2014
Impact on Catamarca: It is the lever that turns 'being from Catamarca' into a selling advantage: registering in the Re.P.E.M. is the entry procedure to a market that opens the lithium portfolio. The cost of entry is administrative (domicile, partners, payroll), not technical or capital — the real barrier is in the lines of business the province does not have (metalworking, process chemistry, instrumentation, certified laboratory, geomembranes, EPC), not in the register. favorable thesis
Its sub-legal rank is the regulatory risk of the supplier ecosystem: a secretariat resolution does not give long-term legal certainty to anyone investing in relocating. The provincial chamber has been asking for a law since 2019 and was still asking in 2026. mixed thesis
in forcePROVINCIAL verif Jun 23, 2014 ↗
▸Federal Registry of Mining Suppliers: it is public, and does not certify complianceRes. S.M. 84/2022in forceNATIONALNov 29, 2022
Impact on Catamarca: This is where the difference costs most: section 4 of Res. S.E.M. 498/14 orders that 70% of a mining company's annual contracting go to firms registered in the Re.P.E.M., which also requires a Catamarca address of at least two years' standing. Being on the RFPM counts for nothing towards that 70%. mixed stability → long-term investment thesis
in forceNATIONAL verif Nov 29, 2022 ↗
▸Salta: 70/60 local mining procurementSalta Ley 8164 (Official Gazette Oct 22, 2019)in forcePROVINCIAL2019
Impact on Catamarca: Salta's Ley 8164 requires 80% payroll and 51% ownership from Salta and rewards the compliant miner with up to 50% of the quarterly royalty as a transferable tax credit. Hombre Muerto is a shared salt flat with a 50/50 split since January 2026: the same supplier faces two incompatible definitions of «local», and on the Catamarca side the Re.P.E.M. is a secretariat resolution with no economic counterpart. adverse federal-provincial tension thesis
in forcePROVINCIAL verif 2019 ↗
▸Mining revenue does not go to the budget: it goes to a trust decided by a committee of threeDecreto Acuerdo 1055/2022 (amended by DA 1802/2022)in forcePROVINCIALMay 5, 2022
Impact on Catamarca: It turns mining revenue into work that can be executed quickly (a hospital, paving, housing on the puna) without going through the ordinary procurement circuit: it is the mechanism by which lithium becomes visible in town. For the contractor, the entry channel is each project's Works Manager. favorable thesis
The decision on which work to fund is taken by a committee of three provincial officials and the procurement sits outside the general regulation: the flip side of speed is discretion. The municipalities where the deposit sits only propose. It is a point to watch on transparency, not an accusation: Catamarca joined the EITI in 2023 and announced a mining transparency law. mixed thesis
in forcePROVINCIAL verif May 5, 2022 ↗
▸Salta and Catamarca split 50/50 what is extracted from the disputed strip, without settling the borderLey 5.940 (Catamarca)in forcePROVINCIALMay 22, 2026
Impact on Catamarca: It unlocks operations at the projects on the disputed strip without requiring the border to be settled first: investment moves ahead with written, shared fiscal rules instead of being held hostage to an eight-decade dispute. favorable thesis
The 50/50 split raises the compliance cost for the operator and the supplier: two tax administrations verify the same tonne without a published common measurement standard. It is an administrative burden for the mine, and demand for whoever can produce a number both will accept. mixed thesis
in forcePROVINCIAL verif May 22, 2026 ↗
▸Belgrano Cargas goes to tender: bids due 11 Nov 2026Resolution 1350/2026in forceNATIONALAug 20, 2026
Impact on Catamarca: Lithium currently leaves the Salar del Hombre Muerto and Tres Quebradas entirely by truck, and freight is pure cost for the supplier. The Belgrano line crosses the province: a private concessionaire with an investment obligation changes the calculation of how far out it makes sense to place a transfer yard. It is the weaker of the two inferences, because the official release does not list the provinces on the route. favorable cheaper to respond: investing takes time, held-back supply shows up at once thesis
in forceNATIONAL verif Aug 20, 2026 ↗
Fiscal and monetary anchor4
▸Fiscal anchor: surplus two years in a rowExecutive execution policy on the extended budget (Decreto 1131/2024)in forceNATIONALFeb 1, 2026
Impact on Catamarca: Two years of surplus are sustained with real cuts to spending, transfers and public works. Catamarca is where that lands differently because of its composition: public administration is its largest sector at 13.28% of provincial GDP and mining is third at 9.69%; adding public education and health, the state accounts for ~24.7% of value added, and mining royalties are 0.28% of provincial revenue. mixed thesis
in forceNATIONAL verif Feb 1, 2026 ↗
▸Catamarca 2026: extracting pays 0.75% turnover tax; serving the mine, 3% to 4.8%Ley 5927 - Decreto 1679 (Catamarca, 2025)in forcePROVINCIALDec 19, 2025
Impact on Catamarca: It sets the tax cost of each link in the mining chain: extracting 0.75%, processing lithium 1.5%, providing services 3% to 4.8%. It is the number against which a supplier from another province decides whether to set up and invoice in Catamarca. mixed federal-provincial tension thesis
in forcePROVINCIAL verif Dec 19, 2025 ↗
▸No excise duty on insurance, satellite or vehiclesLaw 27.802, arts. 189 and 195 (Titles XXIV and XXV)in forceNATIONALMar 6, 2026
Impact on Catamarca: Same as San Juan for the puna, plus one of its own: vines and olives in the Catamarca valley are irrigated by electric pumping, so moving irrigation electricity to the reduced VAT rate hits their main variable cost. favorable confirms the course thesis
in forceNATIONAL verif Mar 6, 2026 ↗
▸Losses indexed to CPI, citizenship without tax residenceLaw 27.802, arts. 190, 191 and 194 (Title XXIV)in forceNATIONALMar 6, 2026
Impact on Catamarca: Same mechanism in lithium: commissioning a carbonate plant involves a long period with no sales, and the accumulated tax loss is part of the expected return. favorable confirms the course thesis
in forceNATIONAL verif Mar 6, 2026 ↗
FX and exit from currency controls1
▸Dollar credit is no longer for exporters onlyDNU 736/2026 (Official Gazette, Aug 14, 2026) · BCRA Communication «A» 8467in forceNATIONALAug 14, 2026
Impact on Catamarca: DNU 736/2026 removes the requirement to hold export revenue in order to borrow in dollars. The Catamarca segments with no local supplier —geomembranes, certified chemical labs, instrumentation, brine drilling— all rely on imported equipment, and the supplier collects in pesos while paying 3.00-4.80% turnover tax plus 1.5% stamp duty on the purchase order. What holds it back is working capital, not demand. The instrument already exists: BCRA Communication «A» 8467 (Aug 18, 2026) enables it with a cap of 15% of each bank's dollar deposits and 25% more capital required. favorable cheaper to respond: investing takes time, held-back supply shows up at once thesis
in forceNATIONAL verif Aug 14, 2026 ↗
Trade opening1
▸Importing mining equipment duty-free: the list and the procedureResolution 73/2026 of the Mining Secretariat (Official Gazette, 1 Sep 2026), implementing s. 21 of Law 24,196in forceNATIONALSep 1, 2026
Impact on Catamarca: Producing lithium projects are the first candidates for the presumed useful life of s. 24: their surface equipment reaches ten years before copper's does, since copper started later. favorable
in forceNATIONAL verif Sep 1, 2026 ↗
Market deregulation4
▸Trucks: digital RUTA and the end of extra provincial requirementsDecreto 832/2024in forceNATIONALSep 13, 2024
Impact on Catamarca: Decreto 832/2024 makes the RUTA digital and free and bars provinces and municipalities from asking a registered interjurisdictional carrier for extra paperwork. Catamarca's lithium chain moves by truck — soda ash travels ~1,900 km and reagents are 40.9% of production spend — and Hombre Muerto is a bi-provincial salt flat with authorities created by law in 2026: the last mile up to the puna stops paying at two counters. favorable cheaper to respond: investing takes time, held-back supply shows up at once thesis
in forceNATIONAL verif Sep 13, 2024 ↗
▸Longer trucks: Annex R updated after 30 yearsDecreto 689/2026in forceNATIONALJul 31, 2026
Impact on Catamarca: Same mechanism as Salta on the approach to the puna, with a more demanding alignment: here provincial route-by-route approval matters more than the national rule. mixed opening and deregulation thesis
in forceNATIONAL verif Jul 31, 2026 ↗
▸Fuel self-service nationwideDecreto 46/2025 + Resolution (SE) 147/2025in forceNATIONALJan 28, 2025
Impact on Catamarca: Decreto 46/2025 does more than allow self-service: it authorizes above-ground storage tanks, mobile service stations and flexible minimum dimensions for installations. In Catamarca the 345 kV line and the pipeline to the puna are agreed and not a meter has been built, so the ceiling on the salt flat's works is diesel, in a district of 28,108 km² with 2,022 inhabitants. favorable cheaper to respond: investing takes time, held-back supply shows up at once thesis
in forceNATIONAL verif Jan 28, 2025 ↗
▸Aviation: provisional certificates to speed up operator entryANAC Res. 436/2026 (Official Gazette, Jul 13, 2026)in forceNATIONALJul 13, 2026
Impact on Catamarca: Resolución 436/2026 allows operating under a provisional certificate — air-work operator, aerial services, workshops — for 90 renewable days when only administrative steps are missing. In July 2026 the rescue of five workers on the salt flat was carried out by volunteer firefighters and a helicopter flown in from Buenos Aires: there is no air ambulance service based in the puna, and four operators coexist within a short radius. favorable cheaper to respond: investing takes time, held-back supply shows up at once thesis
in forceNATIONAL verif Jul 13, 2026 ↗
Energy and natural resources4
▸The State puts 16 high-voltage works out to tender, and six of them run through four of the five provincesRes. SE 202/2026 (Official Gazette, Aug 12, 2026), the Plan's first workin executionNATIONALAug 11, 2026
Impact on Catamarca: This is the province that changes the most if the plan is executed. Work 12 (Lavalle–Chumbicha) reinforces the central valley and work 13 climbs to Antofagasta de la Sierra, the heart of Catamarca's lithium and today running on its own diesel generation. Without a line, the scale ceiling of a Puna project is set by the fuel that can be trucked up; with a line, that ceiling moves and so does the size of everything that can be sold around it. favorable the bottleneck moves to transport thesis
in executionNATIONAL verif Aug 11, 2026 ↗
▸Mining: export duties to 0% for most productsDecreto 563/2025in forceNATIONALAug 6, 2025
Impact on Catamarca: Decreto 563/2025 takes mining export duties to 0% but leaves lithium and silver out of the Annex; according to the official communication they stay at 4.5%. Catamarca has the country's highest mining-to-exports ratio (95.1% between January and August 2026) and its entire producing portfolio is brine lithium — Fénix, Sal de Vida, Tres Quebradas, Hombre Muerto Oeste: it does not capture the cut. Agua Rica/MARA copper does, but it is halted by an environmental permit. The netback that moves expansions did not move here. mixed better export netback thesis
in forceNATIONAL verif Aug 6, 2025 ↗
▸The registry that turns a supplier into a mining beneficiaryResolution 68/2026 of the Mining Secretariat (Official Gazette, 19 Aug 2026), creating the Mining Investment Registryin forceNATIONALAug 19, 2026
Impact on Catamarca: The same effect on suppliers along the salt-flat corridor, where the base of firms is smaller and diversification is the usual way to survive between campaigns. mixed
in forceNATIONAL verif Aug 19, 2026 ↗
▸What you can sell to a mining exploration with VAT that comes backResolution 66/2026 of the Mining Secretariat (Official Gazette, 19 Aug 2026), on s. 14 bis of Law 24,196in forceNATIONALAug 19, 2026
Impact on Catamarca: The same chain in lithium: the provincial exclusive exploration permit unlocks the national recovery, and the general-services list covers what is actually contracted along the access corridor to the salt flats. favorable
in forceNATIONAL verif Aug 19, 2026 ↗
State, institutions and security2
▸Pacto de Mayo: the roadmap signed with the provincesAct of May (declaration, no law no.) + Council of May by Decreto 617/2024pendingNATIONALJul 9, 2024
Impact on Catamarca: The governor is not among those who declined to sign the May Accord, whose seventh point is the exploitation of natural resources; it is the same administration that joined the federal incentive regime by provincial law with an express reservation of jurisdiction. It matters because the Re.P.E.M. requires a supplier to hold two years of local domicile to qualify, and that registry lives in a secretariat resolution, repealable by another. favorable stability → long-term investment thesis
pendingNATIONAL verif Jul 9, 2024 ↗
▸Anti-roadblock protocol: federal forces can clear road blockadesResolución 943/2023 (Ministry of Security)in forceNATIONALDec 14, 2023
Impact on Catamarca: Resolución 943/2023 allows federal forces to clear road blockades on provincial territory and the Court of Appeals upheld it in March 2026. In Catamarca, copper in Andalgalá — the district that grew 8.5% between censuses, the second-lowest variation — carries a history of social conflict. Glencore announced on Oct 2, 2026 the RIGI approval of Agua Rica/MARA, and what still holds back its USD 4,000 M is the environmental permit, filed in September 2026 and under review, and a judicial front, not a blockade. mixed stability → long-term investment thesis
in forceNATIONAL verif Dec 14, 2023 ↗
Labor5
▸Hire formally for 4 years with employer contributions of 2%+3%Decreto 315/2026 (Official Gazette, May 4, 2026), Ley 27.802 Title XXin forceNATIONALMay 4, 2026
Impact on Catamarca: Decreto 315/2026 cuts employer contributions to 2%+3% for 48 months for hires registered between 1 May 2026 and 30 April 2027. In Catamarca hiring locally is not optional: the Re.P.E.M. requires 70% Catamarca payroll in order to sell to the miners, and the registry went from 31 to 229 suppliers in four years with entire categories still empty. The rule makes cheaper exactly what the province requires. favorable cheaper to respond: investing takes time, held-back supply shows up at once thesis
in forceNATIONAL verif May 4, 2026 ↗
▸Labor reform regulated: registration with ARCA, digital pay slip and the end of ultra-activityDecreto 407/2026 (Official Gazette, Jun 1, 2026)in forceNATIONALJun 1, 2026
Impact on Catamarca: Decreto 407/2026 regulates the registry of temporary staffing firms with electronic filing and positive silence, and links construction registration between the tax agency and IERIC. Catamarca has four lithium projects starting inside the same twelve-month window and measurable peak work: a single project laid 3,828,000 m² of geomembrane and Sal de Vida projects ~1,328 ha more of ponds. favorable cheaper to respond: investing takes time, held-back supply shows up at once thesis
in forceNATIONAL verif Jun 1, 2026 ↗
▸Labor: the company agreement beats the industry union dealLaw 27,802, sections 130 to 137 and 149in forceNATIONALMar 6, 2026
Impact on Catamarca: The same mining mechanism, on the smallest supplier base of the five provinces: this is where an agreement of its own can decide whether a local company gets to bid at all. favorable cheaper to respond: investing takes time, held-back supply shows up at once thesis
in forceNATIONAL verif Mar 6, 2026 ↗
▸What a camp wage and roster can be built withLaw 27.802, arts. 31, 33, 34, 35, 41, 42 and 43 (Title I)in forceNATIONALMar 6, 2026
Impact on Catamarca: Puna lithium projects depend entirely on staff who do not live there. Separating the cost of moving a person from the cost of employing them is what decides whether it is worth hiring in Catamarca or bringing people in on a full package. favorable cheaper to respond: investing takes time, held-back supply shows up at once thesis
in forceNATIONAL verif Mar 6, 2026 ↗
▸How much must keep running during a strikeLey 27.802, ss. 101 and 102 (Title VII), rewriting s. 24 of Ley 25.877in forceNATIONALMar 6, 2026
Impact on Catamarca: The same mechanism as San Juan for lithium: it enters through the export-commitment subsection, with a 50% floor. favorable thesis
in forceNATIONAL verif Mar 6, 2026 ↗
What is coming · watchlist · 6 pending signals

Provincial government acts not yet enacted that would move the satellite ecosystem. Each with its official source and unconfirmed seal: it is the political pipeline to follow, not a promise — we do not build an opportunity on what is not law yet.

PENDINGCatamarca announced it will eliminate the turnover tax for industrial activity…2026-09-25 ↗
Our reading — For the small or mid-sized manufacturer that was thinking of setting up in Catamarca to sell to mining, the decision does not change today: the law is still missing. cheaper to respond: investing takes time, held-back supply shows up at once prob
See the full reading and the announcement verbatim
Our reading — If it passes, the cost of setting up falls compared with Salta and San Juan. The step today is to watch the bill in the Legislature.
We received representatives of the Unión Industrial Argentina to discuss the situation of the sector and move forward on a joint work agenda. Also on the need to move ahead with eliminating the turnover tax for industrial activity […]
PENDING132 kV high-voltage line between Tinogasta and Fiambalá…2026-09-23 ↗
Our reading — With the line in service, the Tres Quebradas plant and Fiambalá's services can stop relying on diesel generation: for off-grid generation suppliers it is a demand that shrinks in 2027. a third party pays for the enabling works prob
See the full reading and the announcement verbatim
Our reading — For electrical and assembly contractors, the second stage to Palo Blanco is the project to follow, and the buyer is the transmission company, not the mining company.
In Fiambalá we toured the works on the new 132 kV high-voltage line. A strategic investment made with extra contributions from the company @zijinliex that will be ready in December. It will benefit industrial production and ensure better electricity service for thousands of families in Fiambalá and Tinogasta, adding the town of Palo Blanco in a second stage.
PENDINGCatamarca claims mining generates more than 6,000 direct and indirect jobs…2026-08-27 ↗
Our reading — R8: if the province's mining employment is of that order, the spillover into the local economy is the one we already model for Catamarca. high wages → local non-tradable boom unconf
See the full reading and the announcement verbatim
Our reading — It changes no published figure until the series is available.
Mining already generates more than 6,000 direct and indirect jobs, and the investments open new opportunities for our workers, SMEs and local suppliers. On top of that, we added 200 new private jobs in the last month.
PENDINGwhat the interprovincial agreement still does not fix…2026-05-22 ↗
Our reading — The tax subcommittee and the plant-level measuring devices are themselves a demand for services: fiscal metering and biprovincial auditing of volumes and grades, with two revenue authorities that need a credible third party. federal-provincial tension + the RIGI promise is kept unconf
See the full reading and the announcement verbatim
Our reading — The mirror risk is the ninth clause — a boundary settled by Congress extinguishes the shared regime and with it the rationale for that niche, which is at once its urgency. Vectors to watch, all observable: legislative ratification of per-project royalty agreements in either province (which reveals the real rate), the minutes or resolutions of the management committee, and any bill in Congress on the Salta-Catamarca boundary.
Ley 5.940 (enacted 14 May 2026, provincial Official Gazette 22 May 2026) approves the Facilitation and Development Agreement signed with Salta on 27 March 2025 for the Diablillos project, in the disputed strip of the Salar del Hombre Muerto: an equal split of royalties, provincial taxes and other levies, turnover tax under the Multilateral Agreement, a standing management committee and a tax subcommittee. Salta had approved that agreement and the Sal de Oro one with Leyes 8524 and 8523, passed on 18 December 2025 and published on 9 January 2026; the Sal de Oro agreement creates an interprovincial authority, and the Diablillos one requires certified measurement of the ore entering the plant. The ninth clause voids the agreement once Congress settles the boundary, at which point the winning province becomes sole authority.
See the other 2 signals
PENDINGCatamarca's 2027 tax law: the annual act that shows whether the asymmetry…2025-12-19 ↗
Our reading — A move in code 99000 moves the margin of the province's entire mining-services supply base, on top of the 1.5% stamp tax on the purchase order (art. the RIGI promise is kept + federal-provincial tension unconf
See the full reading and the announcement verbatim
Our reading — 26 subs. 2). Downward, it makes setting up in Catamarca cheaper than operating from another jurisdiction; upward or unchanged, the recurring cost of operating keeps eroding the appeal of establishing locally. Mind the bracket: anyone starting activity from 1 January is taxed at Bracket I for their entire first fiscal year (art. 16 of Ley 5.927), so bracket design matters as much as the rate. Vector to watch: Catamarca's Official Gazette (enactment of the tax law, typically in December) and Annex I of activities and rates on the revenue agency's portal.
Ley Impositiva 5.927 governs fiscal year 2026, and its Annex I sets the turnover tax rates that are today the province's central asymmetry: 0.75% for the extraction of metalliferous minerals and lithium brine (codes 71000/72990/89120) against 3.00% to 4.80% for mining support services (code 99000, by revenue bracket) — 4 to 6.4 times the rate paid by the mine itself. Every province enacts its own annual tax law, so the 2027 one is an act of state with a predictable date.
PENDINGthe pending decision on Catamarca's largest stalled capital…2025-08-18 ↗
Our reading — An environmental permit granted changes the composition of the province's satellite ecosystem, not just its size: copper at this scale demands rings that evaporitic lithium does not (heavy fleet maintenance, off-the-road tires, hydraulics, component workshops, grinding) and sustains years of construction before it produces. lowers country risk + the RIGI promise is kept unconf
See the full reading and the announcement verbatim
Our reading — It is also the toughest test of the thesis: if the capital stays stalled with the RIGI granted federally, the bottleneck is provincial and observable. Vector to watch: the filing of the Environmental Impact Report for exploitation and its resolution at Catamarca's Mining Secretariat, the status of the judicial front, and MARA's appearance on the official list of approved RIGI projects.
Glencore filed Agua Rica-MARA under the RIGI on 18 August 2025, in the same application as El Pachon (San Juan), for USD 4,000 M. As of 25 July 2026 it does not appear among the approved projects on the official RIGI portal. The stated bottleneck is neither fiscal nor geological: it is the environmental permit for exploitation, which has not been filed, plus an open judicial front.

Our reading · Catamarca

2 theses · how the pieces converge
When several pieces of the data —reforms, RIGI, opportunities— push in the same direction, we read them as a single story. It is our reading (thesis seal), not a data point: the status of each one is derived from how many of its pieces are already in force.
Competitive federalism: with no discretionary federal purse and no tax possible on RIGI projects, governors compete for business location — provincial risk turns around and works in your favor4/4 solid pieces · ready to executethesis lowers country risk + federal-provincial tension + the RIGI promise is kept
The classic risk 'the province captures your rent' (R7 · federal-provincial tension) mutates into a structural tailwind: Río Negro adhered to RIMI unanimously with a single-window process (Ley 5857) and 6 RIGI mining projects landed across 5 provinces that competed to host them.
Open the thesis and its evidence — the reasoning, the pieces, the laws and what we watch
For the investor, provincial adhesion legislation (RIGI/RIMI + single-window + stacked exemptions) becomes a leading indicator of where the next capital lands.
The case that debuts the pattern: Río Negro adheres to RIMI unanimously with a single window (Ley 5857)…The lock that closes the capture route: RIGI's secThe mining wave as evidence of competition to host: 6 RIGI copper and lithium projects landed across 5 provinces…Salta shows the other half of the competition for investment — the half that does not appear in the capital ranking…
Río Negro adheres to the RIMI: national benefit + provincial promotion in a single filing in forceThe case that debuts the pattern: Río Negro adheres to RIMI unanimously with a single window (Ley 5857) — a non-aligned province lowering the cost of entry instead of capturing rent.
Ley Bases: the RIGI is born in forceThe lock that closes the capture route: RIGI's sec. 165 shields adhered projects from new provincial taxes (Río Negro's attempt to tax exports was struck down through it in 2025).
Los Azules — copper cathodes (McEwen Copper) approvedThe mining wave as evidence of competition to host: 6 RIGI copper and lithium projects landed across 5 provinces — Los Azules (San Juan, USD 2,672 M) is the first verified in the Official Gazette.
Fiscal anchor reinforcementThe surplus whose arithmetic flip side is the drought of discretionary transfers: without a sustained chainsaw there is no change of incentives.
Investment (RIGI) reinforcementThe board where the result is read: the project pipeline is no longer energy-only — a portfolio diversified by sector and province is the competition at work.
Salta: 70/60 local mining procurement in forceSalta shows the other half of the competition for investment — the half that does not appear in the capital ranking: it joined the RIGI through Ley 8451 in August 2024 while keeping its own Ley 8164 on local procurement and mining employment. This is the move available to a governor who can no longer capture rent and does not want to give it away either: instead of taxing a project shielded by article 165, it sets local-purchase conditions downstream. With three approved mining projects worth USD 4,055 M — plus Pozuelos-Pastos Grandes, over USD 3,000 M, filed in the first quarter of 2026 and still awaiting a ruling from the Committee — Salta runs in the pack rather than at the front: San Juan holds more than triple its approved mining capital (USD 13,328 M across four projects). That is exactly why it is the case that shows the remaining tool is local procurement, not taxation.
Trigger: Two simultaneous closures change the board for the 24 governors: the discretionary federal purse shut down as the arithmetic flip side of the fiscal surplus (non-automatic transfers in June, the lowest for that month since 2005) and RIGI's art. 165 shields adhered projects from new provincial taxes (Río Negro's attempt to tax exports was already struck down in 2025).
Mechanism: R1 + R7 inverted + R2. With no transfer to ask for and no new rent to capture, the margin left for a province to sustain its economy is attracting investment to its territory: competition among jurisdictions shifts from the war over rent to the war over location — lowering the cost of entry instead of raising it. lowers country risk + federal-provincial tension + the RIGI promise is kept
The chain, link by link
  1. 1The provinces' historical channel of political financing —the discretionary federal transfer— closed structurally as the flip side of the surplus (non-automatic transfers to provinces fell 87.7% in real terms in June, the lowest June since 2005). The governor loses the instrument with which he sustained his economy without depending on private investment in his territory.consistent
    Mechanism: R1 (the surplus IS the cut in discretionary spending; the withdrawal of transfers is its arithmetic flip side, not an accident) — same link as the federal-funding substitution thesis, read here from the side of the governor's INCENTIVES, not of works financing.
  2. 2With the second channel also barred —RIGI's art. 165 shields the SPV against new provincial taxes; Río Negro's Feb-2025 'export royalty' attempt was struck down that way—, the governor's only margin is to compete for investment by lowering the cost of entry. The July-15 batch shows it operating simultaneously and across jurisdictions: Río Negro adhered to RIMI by UNANIMITY with a single-window procedure and its own stacked exemptions (Ley 5857), and 6 mining RIGI projects landed across 5 provinces (San Juan, Mendoza, Salta, Jujuy, Catamarca) that competed to host them instead of taxing them.proven
    Mechanism: R7 inverted (the tension over rent mutates into inter-provincial competition for investment: same actor, incentive flipped) + R2 (each provincial adhesion completes the federal regime's legal-certainty promise in its territory).
  3. 3Operational corollary: as long as the federal fiscal regime holds, the watch condition «governors' tension over rent» has a structural bias in its favor (not isolated cases but an equilibrium of incentives), and provincial adhesion legislation becomes a LEADING INDICATOR of where the next capital lands — a new observable to order the federal map and choose our next province.pending
    Mechanism: Synthesis R1 → R7 inverted → R2: no single rule describes the incentive-regime change or its methodological consequence (reading provincial adhesions as a predictor).
What this reading takes for granted these are not sourced facts: this is the part of the reasoning you can argue with
  • That the governor decides at the margin: with no federal cash to ask for and no new rent to tax, he would rather compete for investment than raise the pressure on what he already has inside. This is an assumption about political behaviour, not a datum.
  • That the shutdown of discretionary federal cash holds. It is the arithmetic counterpart of the surplus: if the surplus gives way, the transfer comes back and the incentive to compete undoes itself.
  • That art. 165 of the RIGI holds against whatever a province tries. Today it has one precedent —Río Negro's attempt to tax exports, struck down in 2025— not a body of case law.
What we watch (observable data + external vector):
  • A province with RIGI or RIMI projects under way raising royalties, gross-receipts tax or mandatory carry on the sector in its annual tax law. Vector: 2027 provincial tax laws in the Official Gazettes, observable — the exact signal of the governors-rent watch condition.
  • Governors, via Congress, forcing over the veto the reopening of discretionary transfers or an automatic ATN revenue-sharing law: it would reopen the old channel and dismantle the incentive to compete. Vector: parliamentary proceedings, observable.
  • Provincial legislature turnover in 2027 repealing or conditioning current RIGI/RIMI adhesions. Vector: provincial Official Gazettes, observable.
Predictions we commit to
  • pending At least one more province adheres to RIMI (or enacts an equivalent single-window RIGI/RIMI adhesion process) before Mar-2027. how we check: Provincial Official Gazettes + the legislation monitoring register; re-checked periodically.
  • pending No province with RIGI projects under way raises royalties, gross-receipts tax or mandatory carry on the sector in its 2027 tax law. how we check: Provincial 2027 tax laws (passed Nov-Dec 2026) in the provincial Official Gazettes; this is the exact vector of the watch condition «governors' tension over rent».
When the works are bigger than the place, what sells is service to the works, and it is sold from the provincial capital2/3 solid pieces · under waythesis each phase buys something different + high wages → local non-tradable boom
For a company that wants to sell: in the Andes and the Puna, the contract within its reach is not the works but service to the works (camp, food, staff transport, road maintenance, training), and it is won from the provincial capital.
Open the thesis and its evidence — the reasoning, the pieces, the laws and what we watch
For people who live in the department: the way in is the trade the works cannot find locally, not local retail, which does not receive the wage spending while people live in camp. In large cities it is the other way round: the local SME competes for the works themselves.
The strongest case: 2.1 times the registered jobs of Iglesia estim2.0 times the registered jobs of Los Andes (Salta), with 4,200 workers at the construction peak [validated]The intermediate case: the works are 38% of Andalgalá's jobs but 2.5 times its miners and construction workersThe market where the thesis turns into a sale in San JuanHigh-altitude catering: the spending the thesis says is contracted from the capitalStaff transport: a direct consequence of people not living in the departmentThe same market in the Salta Puna, where Rincón, Sal de Oro, Pozuelos and Diablillos share a departmentThe same market in Catamarca (Andalgalá, Tinogasta, Antofagasta de la Sierra)
Vicuña (Josemaría + Filo del Sol) — copper, gold and silver approvedThe strongest case: 2.1 times the registered jobs of Iglesia estim. The awarded stage of the new camp, about 25%, is being carried out by a consortium in which PowerChina holds the contract, Beijing Chengdong makes the modules in China and RAFA, from Santa Fe, does the civil works prob. The other known contractors are from San Juan city prob: none declared with an address in Iglesia.
Rincón Project — lithium carbonate (Rio Tinto) approved2.0 times the registered jobs of Los Andes (Salta), with 4,200 workers at the construction peak [validated].
Sal de Oro II — lithium carbonate (POSCO) approvedreinforcementThe same department as Rincón. Its known contractors are from Rosario and from the province of Salta prob, and 54 % of its 3,600 construction workers came from the province of Salta, not from the department.
Agua Rica / MARA — copper, gold, silver and molybdenum (Glencore) submittedThe intermediate case: the works are 38% of Andalgalá's jobs but 2.5 times its miners and construction workers. It shows where the thesis starts to hold.
Mining camps and modular housing (San Juan) The market where the thesis turns into a sale in San Juan.
Catering and remote high-altitude site hospitality (San Juan) High-altitude catering: the spending the thesis says is contracted from the capital.
Mining personnel transport and people-to-mine logistics (San Juan) Staff transport: a direct consequence of people not living in the department.
Camps, catering and the community joint venture of the Salta puna The same market in the Salta Puna, where Rincón, Sal de Oro, Pozuelos and Diablillos share a department.
Camps, catering and high-altitude living services in the Catamarca puna The same market in Catamarca (Andalgalá, Tinogasta, Antofagasta de la Sierra).
Trigger: Three mining projects need more people on site than all the registered jobs of the department where they are built: Vicuña, with an average of 5,500 direct jobs, against 2,597 jobs held by residents of Iglesia (2.1 times, and 9.8 times its 560 miners and construction workers); Rincón, with 4,200 workers at peak, against 2,071 jobs in Los Andes (2.0 times); and Sal de Oro, with 3,600, in the same department. Iglesia had 4 lodging businesses with employees in 2022 and Los Andes had 2. In Bahía Blanca, San Nicolás or San Lorenzo, the works of Fértil Pampa, Sidersa or Timbúes are between 1% and 5% of local employment.
Mechanism: R13 × R8. A project's first phase buys the camp, roads, heavy logistics and transport of people (R13 · each phase buys something different). When the place lacks the people and the firms for that, the works bring their workforce from outside and house it in a camp: the high wage that R8 turns into local spending is spent where the worker lives, which is the provincial capital or another province, not the department of the works. The private response (R9 · without controls, supply responds to the boom) does appear, but it comes from firms with the scale to set up and run a high-altitude camp, and those are in the capital. each phase buys something different + high wages → local non-tradable boom
What this reading takes for granted these are not sourced facts: this is the part of the reasoning you can argue with
  • That the registered jobs of department residents in November 2023 describe today's local labour supply well. The official series was not updated after that, so it is the starting-point snapshot.
  • That the construction employment figure each company publishes is close to the real peak. In Vicuña it is an average over the 40 months of construction its technical study foresees, so the peak is higher.
What we watch (observable data + external vector):
  • That the supplier roll of Vicuña, Rincón or Sal de Oro shows that most camp, food or transport contracts are held by firms registered in the department of the works. Vector: each project's local-purchasing reports and provincial registers of mining suppliers.
  • That, if the State publishes the jobs-by-department series again, the construction jobs of people living in Iglesia or Los Andes grow by a magnitude comparable to the works (thousands, not tens). Vector: CEP-XXI jobs-by-department series.
Predictions we commit to
  • pending From now to 31-Dec-2027, among the camp, food and staff-transport contracts of Vicuña, Rincón and Sal de Oro that become public, most are won by firms registered in the provincial capital or outside the province, not in Iglesia or Los Andes. how we check: The awards and contractors published for Vicuña (San Juan), Rincón and Sal de Oro (Salta), with each firm's registered address. Only those with a declared address are counted.
First step · free
The first read of your company

We look at what your company does and tell you whether we see a sign that it fits this market, with the evidence behind it. If we do not see one, we say so too and name the condition that would change it. One page as a dated PDF, within 48 working hours.
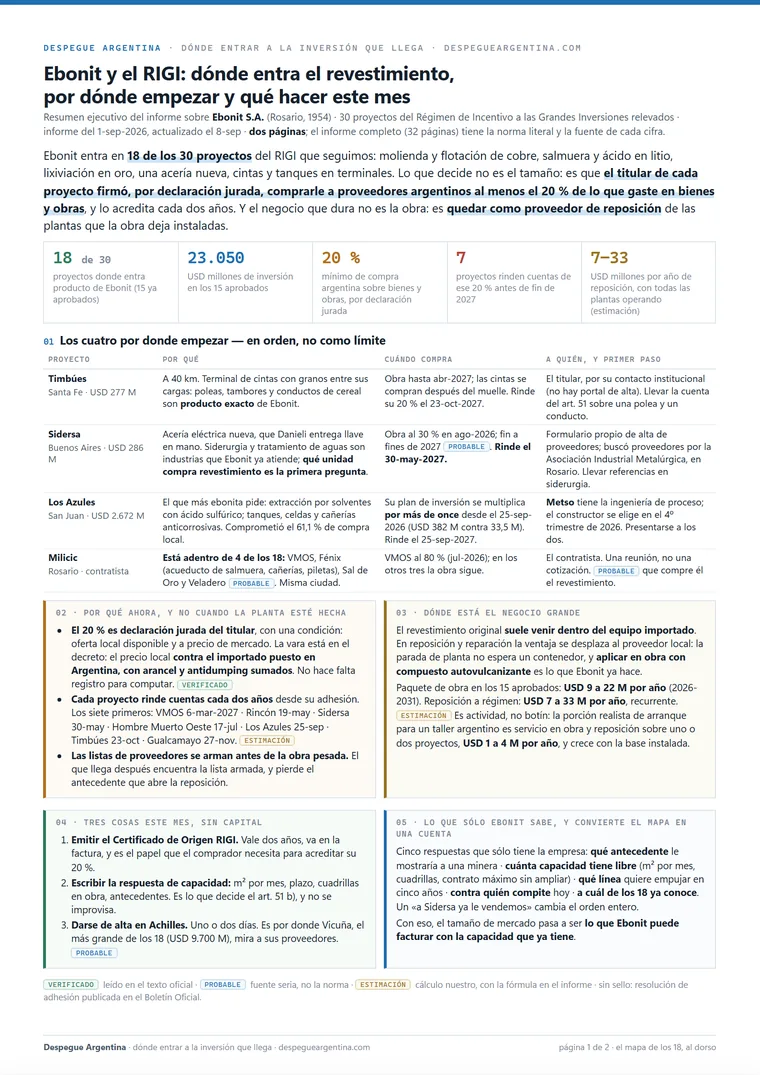
Not here for a company? Invest · Work (in Spanish) · Start a business (in Spanish) · Institutions
Page 1 of the example executive summaryOpen the report ↗A real analysis · a real company, open in full →
Ignacio Aredez
Analysis and curation: Ignacio Aredez
Head of Despegue
Method and track record →
  • 20+ years in technology, 15 of them in data and AI, for clients across Europe and the Americas
  • Certified in AI governance (ISO/IEC 42001)
  • Machine Learning (Google Cloud)
  • Registered expert with the European Commission
How to read the seals →
  verif primary source · prob primary source pending · unconf a source said it · estim our own calculation · thesis our reading · the date belongs to the datum, at the precision its source allows
This is not financial advice. Each data point carries its confidence level and its source; projections are labeled as thesis. Looking for the impact on jobs and SMEs? See the version for working and starting a business.