Despegue ← Catamarca OPPORTUNITY
11 more opportunitiesOther opportunities ▾
ESEN Where my company can get in
Catamarca · Salar del Hombre Muerto · fiscal metering, traceability and royalty auditing
The province already ordered every well to be instrumented, with an expired deadline — and the technical standard is not writtenthesis

Fiscal metering, traceability and royalty auditing at the Salar del Hombre Muerto (Catamarca)

Estimated entry range for a supplier
USD 40,000-150,000 per client per year
in 2-3 years
Estimated market: USD 0.8-3.0 M/year
awaiting new data · reviewed Jul 25, 2026
estim Jul 25, 2026midpoint ~USD 1.8 M/yearurgent demandour reading
At a glance
Who buys
The operator extracting from the strip, directly
the 3 doors →
In which projects
Diablillos, Fénix, Hombre Muerto Oeste and 2 more
what each one invests →
When
The deadline has already expired: since 29 September 2023 every plant in Catamarca must meter each well, and the province gave sixty days. The inter-provincial part has no date: it is settled when the salt flat's plant starts up and the authority is constituted. verif Sep 29, 2023 ↗
what to watch and where it stands →
The main barrier
It is not a capability that is missing: what is missing is the combination. Whoever measures must be credible to two tax authorities, be accredited with traceability and work above 4,000 metres. All three exist; together and based in the province, in no company. thesis
the whole entry map →
Where you get in
Do not start by fighting for the instrument against the contractor that already bought it, or for the auditing against two tax agencies that can do it with their own staff. The place of the independent third party is open:
the 3 routes →

The boundary between Salta and Catamarca at the Salar del Hombre Muerto has been undefined since 1943, and in 2021 the governors solved the problem in the simplest possible way: splitting 50 and 50 the royalties, the provincial taxes and every other levy on whatever is extracted from the disputed strip. Salta approved both agreements by law in January 2026 and Catamarca the Diablillos one in May, and the agreements themselves create bodies: an interprovincial authority of three representatives per province for Sal de Oro and a management committee with a tax subcommittee for Diablillos, with tax officials from both sides seated at the same table. Only one thing is missing, and it is the one that decides everything: the number. Catamarca's royalty law orders collection on the physical volume extracted at the mine mouth and gives the State the power to verify it — but there is no method agreed between the two provinces, no specialized provider in either of them, and the mass the two provinces split each year —royalties, Turnover tax and stamp tax on both sides— is of the same order as all of Catamarca's mining collections.

An event-driven regulatory window: the system is defined when CP2 starts up and the interprovincial authority is constituted; whoever installs the first fiscal point sets the method that gets replicated. And the agreement carries its own switch: it can turn the biprovincial core off overnight.

verif primary sourceestim our own calculationthesis our readingHow to read all five →

What the market is made of

The TAM is activity, not what you will invoice. Here the captive share takes a form seen in no other niche: it is captured by the State itself. The tax subcommittee is made up of the heads of the two provincial tax authorities, and the metering instrument the agreements require will most likely be bought by the contractor inside the plant's capex. Your real gap is what neither of them can do: being the independent third party that measures, seals and certifies a number both provinces accept — plus all the royalty settlement work of the province's other four operations, which does not depend on this agreement.

How it splits, and against which total
Midpoint of the captive/addressable split (~55-65% captive, per the funnel) over the central TAM of ~USD 1.8 M/year. Our own estimate. estim
CaptiveUSD 1 M · 56%
Addressable (SAM)USD 0.8 M · 44%
CaptiveUSD 1 M56%non-addressable
the instrumentation the contractor will most likely put inside the plant's capex + the enforcement the two tax agencies carry out with their own staff (zero market price) + the royalty advisory resolved at head office or at a Buenos Aires Big-4 + the umpire work and assaying the international laboratory captures from Mendoza or Jujuy, where it already holds accreditation
Addressable (SAM)USD 0.8 M44%addressable
royalty auditing and valuation of the mine-mouth base (the arbiter can be neither the audited party nor the tax authority that later issues the assessment) + the biprovincial settlement software — we did not identify a product covering two jurisdictions over the same extraction, and that is a search that cannot be closed from here + traceable calibration and verification, which demands recurring physical presence + fiscal-point engineering and its sealing + all the royalty settlement work of the other four operations, which survives if the agreement falls
Non-addressable

~USD 1.0 M/year (~55-65% of the TAM) estim: (a) the instrumentation the operator is required to install —flow meters at each well at Sal de Oro and certified measurement of the ore entering the plant at Diablillos— verif, which will most likely be bought and integrated by the plant contractor inside the control capex, not by a third party thesis.

See the full breakdown
(b) the enforcement the two tax agencies do with their own staff, at zero market price: the tax subcommittee is made up of the heads of the tax authorities themselves, Ingresos Públicos y Rentas for Salta, Agencia de Recaudación y Rentas for Catamarca verif; (c) the royalty advisory resolved at head office or at a Buenos Aires Big-4; (d) the umpire work and assaying that the international laboratory captures from Mendoza or Palpalá, where it already has an accredited OAA scope. NOTE: HMW's 95.34% and Fénix 1B's 60% do NOT automatically enlarge this SAM — they are the share of what each project pays suppliers that it declares goes to local suppliers, and in the national RIGI 'local supplier' means ARGENTINE, not from Catamarca (art. 176 subs. l Ley 27.742 + art. 49 Decreto 749/2024, a 20% minimum) verif; besides, neither project is inside the biprovincial perimeter.
Addressable share

~USD 0.35-1.4 M/year addressable by a local/domestic entrant (midpoint ~USD 0.8 M/year):(1) the entire auditing, valuation and technical assistance component, because the arbiter can be neither the audited party nor the public auditor who later issues the ex officio assessment;(2) the biprovincial settlement software, where there is no specific local or international offering;(3) traceable calibration and verification, which demands recurring physical presence and today has no provider in the province;(4) the low half of implementation (fiscal-point engineering, sealing and file, separable from the supply of the instrument);(5) ALL of the adjacent layer (royalty returns for the other four operations, pond inventory certification, 3% vs 5% classification), which does not depend on the interprovincial agreement and therefore survives its extinction.

Entry range for a supplier

USD 0.15-0.45 M/year recurring for ONE entrant within 2-3 years (midpoint ~USD 0.3 M/year), plus the implementation peak, which is contingent and counted separately.

See how the range is built
Year 1: 2-3 reconciliation and valuation clients + the draft technical protocol → USD 0.15-0.35 M. Year 2: annual calibration program at 2-3 sites + pond inventory certification → +USD 0.1-0.25 M. Year 3: the implementation of ONE complete fiscal point (USD 0.35-1.10 M one-off) or the settlement system → the peak year. Honest ceiling: with 12-20 qualified jobs at stake, this niche does NOT sustain a stand-alone company — it is a high-margin module bolted onto an existing practice (a tax firm, a laboratory, an instrumentation integrator) or the anchor of a 4-8 person technical consultancy.
▸ An event-driven window, not a yearly one: the system is defined when the salar's carbonate plant starts up and the interprovincial authority is constituted. And there is a clause that switches it off: once Congress settles the boundary, the agreement becomes void.

Who really pays?

The obvious name —«the tax authority»— is the one that pays latest and worst. In fiscal metering the money flows through three different channels:

If you sellMonthly volume reconciliation, base valuation and defense of the sworn return
→
The operator extracting from the strip, directly verif in force since 1993 ↗

Whoever produces in the disputed strip needs a single number that Salta and Catamarca both accept thesis. Catamarca's royalty law puts the risk on them: the base is the physical volume extracted at the mine mouth, settlement is by monthly sworn statement and the fine for not filing it can reach 100% of the royalty verif; on the Salta side the statement is quarterly verif. We found nobody who certifies that number independently today unconf.

If you sellThe installed fiscal metering system (redundant flow metering, type-approved weighbridge, automatic sampling, sealed record) — the big project
→
The plant's EPC, by subcontract — NOT the State prob Jan 9, 2026 ↗

Both agreements require the operator to meter: flow meters at every extraction well as a condition of the environmental impact statement at Sal de Oro, and certified metering of the ore entering the plant at Diablillos, with the devices each province requests verif. The instrument will most likely come in with the works and be integrated by the plant contractor inside the control capex thesis: an entrant wanting that slice sells to the EPC, and its differentiator is not the hardware (imported) but the fiscal-point engineering, the traceable sealing and a file admissible before two jurisdictions thesis.

If you sellUmpire work, certification of the split and technical assistance to the subcommittee — the contract that confers authority
→
The two tax agencies (ARCAT and Salta's), via the interprovincial tax subcommittee prob Jan 9, 2026 ↗

The tax subcommittee of each agreement is made up of two representatives per province, and they are the heads of the tax authorities themselves: Ingresos Públicos y Rentas for Salta, Agencia de Recaudación y Rentas for Catamarca; it can recommend joint regulations to facilitate enforcement verif. That is why it can be done in-house at zero market cost, and it is the door with the most prestige and the least urgency thesis. It opens when the provinces issue those joint regulations.

▸
The lesson: the hardware is paid for by the works, the number is paid for by the operator and the seal is paid for —if it is paid for at all— by the State.

Which projects move this demand

Second stage of POSCO's Sal de Oro lithium complex in the Salar del Hombre Muerto, on the disputed Salta/Catamarca border strip…

see the project →

Gold and silver mining in the puna, on the Salta/Catamarca border area: feasibility development, a 3.15 Mt/yr processing plant and full infrastructure…

see the project →
USD 251 M Apr 6, 2026 ↗

Expansion (Phase 1B) of the historic Fénix lithium-carbonate project in the Salar del Hombre Muerto, operated by Rio Tinto via Minera del Altiplano…

see the project →

Lithium brine project in the Salar del Hombre Muerto (western zone), to produce 12,000 t/yr of lithium carbonate equivalent…

see the project →

Tres Quebradas stage 2: plant and infrastructure for 40,000 t/year of lithium carbonate via direct extraction (DLE), per art…

see the project →

When the window opens

Here the warning is not a price or an investment decision: it is an administrative act, which can open the market or close it for good. These four numbers are the ones that give notice.

What to watchWhat changes when it happensStatus
The implementing rule for the mandatory per-well instrumentation
It is the most direct trigger on this page. The day the three provincial directorates say which equipment and which procedures, there is a tender. Until then there is an obligation with no specification, which is exactly the space you can occupy by writing it.
the obligation has applied since 29 September 2023 and its 60-day deadline expired; the power to issue the implementing rule is in article 4 of the same resolution.
See the evidence
⚠️ That rule does not appear in the official mining legislation index — which is what the Ministry chooses to publish there, not the provincial official gazette, so it cannot be stated that it was never issued
verif Sep 29, 2023 ↗
The constitution of the inter-provincial authority and the management committee
It is the event that creates the arbiter role between the two provinces.
Salta approved both agreements by law —Sal de Oro (Ley 8523) and Diablillos (Ley 8524)—, passed in December 2025 and published on Jan 9, 2026 with the full text as an annex.
See the evidence
Catamarca approved the Diablillos one through Ley 5940, published on May 22, 2026, without transcribing the annex. The Sal de Oro one provides for an interprovincial authority of three representatives per province; the Diablillos one, a management committee of three per province, with subcommittees for procedures, environmental impact and control, and a tax subcommittee of two per province.
verif May 2026 ↗
The annual rent the two provinces share
It is the ceiling of this market: nobody spends more on measuring than what is being shared. And it moves with the lithium price, which is the only truly live input in the model.
USD 8-24 million a year under the fifty-fifty split, midpoint 15; the Catamarca half, USD 4-12 million.
See the evidence
For comparison, all of Catamarca's mining royalty revenue runs at USD 15-17 million a year
estim 2026
The fines on the royalties sworn statement
It measures what getting it wrong costs, and therefore what not getting it wrong is worth. It is this page's willingness-to-pay figure.
for failure to file, incomplete filing or late filing, and with no prior demand required, a fine graduated between 10% and 30% of what should have been paid, with an ex officio assessment.
See the evidence
for falsehood in the sworn statement, two to five times the royalty, without exempting civil, administrative or criminal actions. The law allows up to 100% and the implementing decree limited itself to that scale
verif Jul 8, 2014 ↗
What signals the game has changed
The ninth clause of the Salta-Catamarca agreement

Quoted text: 'Once the boundary dispute is resolved by an Act of the National Congress, this agreement shall become void...', and the winning province becomes the sole authority prob.

See the evidence
Binary timing, at any moment: it is an act of Congress, not a gradual process (82 years without resolution since the National Territory of Los Andes was dissolved in 1943 suggest a low near-term probability). It erases the entire biprovincial core (USD 0.5-2.0 M/year): with no two jurisdictions, no arbiter is needed. It does NOT erase the adjacent layer, because the monthly sworn return under art. 7 of Ley 4757 remains alive. It is both the killer and the reason for urgency.
The two tax agencies doing it in-house

The most likely and most immediate killer. The interprovincial tax subcommittee is made up of tax officials from both provinces (three converging sources, Jan 10/12/14, 2026) and art.

See the evidence
14 of Ley 4757 already gives them the power to verify the physical volume: a purchase line may never be created. It erases 60-80% of the auditing and all of the software on the State side. Structural mitigation: sell to the operator, which needs a number both provinces accept.
The metering never being instrumented (the premise is not proven)

The main analytical risk in this niche. 'Metering devices at the plant' did not appear in any of the four press sources opened (El Tribuno, Minería y Desarrollo, Poder Local, Club Minero), but the annex to the Diablillos agreement is published in Salta's Official Gazette and provides for certified metering of the material entering the plant, with technical metering devices that each province may request.

See the evidence
the Sal de Oro one requires flow meters at every well verif annex to Salta's Ley 8524. Catamarca approved the Diablillos one through Ley 5940 without transcribing the annex. What remains open is who audits those measurements: if reconciliation ends up being documentary between two tax offices, implementation, calibration and umpire work disappear (45-55% of the core) and only advisory remains thesis. Structural, already present.
Lithium carbonate price

The TAM is a percentage of the fiscal mass: it is LINEAR with price. Q2-2026 spot averaged USD 22,043/t (+13% quarter on quarter) but closed the quarter at USD 19,400/t, and Rio Tinto's realized price in H1-2026 was USD 18,960/t verif.

See the evidence
A 30% fall in price cuts ~30% of the niche without any other variable changing. Continuous exposure.
See the remaining 4 risks
Delay or cancellation of stages: half the perimeter is an announcement

Sal de Oro's Plant II was inaugurated on Oct 6, 2026, with a gradual start-up during 2027 verif Presidencia de la Nación.

See the evidence
the Diablillos plant is not built: its RIGI resolution provides for construction from July 2026 and operation from July 2029 verif Resolución 562/2026; Tres Quebradas 2nd stage has a published RIGI resolution —Jul 29, 2026, with USD 594,136,000 of computable investment verif Resolución 1153/2026— and so does Sal de Oro II: Resolución 1157/2026, published on Jul 31, 2026, with USD 207,936,427 of computable investment verif Resolución 1157/2026. If Diablillos slips to 2029-2030, the core stays in today's band (USD 0.3-1.1 M/year) for three more years. Timing 12-36 months.
Capture by Salta or by the operator's chain

Salta publishes Sal de Oro as a Salta project and mentions neither Catamarca nor the royalty split verif Government of Salta, Feb 18, 2026.

See the evidence
the hydroxide plant is in the General Güemes industrial park prob; the nearest official laboratory accreditation for lithium in brines is in Palpalá, Jujuy verif official accreditation registry; and of the drilling firms named in Sal de Vida's technical report, the most significant are based in Salta and Mendoza, and the only Catamarca one, Hidroper, drilled a single well prob. The supplier will be from Salta or Mendoza unless a registered Catamarca vehicle exists. It is the only killer an entrant CAN neutralize, and only by moving now (2026-2027, at contracting time).
Social license and litigation

The Catamarca Court of Justice lifted 5-2 the injunction over the Río Los Patos sub-basin with continuous monitoring conditions, on a 2021 amparo action by Román Guitián (Atacameños del Altiplano community) with a filing pending before the iachr prob.

See the evidence
If production stops, the fiscal mass stops. Stated double edge: the same ruling creates demand for continuous measurement and reporting. Continuous exposure.
End of the implementation window vs. the perpetual operating core

Implementation (35-40% of the TAM) is ONE-OFF and concentrated in 2026-2030. The perpetual core —annual calibration, monthly volume reconciliation, base auditing, pond inventory certification— is USD 0.6-2.0 M/year and does not end while the plants operate (mine lives of 25 to 40 years).

See the evidence
An entrant should charge for the peak and keep the retainer; whoever sizes the organization for the peak goes bust in 2031.

The opportunity in depth

How to get inthe gap and the routes that open it
1

Here is a fact that changes the conversation: the province has already ordered instrumentation. Since September 2023, every company with a pilot or producing plant must install flow meters, piezometers and multiparameter meters at each producing well, with cameras and sensors, to audit production, commercialisation and industrialisation, in real time where possible. The deadline was sixty days and it expired. The same resolution empowered three provincial directorates to say which equipment, with which methods and with which procedures — and that implementing rule does not appear in the official mining legislation index.

2

Whoever extracts from the strip needs a single number that both provinces accept and today has nobody to certify it: monthly reconciliation of the physical volume, defensible valuation of the base, an auditable file in two jurisdictions and a defence against an ex officio assessment —when the tax authority calculates the tax itself because your filing does not add up— where the fine runs from 10% to 30% of what should have been paid, and two to five times the royalty if falsehood in the sworn statement is proven. Ticket USD 40,000-150,000 per client per year, with no equipment.

3

Integrate the metrological leg via a joint venture — the provincial regime admits it with at least 50% local partners and the precedent is proven in a USD 130 M EPC with a Catamarca firm inside. There you bid the complete package and set up a calibration laboratory in Catamarca serving the whole industry of the province, not just mining: it is the only thing in this niche that remains when the lithium price falls.

What you needcapital, certification, tax regime and who pays
The service is paid against monthly delivery and against milestones, with no dead gap. What you need in order to enter:
Capital
From USD 50,000-200,000 to enter via advisory and reconciliation (it is an hours business) to USD 0.4-1.5 M to integrate metrology and an accredited calibration laboratory. Implementing a complete fiscal point is quoted at USD 0.35-1.10 M per plant.
Capability
Three competencies that today do not live together: traceable metrology (standards, uncertainty, an ISO/IEC 17025 scope, accredited with the address of each laboratory and taking 12-24 months, and today there is no accredited entity domiciled in Catamarca, of any kind, out of the 341 in the national registry), mining tax expertise (valuation of the mine-mouth base and its closed list of deductions) and operating at altitude (above 4,000 masl, -30 °C, winds of up to 120 km/h, 215 of 390 km unpaved).
Regime
Registration with the Re.P.E.M.: domicile in Catamarca for 2 years, 50% local partners —or a joint venture at least 50% local, the realistic route— and 70% of the professional payroll from Catamarca, which is precisely what is scarce. Plus the cost of being a supplier: Turnover tax of 3.0% to 4.8% against 0.75% for extraction, and 1.5% stamp tax on the purchase order.
Who pays
It is neither «the mine» nor «the province»: they are three different doors and the fastest is not the State's.
▸ You tell us where to see what your company does and we tell you whether we see a sign that it fits this opportunity, with the evidence behind it. See if my company fits this opportunity →
When you get paid, and what blocks it
It is partially paid today, and one has to be precise: the instrumentation is already paid for (most likely inside the plant contractor's capex) and so is the preparation of the sworn return (inside the operator's administration); what has NO purchase line yet is the independent service. Its first invoice depends on an identifiable event: (i) the first fiscal settlement of the strip under the 50/50, now that CP2 was inaugurated on Oct 6, 2026; (ii) the formal constitution of the interprovincial authority and of the tax subcommittee with its bylaws —the event that defines the tender specification—; (iii) construction start at the Diablillos plant. The real bottleneck, in order:(1) Independence and admissibility, the bottleneck money cannot buy — nobody has written the rule saying whether the same provider may measure for the operator and certify for the provinces; without that rule every contract is objectionable by the counterparty;(2) Re.P.E.M.: legal domicile in Catamarca with 2 years of seniority, 50% local partners (or a joint venture at least 50% local), municipal and Rentas licensing, 70% of the professional/technical/administrative payroll from Catamarca with 2 years of residence and a semi-annual sworn statement prob; it bites precisely here, because a metrologist or a mining tax specialist with two years of Catamarca residence barely exists in a province of 429,562 inhabitants whose salar department has 2,022 — the realistic route is the joint venture, not your own registration;(3) homologation in the operator's supplier registry (Rio Tinto publishes KPIs: +50 suppliers trained, 800 hours of assistance, 290 improvement actions, +60% in requests for quotation, 90% acceptance verif; POSCO and AbraSilver run their own);(4) traceability and accreditation: the chain must end in national standards and, for assaying, in an accredited ISO/IEC 17025 scope, which carries the laboratory's address verif and takes 12-24 months (that it is not lent between sites is our reading thesis);(5) the tax cost of being a supplier: Turnover tax 3.0%/3.9%/4.8% for mining support services (code 99000) against 0.75% for extraction, plus 2% stamp tax on acts tied to mining rights and 1.5% on mining suppliers' purchase orders — whoever starts activity from Jan 1, 2026 pays Bracket I (3.0%) for their entire first fiscal year (art. 16), with the bracket jump only above ARS 3,255,000,000 verif; on a USD 1 M contract that is ~USD 15,000 of stamp tax nobody puts in the model;(6) capital and altitude: USD 50,000-200,000 via the advisory route, USD 0.4-1.5 M to integrate metrology and a calibration laboratory, with campaigns above 4,000 masl, -30 °C to 26 °C, winds of 20 to 120 km/h and 215 of the 390 km of access unpaved.
Who you compete againstwho is already there and what share they take
Who is
already in
Market
split
The operator itself (POSCO Argentina, Pacific Rim/AbraSilver; and Rio Tinto/MdA, Galan, LIEX in the adjacent layer)~55-65% of the function estim

It installs and operates the instruments, builds the mass balance and signs the monthly sworn return. It is the AUDITED party: structurally inadmissible as arbiter. Its instrumentation is not 'fiscal metering' until someone independent seals it. It is a client, not a competitor.

ARCAT + Salta's tax agency (via the interprovincial tax subcommittee)~10-15% of the function and 0% of the paid market prob

The most dangerous competitor is the public budget: the subcommittee is made up of the two provincial tax authorities (three converging sources), and art. 14 of Ley 4757 already gives them the power to verify the physical volume. If they do it in-house, there is no purchase line.

International assaying and umpire laboratory (and by extension the large international certifiers)~80-100% of what is bought today in umpire work and assaying estim

The only real and credible incumbent in sampling, weighing and umpire assaying. OAA accreditations LE187 (Maipú, Mendoza) and LE273 (Palpalá, Jujuy — lithium in brines by ICP-OES), with Catamarca listed as an office WITHOUT any stated specialization or accreditation verif.

See the evidence
Each OAA scope carries the laboratory's address verif, so today, as we read it, it cannot lend its accreditation to Catamarca thesis. It is the same incumbent that dominates the brine laboratory.
Big-4 and national tax firms (royalty and transfer pricing advisory)~50-70% of paid advisory [assumption, no source]

They argue the valuation of the base and the defense of deductions, but none has a specialized office in Catamarca or metrological capability: they can fight over the value, not measure the flow. The share is a stated assumption and is not used to size the TAM.

See the remaining 3 players
INTI (legal metrology and the national traceability chain)not a competitor: it is the traceability provider -- and it does not have a single laboratory in the province verif

INTI is the national authority on legal metrology, but which instruments in this chain require type approval or periodic verification under Ley 19.511 (SIMELA) is still unconfirmed against the rule, which is why no claim on that point is used as a lever for this niche unconf. What did stay verified is the geography, and it is the useful half of the datum: across the open registry of inti's 332 laboratories, Catamarca has zero verif. Of the agency's 30 Metrology laboratories, none is in the province and none in the NOA except one: the Industrial Metrology Laboratory of La Banda, Santiago del Estero -- more than 600 km from the Catamarca capital and more than 1,000 from the Salar del Hombre Muerto estim. The rest are concentrated in Santa Fe, Córdoba, Buenos Aires, Chubut and San Luis. The metrological traceability that the fiscal chain needs is not nearby: it is imported from another region, or it is not done.

The local registry (Re.P.E.M. 229 suppliers / CAPPROMIN's category map)~0%

Zero categories for metrology, fiscal instrumentation, mining tax auditing or traceability software among the 19 categories and 123 memberships verif. The closest: professional services 7, electrical services 3, satellite monitoring 2, environmental services 4, insurance and guarantees 1. And only 12 suppliers in Antofagasta de la Sierra, the department of the salar (2,022 inhabitants).

Accredited calibration lab from Buenos Aires and the rest of the accredited private calibration network~100% of the accredited calibration available, 0% installed in the province

Who occupies the slot today, AND from where. An accredited calibration lab from Buenos Aires appears in the supplier registry of CAMYEN, the Catamarca State mining company, and is the only accredited calibration lab we could document serving the province. It is NOT from Catamarca and cannot be for Re.P.E.M. purposes: the OAA registry domiciles it in Tigre, province of Buenos Aires, and its accredited scope is, verbatim, "Calibration of torque tools type I and type II" -- torque wrenches, not flow or density or brine mass verif. It serves to size the gap, not to fill it. THE count that matters, over the full OAA registry: there are 29 accredited calibration laboratories in force across the whole of Argentina and they live in three provinces -- Buenos Aires 21, Santa Fe 7, Mendoza 1. Zero in Catamarca, zero in the whole NOA verif. Added to inti's 0 laboratories in the province, that is two independent national registries saying the same thing: the metrological traceability chain that a fiscal measurement needs in order to be enforceable does not have a single accredited link within ~1,000 km of the salar estim. That is the gap, and it is now proven by registry rather than assumed.

The jobs it createsWith the same rigour as the risk: this is 12-20 jobs, not 200 — it is the smallest niche in employment of the whole Catamarca pass and anyone selling it as a mass job creator is lying. What it does have is the best qualification-to-capital ratio in the chain and a peculiarity no other line on the salar has: IT IS city employment, NOT camp employment. Sal de Vida's primary source documents a regime of '5 days on / 2 off, 40 hours a week, applicable solely to the staff of the Catamarca city office', against the site's 14x14 of 9.5 hours at 4,100 masl verif: an office with campaigns, with no uprooting and no 7x7 rotation, in a province where mining pays 2.8x the private-sector average (ARS 4,496,304 vs ARS 1,612,706 as a 12-month average, OEDE-SIPA) verif.Trades with a concrete, short route: instrumentation and control technician (verification of electromagnetic and Coriolis flow meters, 4-20 mA loops, weighbridge verification with standard weights, instrument sealing — months of training on an electromechanical technician base); metrology technician (standards, uncertainty calculation, managing an ISO/IEC 17025 scope: it is the trade that does not exist today in the province and the one that enables everything else); lot sampler/inspector with chain of custody (the only role requiring physical presence at the salar's fiscal point: 2-6 jobs that CAN be from Antofagasta de la Sierra, where there are 2,022 inhabitants and there were 12 registered suppliers in May 2025 — it is the part of this niche that reaches the puna); laboratory analyst with ICP-OES and atomic absorption, with an existing talent pool (UNCA produces chemists and chemical engineers, and Minera Cordillera Litio / Arex Mining set up a laboratory in the province where, counting the administrative area, 40 people work; 89% of the company's staff are from Catamarca and the laboratory's two areas are run by local chemical engineers prob — proof that the team can be built here); data analyst/developer for the traceability system; and an accountant or tax lawyer specialized in mining (two profiles imported from Buenos Aires today).The linkage that remains: an accredited calibration laboratory in Catamarca serves more than lithium — it serves every commercial scale, fuel dispenser, weighbridge and meter in a province of 429,562 inhabitants; it is the only piece that, once installed, leaves permanent capability independent of the carbonate price. And the written standard (the biprovincial fiscal metering protocol) is a public asset: if it is written well, every future supplier works better.The three limits, stated in full: (1) these are professional, urban jobs that do NOT reach the resident of Antofagasta de la Sierra except through the 2-6 sampling roles; (2) all the employment depends on the function being bought rather than done in-house, and that is not decided; (3) if Congress settles the boundary, half of these jobs disappear along with the agreement.

How we
calculate it

The number is our own estimate. The calculation, step by step, is below.

The full calculation, step by step
Annualization window: 4 years — and it is a THIRD Catamarca window, different from the other two. This niche divides over 4 years, not the canonical 3.5 nor the extended 5, because its clock is neither the capex one nor the RIGI act one: it is the fiscal metering system, which is defined when CP2 starts up and the two-province scheme is set, and once built it is recalibrated on an annual program. ⚠️ Practical consequence: its TAM/year does not compare directly with any other Catamarca niche.Bottom-up in five steps, with stated no-double-counting.Step 1 - Perimeter (how many plants are covered): 2 projects / 3 fiscal points, NOT four. (a) Sal de Oro / POSCO: volume leaving the strip toward CP1 (hydroxide, General Guemes, SALTA: 25,000 t/year LiOH = 21,990 t LCE, ~80% utilization, operating since Oct-2024) + carbonate plant CP2 on the salar (23,000 t/year LCE, inaugurated on Oct 6, 2026 verif Presidencia de la Nación); the 3+3 interprovincial authority was created for this project. (b) Diablillos / AbraSilver-Pacific Rim: a 3.15 Mt/year plant (Ag-Au), RIGI Res. 562/2026 Gazette May 11, 2026 verif Resolución 562/2026, DFS Jul 20, 2026, plant not yet built; interprovincial management committee with 4 subcommittees including the tax one. (c) Fénix is left out: 7.6% (25 km2) of MdA's concessions are in dispute but the wells and plant are 'south of the disputed areas and unimpacted' unconf notice to the Australian stock exchange of Dec 4, 2025, not located. (d) Potential perimeter: overlapping titles granted by Salta to Taballione Carlos Dante and Alpha Minerals S.A., with objections from MdA.Step 2 - legal demand (the rule in force today): Ley 4757 art. 5 (base = physical volume extracted at the mine mouth, 'prior to any transformation process'; value = first commercial stage minus transport/freight/insurance, crushing/grinding/beneficiation 'and every treatment process', marketing, administration, smelting and refining, without depreciation and without deducting extraction), art. 6 (3%; 3-5% for new projects under Ley 5871), art. 7 (monthly sworn statement + ex officio assessment), art. 11 (automatic fine of up to 100% of the royalty), art. 12 (Mineral Transit Permit), art. 14 (verification of the physical volume extracted) verif all. The 50/50 agreement does not create the obligation: it duplicates the auditor, because the same volume and the same list of deductions have to be accepted by two tax agencies with no common standard.Step 3 - risk anchor (the mass the split operates on): Sal de Oro at full ramp 30,000-45,000 t LCE/year estim x USD 19,000-22,000/t estim (supported by Rio Tinto's realized price, USD 18,960/t in H1-2026, and by the Q2-2026 spot, USD 22,043/t average and USD 19,400/t at close verif Rio Tinto results) = USD 570-990 M/year of gross value -> royalty via the statutory route (3% on a mine-mouth base of 80-90% of gross) USD 14-27 M/year, or via the Fénix-type contractual route (a ceiling of 2% of sales + 0.3% CSR) USD 11-20 M/year -> band USD 11-27 M/year (midpoint ~18), i.e. USD 5.5-13.5 M/year PER PROVINCE; + extraction turnover tax 0.75% x gross = USD 4.3-7.4 M/year; + episodic stamp tax (1.5% purchase orders and works and services contracts, art. 26 subs. 2 / 2% acts over mining rights, subs. 1) = annual fiscal mass under the split USD 8-24 M/year, midpoint ~15, of which the Catamarca half is USD 4-12 M/year.Verified contrast: all of Catamarca's mining royalty collections are ARS 10,286,910,844.69 in 2025 and ARS 12,143,581,807.87 in H1-2026 (ARCAT API series) = an annualized run-rate of ~USD 15-17 M/year at an estimated exchange rate (not anchored). In other words: the disputed strip puts in play each year a mass of the same order as the province's entire mining collections, and there is no agreed method to measure it. Step 4 - The biprovincial core (units x price, with a billed FTE of USD 100-160k/year anchored in the Catamarca SIPA letter C pay of ARS 4,496,304/month averaged over 12 months verif ~ USD 34-37k/year of cost, which reconciles with the USD 35,500/employee/year implied by Sal de Vida's feasibility study): A) implementation of the fiscal metering + traceability system per plant (redundant flow metering at 4-8 points, type-approved weighbridge, automatic sampling, sealed historian, initial calibration protocol and a file for two tax agencies) 2 plants x USD 0.35-1.10 M [stated assumption; cross-check: 0.07-0.23% of Diablillos' USD 481 M capex] / 4 years = USD 0.18-0.55 M/year; B) annual program of traceable calibration, verification and sealing, 3 campaigns/plant/year x USD 9-20k = USD 40-90k/plant/year = USD 0.08-0.18 M/year; C) umpire laboratory for fiscal lots, 40-120 lots/year x USD 550-1,600 (assays USD 150-400 at open list prices from the Actlabs 2026 price list: prep RX1 12.40 + Li 4-acid ICP-OES 15.65 + multi-element ICP-OES 43.50; custody and certificate USD 400-1,200 [assumption]) = USD 0.02-0.19 M/year; D) biprovincial traceability and settlement software, implementation USD 0.12-0.40 M + support USD 50-150k/year = USD 0.08-0.25 M/year; E) royalty auditing, mine-mouth base valuation and technical assistance to the subcommittees, 2-5 FTE x USD 100-160k = USD 0.20-0.80 M/year [risk cross-check: 1.5-4% of the USD 11-27 M mass = USD 0.2-1.1 M/year, converges]. Core subtotal with both plants = USD 0.5-2.0 M/year (midpoint ~1.1); with Sal de Oro only (today, Diablillos with no plant) = USD 0.3-1.1 M/year (midpoint ~0.6). Step 5 - the adjacent Catamarca layer (same capability, without the biprovincial law, and it survives that switch): F) implementation/upgrade of fiscal metering at 4 operations (Fénix, Sal de Vida, HMW, 3Q) x USD 0.15-0.50 M / 4 years = USD 0.15-0.50 M/year; G) annual calibration and verification at 4-5 sites x USD 40-90k = USD 0.16-0.45 M/year; H) certification of brine inventory in ponds and mass balance (Galan accumulates ~10,000 t LCE in the open with an 8-12 month cycle) 3-4 operations x USD 30-120k = USD 0.09-0.48 M/year; I) mine-mouth base valuation, preparation and defense of the monthly sworn statement and the 3% vs 5% classification under Ley 5871 (a 2-point exposure), 4-6 clients x USD 40-150k = USD 0.16-0.90 M/year. Adjacent layer subtotal = USD 0.6-2.3 M/year (midpoint ~1.3). Gross biprovincial total = USD 1.1-4.3 M/year, midpoint ~USD 2.4 M/year.Why the published number is only the Catamarca side: USD 0.8-3.0 M/year, midpoint ~USD 1.8 M/year (and USD 0.65-2.55 M/year today, with Diablillos still without a plant); the complete biprovincial business, labeled as such, is USD 1.0-3.9 M/year.What does not go into the number (no double counting): Sal de Oro's CP1 hydroxide plant is in General Guemes, SALTA (its instrumentation is Salta activity; only the metering of the volume extracted from the strip is counted); half of the biprovincial core is Salta's mass and is published separately; daily process control, environmental aquifer monitoring and exploration characterization are counted in the brine laboratory niche (only fiscal lots with umpire custody are counted here, USD 0.02-0.19 M/year); detailed engineering and construction document management are in the detailed engineering niche; MARA/Agua Rica (capex on hold) and Kachi (pre-FID) are stated optionality, not TAM; Rincón belongs to Salta.

Concentration The market is not concentrated: IT IS NOT bought. There is no dominant supplier to displace; there is a function executed internally, with no standard and at zero market cost. A single international laboratory monopolizes the credible technical leg —umpire work and assaying, with OAA accreditations in Mendoza and Jujuy and nothing stated in Catamarca—, no player covers the three competencies the service demands at once (independence admissible before two tax authorities + accredited traceability + operation at 4,000 masl), and the natural buyer can self-supply with public staff. Across 229 active suppliers in the Re.P.E.M. there is not a single local competitor in this line. The competitive risk is not an incumbent: it is the status quo.

The rule that moves it

The driver of this niche is a double act of State: Catamarca's Mining Royalties Ley 4757 sets the base at the physical volume extracted at the mine mouth, requires declaring it every month and empowers the tax authority to verify it with a fine of up to 100%; and the Salta-Catamarca agreement over the disputed Hombre Muerto strip duplicates that control, because the same volume and the same deductions now have to be accepted by two tax administrations that share no standard.

See the underlying reading

The underlying policy that opens up this demand. It is the same inference declared by the rules and the program pillars pushing in this direction.

federal-provincial tension
enables
Salta and Catamarca split 50/50 what is extracted from the disputed strip, without settling the border
See the rule →
The Sáenz-Jalil agreement of May 2021 and the Diablillos one split 50/50 between Salta and Catamarca the royalties, the provincial taxes and every other levy on what is extracted from the disputed strip.
See the full legal grounds
Salta approved them through leyes 8523 y 8524, published on Jan 9, 2026, and Catamarca the Diablillos one through Ley 5940, published on May 22, 2026. The agreements themselves create the bodies that oversee it: an interprovincial authority of three representatives per province for Sal de Oro (mining-environmental control and mining police) and a management committee of three per province for Diablillos, with subcommittees for procedures, environmental impact and control, and a tax subcommittee of two per province made up of the heads of the tax authorities. It enables the niche because it duplicates the auditor without creating the method. And it carries its own switch: the ninth clause says that «once the boundary dispute is resolved by an Act of the National Congress, this agreement shall become void», and the titular province remains the sole authority. Watch the scope: the full text of the agreements is published as an annex to Salta's laws, and the Diablillos one provides for technical metering devices at the plant intake verif; Catamarca's Ley 5940 approves the Diablillos one without transcribing the annex.
enables
Re.P.E.M.: Catamarca's mining local-content rule is a resolution, not a law
See the rule →
The Re.P.E.M. (Resolution S.E.M. 498/2014) is both the door and the filter: it requires legal domicile in Catamarca with 2 years of seniority, 50% local partners, 70% of the professional, technical and administrative payroll from Catamarca with 2 years of residence and a semi-annual sworn statement.
See the full legal grounds
In this line the requirement bites where it hurts most —a metrologist or a mining tax specialist with two years of provincial residence barely exists in a province of 429,562 inhabitants whose salar department has 2,022— which is why the realistic entry route is the joint venture with at least 50% local suppliers that the regime itself admits, with the precedent of a Catamarca firm inside a USD 130 M EPC.

Where the number comes from

~USD 1.8 M/year at the midpoint on the Catamarca side; the band is USD 0.8-3.0 M/year, and today —with Diablillos still without a plant— USD 0.65-2.55 M/year. Counting both provinces, the complete biprovincial business is USD 1.0-3.9 M/year

See the calculation, the variables and how it was validated

The TAM is built from three variables you can watch: how many fiscal points are covered, what an integrated retainer per plant is worth and how much rent is at stake (which is the ceiling: nobody spends more on measuring than what is being split). Change one and the number is recalculated.

~5-6 fiscal points covered × ~USD 0.25-0.70 M/year of integrated retainer (metering + traceability + auditing)=~USD 1.8 M/year at the midpoint on the Catamarca side; band USD 0.8-3.0 M/year
Fiscal points covered2 today → 5-6 with Diablillos and the provincial layerlive data
The perimeter of the 50/50 split is TWO projects, not four: Sal de Oro (one plant operating in Salta with the volume that leaves the strip, and the salar's carbonate plant starting up) and Diablillos (a plant not yet built). Fénix is left out: its own owner states that 7.6% of its concessions are in dispute but that the wells and the plant are south of the disputed area and unaffected. The other 4 points are the operations that settle royalties on their own.
Integrated retainer per plant~USD 0.25-0.70 M/plant/yearannual review
The sum of five services: amortized fiscal point implementation (USD 0.35-1.10 M per plant), traceable calibration and verification (USD 40,000-90,000/year), umpire laboratory by lot (USD 550-1,600), settlement software (USD 50,000-150,000/year) and royalty auditing (2-5 professionals at USD 100,000-160,000 each). The labor cost is anchored in the official pay series for Catamarca mining; equipment and software prices are our own stated assumptions, because nobody publishes them.
Annual rent at stake (the ceiling)USD 8-24 M/year under the 50/50 split (midpoint ~15) — the Catamarca half is USD 4-12 M/yearlive data
An audited band. The starting estimate was USD 15-35 M/year (midpoint ~25) and the audit cut it back by correcting the royalty component and bounding the Turnover tax one. It is still of the same order as ALL of the province's mining royalty collections (run-rate USD 15-17 M/year on the ARCAT series), which is what orders this niche: nobody spends more on measuring than what the split is splitting. Royalties plus Turnover tax on what is extracted from the strip once Sal de Oro is at full pace (30,000-45,000 t of carbonate equivalent at today's price). For comparison: ALL of Catamarca's mining royalty collections run at USD 15-17 M/year according to arcat's official series. It moves with the lithium price, which is the only truly live input in the model.

A robustness check by three routes —and our own audit says that none of the three validates the bottom-up, so the number rests on the method and not on them—: (a) by risk, an assurance program costs 2-8% of the rent it protects → USD 0.3-2.8 M/year for the core, and the bottom-up gives 0.5-2.0: it falls inside, but the band is 9.3× as wide and any result would fall inside; (b) top-down, 5-6 plants × USD 0.25-0.70 M of retainer = USD 1.3-4.2 M/year, which falls ABOVE the published range; (c) by headcount, the midpoint equals ~13-18 full-time equivalent professionals for the whole province, but the price per professional is an input of the calculation itself, so dividing and getting the head-count back is an identity, not a verification. What does stand: this is a niche of 12-20 qualified jobs, not of a hundred million.

The number rests on a few variables. The formula shows how it moves when each one changes; and each variable carries its freshness seal — how often it is worth revisiting. estim

How solid the number is estim

The anchor is not a projection: it is the law. We opened the text in force of Catamarca's Mining Royalties ley 4757 and read the six articles that create the obligation to measure: the base is the physical volume extracted at the mine mouth (art. 5), settlement is by monthly sworn return (art. 7), the law allows an automatic fine of up to 100% of the royalty (art. 11) and its implementing decree graduates it: 10% to 30% for failing to file, filing incomplete or filing late, and two to five times the royalty if falsehood in the sworn statement is proven, transport requires a Mineral Transit Permit (art. 12) and the authority may demand the documentation for the verification of the physical volume extracted (art. 14). We then measured the mass at stake with ARCAT's official collection series and with the carbonate price published by the largest operator. And we say what we could not confirm: the text of the agreements between the two provinces is not published —the law approving them is, the annex is not—, so the phrase going around about «metering devices at the plant» is one we did not find in any of the four sources we opened. The annual total is our own estimate: we multiply covered plants by service price and cross-check it against the size of the rent it protects.

Coverage: the register of accredited bodies of the Organismo Argentino de Acreditación, the country's only accreditation body (341 accreditations, counted one by one: none domiciled in Catamarca and a single one in Salta), and INTI's list of laboratories by province (332 records) · Sep 14, 2026 · not reviewed: the national register of manufacturers and repairers of measuring instruments was not opened, and it would be the exact universe for the calibration leg; and the international supply of royalty-settlement software cannot be swept from here

How to cite this figure: Despegue (2026). Fiscal metering, traceability and royalty auditing at the Salar del Hombre Muerto (Catamarca) · Catamarca. despegueargentina.com/en/catamarca/medicion-fiscal-biprovincial-hombre-muerto · terms of use

Neighbouring markets2 markets in the same group, from USD 8 to USD 95 M a year

First step · free
The first read of your company

We look at what your company does and tell you whether we see a sign that it fits this market, with the evidence behind it. If we do not see one, we say so too and name the condition that would change it. One page as a dated PDF, within 48 working hours.
Not here for a company? Invest · Work (in Spanish) · Start a business (in Spanish) · Institutions
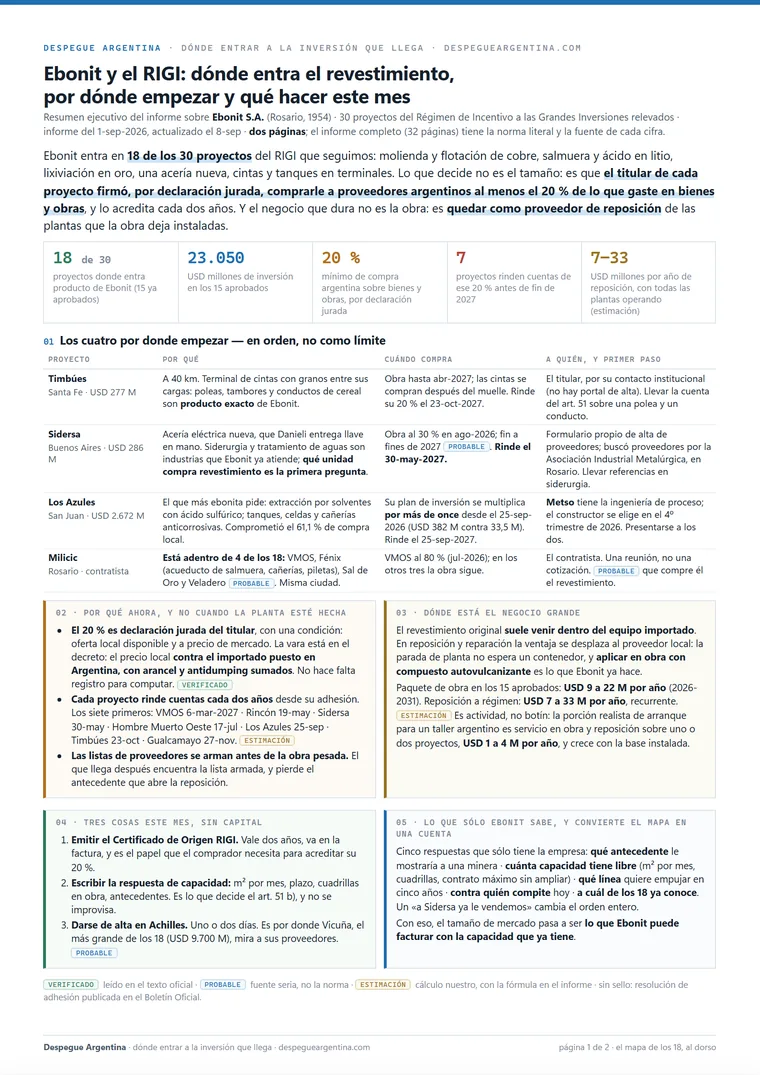
Page 1 of the example executive summaryOpen the report ↗A real analysis · a real company, open in full →
Ignacio Aredez
Analysis and curation: Ignacio Aredez
Head of Despegue
Method and track record →
  • 20+ years in technology, 15 of them in data and AI, for clients across Europe and the Americas
  • Certified in AI governance (ISO/IEC 42001)
  • Machine Learning (Google Cloud)
  • Registered expert with the European Commission
How to read the seals →
  verif primary source · prob primary source pending · unconf a source said it · estim our own calculation · thesis our reading · the date belongs to the datum, at the precision its source allows
This is not financial advice. The TAM is an estimate with a transparent method, not an official figure; the framing is labeled as thesis. Every figure carries its source. ← All opportunities in Catamarca