Despegue ← Catamarca OPPORTUNITY
11 more opportunitiesOther opportunities ▾
ESEN Where my company can get in
Catamarca · Lithium puna · process reagents and last-mile logistics
Four new plants in 12 months and a single domestic producer, some 1,700 km from the salarthesis

Lithium process reagents and their last mile to the puna (Catamarca)

Estimated entry range for a supplier
USD 2-6 M/yr
in 2-3 years
Estimated market: USD 55-95 M/year of reagents delivered at the plant gate
up to date · reviewed Sep 22, 2026
estim Jul 25, 2026midpoint ~USD 70 M/yearurgent demandour reading
At a glance
Who buys
The operator's procurement desk — global, not provincial
the 3 doors →
In which projects
Fénix, Salar Tres Quebradas
what each one invests →
When
The reagent is bought from the day of commissioning and follows the forty years of mine life. The only thing with a date is how much capacity has to be supplied, and the floor already committed is 75,000 tonnes of carbonate a year. verif Jul 29, 2026 ↗
what to watch and where it stands →
The main barrier
Since January 2026 the reagent does not travel like any other cargo: it goes in a separate convoy, escorted, daylight only and with lower weight caps. The four of them make the trip dearer, and the capability that gets paid for is assembling and dispatching convoys. verif in force since 2026 ↗
the whole entry map →
Where you get in
Do not start by fighting for the molecule: South America's only producer sits at the other end of the map and your own plant is nine-figure capex. Enter where the barrier is not the international price but being up there, qualified and with the shed in place:
the 3 routes →

Lithium's most expensive input is not energy or labor: it is reagents, and Argentina barely produces them. Rio Tinto published that they were 42% of its production cost in 2025; the national State measured them at USD 1,918 per tonne of carbonate and warned that ~90% of that money is a single product: soda ash. South America's only producer sits in Río Negro, some 1,700 km from the salar in a straight line — and the State itself wrote that this freight «weighs very heavily on the final cost of a tonne delivered to the salar area» and that a complementary plant should therefore be installed near the lithium projects. With four Catamarca operations starting up in 12 months, that leaves a market of USD 55-95 M/year of reagent delivered at the plant gate. The molecule is fought over abroad; what is left on this side is the last mile —storage, silo, big bags and the final 145 km of dirt at 4,000 meters— which today is solved project by project: three operations do not publish who provides it and the fourth's feasibility study declares that it outsources it to a local company. Nobody sells it as a shared service to all four.

This is not a window niche: the reagent is opex and gets consumed every day for the ~40 years of mine life. It starts with four start-ups in 12 months and grows with every ramp-up.

verif primary sourceestim our own calculationthesis our readingHow to read all five →

What the market is made of

The TAM is activity, not what you will invoice — and in reagents the difference is brutal. The molecule travels from Wyoming, Turkey or Río Negro; the purchase is decided by a global desk (Rio Tinto controls two of the three plants that consume, and planned to import half of its soda ash through a Chilean port); and on-site conditioning is already built, with three separate warehouses and two forklifts dedicated to reagents alone. All of that is captive. Your real gap is the last mile: storage, silo, bagging, quality control and the final 145-215 km of dirt — the addressable segment, small in money and large in accessibility.

How it splits, and against which total
Midpoint of the captive/addressable split over the mid-range reagent TAM delivered at the plant gate, ~USD 70 M/year, per the funnel. The last mile is sized separately. Our own estimate. estim
CaptiveUSD 62 M · 89%
Addressable (SAM)USD 8 M · 11%
CaptiveUSD 62 M89%non-addressable
the imported molecule (Wyoming, Turkey) or ALPAT's in Río Negro + the operator's global procurement —Sal de Vida planned to bring in 50% through the port of Antofagasta, Chile— + the on-site conditioning the four operators have already built themselves
Addressable (SAM)USD 8 M11%addressable
the complete last mile: storage terminal, silo, big-bag bagging, moisture and insolubles control and the final 145-215 km of dirt up to the plant gate, plus customs clearance of the imported reagent
Non-addressable

~USD 62 M/year (~89% of the reagent TAM), in three layers that do not compete with one another.

See the full breakdown
(a) THE molecule — it travels from Wyoming, Turkey or San Antonio Oeste; the United States holds 92.12% of world reserves and ALPAT, in Río Negro, is South America's only producer: a Catamarca entrant does not manufacture soda ash; (b) THE operator's global procurement — Rio Tinto controls 45 of the base's 65 ktpa and buys in bulk, Sal de Vida planned to import 50% through the port of Antofagasta (Chile), Livent has the Pocitos-Antofagasta railway reinstated to import reagents and Zijin runs on a Chinese supply chain: the reagent can reach the puna without an Argentine purchasing decision; (c) THE on-site conditioning, already built — Reagent Storage + Reagent and Consumable Preparation with three separate areas, 4 forklifts (2 dedicated to reagents), 5 forklifts going to 10. The operator does not buy conditioning: it buys reagent delivered to its shed.
Addressable share

USD 4-12 M/year addressable by a local/domestic entrant = essentially the entire last-mile TAM (puna freight + storage + conditioning + bagging + dosing: USD 7-30 M/year) plus the clearance and bonded-warehouse fee on USD 48-83 M/year of nationalized merchandise, plus the unquantified upside of regional quarry lime (the lime ratio per t of LCE is missing). The basis for the SAM is not inference: the project's primary source states that reagent and product logistics are OUTSOURCED TO a local company in three independent mentions.

Entry range for a supplier

USD 1.5-5 M/year for ONE entrant within 2-3 years. Honest arithmetic: you do not win all four operators (Rio Tinto contracts in bulk for two operations and Zijin brings its own chain), so the wedge is 1-2 clients over 30-50% of the SAM. A realistic path, in this order: (1) a handling and last-mile subcontract with the logistics company already approved — 2-4 months to first invoice; (2) your own storage terminal with one operator under contract — 6-12 months; (3) scaling up to supply delivered at the plant gate, with the molecule bought from an importer.

▸ A warning almost nobody gives: the RIGI local-content commitments —95.34% at Hombre Muerto Oeste, 60% at Fénix— are the local share of what each project pays suppliers, and the regulation counts goods and works there, not services; the reagent, moreover, is operating spend. They widen the climate and the buyer's willingness; they do not guarantee a single peso of demand for this category.

Who really pays?

«The mine» is not a single door, and in reagents the money splits into three flows contracted separately — one of them does not even pass through Argentina:

If you sellThe molecule: soda ash, lime, caustic soda, hydrochloric acid
→
The operator's procurement desk — global, not provincial prob Mar 31, 2022 ↗

Rio Tinto controls two of the three plants that consume carbonate in Catamarca and buys in bulk prob; Sal de Vida's feasibility study planned to import 50% of its soda ash through the Port of Antofagasta, Chile, and Livent reinstated the Pocitos-Antofagasta rail link used, verbatim, «to import reagents» verif. South America's only producer, ALPAT, is in Río Negro: it does produce —170,000 to 210,000 t/year declared to the State— but freight to the salar weighs so heavily that the official study itself says a complementary plant near the lithium projects should be considered verif.

If you sellFreight and logistics of reagent and product — the lowest-capital door
→
The operator, which in its study plans to outsource this service to a local company verif Mar 31, 2022 ↗

Sal de Vida's feasibility study says it without hedging: «lithium carbonate and reagent transport logistics will be outsourced to a local company». It also clarifies twice that the operator provides fuel and servicing to all of its fleet except reagent and product logistics. Reagents arrive in 1 t big bags on 28 t flatbed trucks. It is the link in the niche that the study puts in writing as outsourced and local thesis.

If you sellOn-site conditioning (receiving, storage, dissolution, dosing)
→
Today nobody: the operator self-supplies it — and that is where the gap is verif Mar 31, 2022 ↗

Sal de Vida built a reagent storage warehouse and a reagent and consumables preparation building with three separate storage areas —quicklime, caustic soda and sodium carbonate—, plus its own lime slaking plant; it has 4 forklifts, 2 dedicated exclusively to reagents, and a forklift fleet that goes from 5 to 10 when it scales up. The four operators on the same salar replicate the same infrastructure. You beat it on price at the next scale-up, not by regulation.

▸
The lesson: the molecule is bought abroad and can come in through Chile without touching Argentine customs; freight and the last mile are written as a local contract; and conditioning is paid for by the operator four times over, in four different sheds, at 4,000 meters.

Which projects move this demand

USD 251 M Apr 6, 2026 ↗

Expansion (Phase 1B) of the historic Fénix lithium-carbonate project in the Salar del Hombre Muerto, operated by Rio Tinto via Minera del Altiplano…

see the project →

Tres Quebradas stage 2: plant and infrastructure for 40,000 t/year of lithium carbonate via direct extraction (DLE), per art…

see the project →

When the window opens

In reagents what you watch is where the molecule comes from and how it can be moved. The plant of 40,000 tonnes a year approved at Tres Quebradas on 29 July 2026 has construction from June 2026 and operation scheduled for 1 April 2029. And there are two rules that are never announced because they are already written into the regulation: from 1 May to 30 September a winter procedure applies, which pushes you to have the input stockpiled up there beforehand; and since January 2026 the reagent travels in a dedicated convoy, escorted and only in daylight. These four numbers are the ones that give notice.

What to watchWhat changes when it happensStatus
The tonnes of lithium carbonate Catamarca produces
It is the whole multiplier: each tonne of carbonate calls for between 1.4 and 2.081 tonnes of soda ash.
40,000 to 50,000 effective tonnes in 2026 and 65,000 to 75,000 of nameplate capacity; and since 29 July 2026 there is an act for a plant of 40,000 tonnes a year at Tres Quebradas by direct extraction, which takes the nameplate floor to 75,000.
See the evidence
the 115,000 ceiling assumes those tonnes are additional, and the act does not say that
verif Jul 29, 2026 ↗
The price of imported soda ash and its tariff
It is 90% of the money in this category: it moves the entire bill for the main input.
it went from USD 260 to USD 485 a tonne between 2018 and 2023, plus a 9% tariff. ⚠️ It is a series and needs re-dating: the last published point is from 2023 prob 2023 ↗
The state of the sole domestic producer
If it falls, the whole volume shifts to imports and the clearance and bonded-warehouse business grows; if it expands near the salt flats, the haul of more than 1,700 kilometres disappears and with it half the argument.
ALPAT in crisis because of soda ash imports: according to the union, it sells about 80,000 tonnes a year against the 120,000 it needs to be profitable, and in September 2026 it laid off more than 30 non-union staff and dismissed 3 unionised workers, with wages paid in instalments under a preventive crisis procedure prob palabra del gremio prob Sep 22, 2026 ↗
The regime for transporting chemical substances in Catamarca
It defines how the input moves and what each trip costs: dedicated convoy, outsourced escort, daylight only and lower weight caps.
in force since 27 January 2026, with 15 days for each company to adapt its own protocol.
See the evidence
The clause ordering the separate convoy names the reagents literally
verif Jan 27, 2026 ↗
What signals the game has changed
Direct import through the operator's chain (the most likely and the most structural)

If the reagent comes in through Chile (port of Antofagasta) or via the Pocitos-Antofagasta railway under an international trader's contract, the last mile stays inside that contract and the local entrant never sees it.

See the evidence
It is already written in the feasibility study: Sal de Vida planned 50% of its soda ash through a Chilean port. Permanent exposure, decided at every renewal of the supply contract.
Lithium carbonate price

Today the wind is strongly at its back: Q2-2026 spot USD 22,043/t (+125% y/y in the first half), Rio Tinto's realized price USD 18,960/t and Fénix's C1 below USD 5/kg verif Rio Tinto Q2-2026 filing with the SEC.

See the evidence
with that margin nothing stops, and the structural driver is BESS (~30% of lithium demand, shipments +108% y/y verif ídem). If the price returns to USD 10-12k, 3Q's Phase 2 and Sal de Vida's Stage 2 get postponed: the ceiling of the TAM falls, not the floor — the reagent for operations already running is consumed all the same. Continuous exposure on the ceiling, low on the floor.
Delay or cancellation of stages (risk of a missing act of State)

Tres Quebradas' Phase 2 now has its act: resolution published on 29-Jul-2026, with USD 594,136,000 of computable investment verif — the USD 709 M was the announced amount.

See the evidence
Sal de Oro's 2nd stage as well: Resolución 1157/2026, published on 31-Jul-2026, with USD 207,936,427 of computable investment verif Resolución 1157/2026, and its plant was inaugurated on 6-Oct-2026 verif Presidencia de la Nación; the USD 547 M is the investment published on the regime's official portal verif the regime's official portal and does not appear in the resolution. The 115 ktpa scenario —the one that takes the TAM to USD 240 M/year estim— no longer depends on the act coming out: it depends on whether the 40,000 tonnes the act approves are additional to the previous phase, something the resolution does not clarify. That is why the published floor is 75 ktpa and the 115 stays as a scenario thesis. Exposure 2026-2028.
Technological substitution: DLE shrinks the consumption ratio

Fénix went from a 2-3 month to a 1-2 day concentration cycle with Phase 1B. Less evaporation and less softening push the ratio from the 2.081 actually observed toward the stoichiometric 1.435: up to 31% less soda ash volume at the same output.

See the evidence
And Catamarca concentrates four different lithium flowsheets within 200 km, three of them DLE variants (selective adsorption at Fénix, ion exchange at Kachi, hybrid adsorption at 3Q). It is the silent killer of volume, gradual between 2027 and 2032.
See the remaining 5 risks
Ninth clause of the Salta-Catamarca agreement

The Sáenz-Jalil agreement (May-2021) splits the taxes and royalties of the disputed Hombre Muerto strip 50/50, and lapses once Congress settles the boundary: the winning province becomes the sole authority.

See the evidence
For a supplier that redefines the enforceable tax domicile, the applicable registry (Re.P.E.M. vs Salta's) and the Turnover tax jurisdiction over the strip. The Jan-2026 laws also created an interprovincial authority and a tax subcommittee with metering devices at the plant. By event and with no date (an 82-year-old dispute): low probability, high impact.
Social license and freight conflict

Three spills in seven months in Fiambalá and a $254.1 million fine on Zijin-Liex from the Ministerio de Minería de Catamarca prob converging provincial press after the brine spill of 25-Mar-2026.

See the evidence
According to those same sources the sanction was grounded in speeding, lack of preventive measures and shortcomings in training and in the handling of hazardous substances, and the impact was declared limited and reversible; the sanctioning resolution could not be opened in the provincial BO. Add to that: in Jun-2026 CAPROMITI claimed that Zijin-Liex had hired a trucking company from Córdoba and threatened road blockades in Fiambalá: the threat is documented, the blockades were not carried out prob provincial press. And the Río Los Patos injunction was lifted 5 votes to 2 with the case still before the CIDH as of the Aug-2026 cutoff: the litigation did not close, it paused. Continuous exposure — and in this niche the risk is double, because the truck IS the business.
Weather and road (the operating risk that gets paid in penalties)

The storm of Jul 21-23, 2026 left RP 43 Antofagasta-Salar del Hombre Muerto impassable, closed the Paso San Francisco with winds above 170 km/h, recorded -27 °C at 3Q's camp and forced the rescue of five miners with a helicopter brought in from Buenos Aires.

See the evidence
A supply contract with a delivery SLA and no well-drafted force majeure clause is a trap. Seasonal, every winter.
ALPAT, in both directions

If it executes its expansion to 550,000 t/year verif projection declared by ALPAT in the official study of the Secretariat of Mining, the domestic price falls and the trading margin compresses.

See the evidence
If import pressure beats it and it shuts down, all the carbonate is imported. Neither scenario touches the last-mile business: the distance is still there. It is the killer of supply, not of freight.
End of the construction window: DOES NOT APPLY (and this plays in favor)

This is what sets this niche apart from camps, geomembranes or earthmoving: the reagent is perpetual OPEX, not construction capex.

See the evidence
Fénix states 40 years of remaining mine life and Sal de Vida ~40 years. There is no post-2030 cliff: there is an operating core that grows with every ramp-up. The risk in this niche is not that the works end — it is technological substitution and the integration of the operator's chain.

The opportunity in depth

How to get inthe gap and the routes that open it
1

The shared storage and conditioning terminal. Today the same service is solved four times over, one per operation, and nobody sells it shared: covered shed, one-tonne big bags on 28 t flatbed trucks and dedicated forklifts. A terminal in the area with bulk receiving, silo, bagging, moisture control and shared freight turns four sunk costs into a service with a single asset. Ticket of USD 1-4 M of capex. And since January 2026 there is a rule that makes it dearer and more necessary at the same time: a provincial resolution requires the convoy of mineral and chemical substances —the text names the reagents— not to be mixed with other products, to carry an outsourced escort for every one to three trucks, to travel only in daylight and to respect lower weight caps. Pooling the same input from several operators into one convoy is still possible; what is no longer possible is mixing the reagent with other cargo to fill the truck.

2

Regional quarry lime, the only reagent with a possible 100% Catamarca chain. Sal de Vida receives granular quicklime and slakes it at its own slaking plant: it buys the product, it does not make it. The NOA has limestone quarries and the province taxes limestone at 0.75%. The lithium market asked for ~250,000 t of lime in 2023 and projects more than 800,000 t by 2027 prob — and nobody has documented who delivers it at Hombre Muerto. Here you compete against a freight rate, not against Wyoming.

3

Foreign trade and the bonded warehouse of western Catamarca. The provincial mining suppliers' chamber listed, in its 2023 category map, a single member in foreign trade for a portfolio that brings in a good part of its main reagent from abroad, with a 9% tariff (Sal de Vida plans to import half of its sodium carbonate through Chile). And the clearance link cannot be provided from within the province: out of the 175 bonded warehouses authorised nationwide, Catamarca has zero. What can change that is the Free Zone in the Tinogasta department, with the national agreement signed in September 2026 and awaiting the provincial legislature's vote.

What you needcapital, certification, tax regime and who pays
The reagent is paid for every month from the day of commissioning — there is no investment decision to wait for. What you need in order to enter:
Capital
From USD 1-4 M for a storage terminal with silo, weighbridge and forklifts, down to pure working capital if you enter as a handling subcontractor. The silent bottleneck: there is no public data on payment terms from the miners in Catamarca, and without that you cannot size the capital. And without the bond you have to post you do not close a big contract: that insurance is bought from a national insurer, so what decides is not local supply but your balance sheet.
Capability
Operating at 4,000-4,300 masl with -30 °C and winds of 20 to 120 km/h, on a road that gets cut off in winter (RP 43 was left impassable in July 2026). And a requirement of quality, not just logistics: the technical study warns that the soda ash's insolubles end up in the final product — moisture control, insolubles and batch traceability are the insurance policy. And since January 2026 the reagent travels in a dedicated convoy, escorted and only in daylight, with lower weight caps: that means more trips per tonne, and the convoy cannot be topped up with other cargo.
Regime
Register with the Re.P.E.M. (Resolution SEM 498/2014): domicile in Catamarca with 2 years of seniority, 50% local partners, 70% Catamarca payroll and a semi-annual sworn statement. Seniority is what stops the pure entrant and the 50% joint venture with a local firm is the vehicle the rule itself designed. The tax structure you invoice under changes the turnover tax rate.
Who pays
The operator buys the reagent delivered to its shed, but contracts freight and logistics separately — and by design, from a local company.
▸ You tell us where to see what your company does and we tell you whether we see a sign that it fits this opportunity, with the evidence behind it. See if my company fits this opportunity →
When you get paid, and what blocks it
It gets paid today, with no dead gap and without waiting for any FID: all four operations already consume. Fénix has produced since 1998 (Phase 1A at nominal capacity, 1B with first production in Q2-2026), Sal de Vida achieved first production in Q2-2026 ahead of plan, 3Q started up in Sep-2025 and HMW discharged its first chloride on May 28, 2026: four start-ups in 12 months, and the reagent is bought every month from the day of commissioning.The real bottleneck, in order of hardness: (1) Re.P.E.M. (Resolution SEM 498/2014) — the requirement that kills the pure entrant is seniority: legal domicile in Catamarca for 2 years, 50% of partners domiciled in the province, a joint venture with at least 50% local suppliers, municipal license + Rentas registration, 70% of the professional/technical/administrative payroll from Catamarca with 2 years of residence, and a semi-annual sworn statement (the silent filter that de-registers suppliers). The legal way out is a 50% joint venture with an already registered local firm: it is the vehicle the resolution itself designed, and there is proven precedent (Sal de Vida's EPC brought in a Catamarca construction firm alongside two contractors from other provinces). (2) Homologation as the operator's vendor, a separate and later process: each operator runs its own onboarding and Rio Tinto runs its own portal; the sign that the door is open is the 2nd Mining Suppliers Meeting (May 28, 2026, >500 suppliers with Rio Tinto, POSCO, Galan, MARA, Albemarle, CAMYEN and YMAD present as buyers) and Rio Tinto's program in Catamarca (+50 suppliers trained, 800 hours of assistance, +60% in requests for quotation, 90% acceptance). (3) Working capital, with one piece of data that does not exist: there is NO public information on the miners' actual payment terms in Catamarca, and without that you cannot size the capital of a business that buys merchandise or fronts freight; surety is a bottleneck of its own, because the 2023 registry of the mining suppliers' chamber had ONE (1) member in insurance. (4) Tax cost (Ley Impositiva 5.927): mining support services (code 99000) pay 3.00 / 3.90 / 4.80% of Turnover tax by bracket against 0.75% for extraction, and rental of mining machinery without operators (773020) the same; other invoicing structures pay different rates. Bracket I runs up to ARS 3,255,000,000 of 2025 revenue, and whoever starts activity from Jan 1, 2026 pays Bracket I for their entire first fiscal year (art. 16). Stamp tax: 1.5%. Art. 26 has its own mining chapter with two rows, and the 1.5% one —subsection 2— mentions verbatim 'purchase orders... their mining suppliers'; the 2% of subsection 1 reaches only acts linked to mining rights or to mines in general verif; in any case mining and its chain are among the few acts that still pay stamp tax in Catamarca (the general regime took commercial contracts to 0%). (5) Altitude, weather and quality: operating at 4,000-4,300 masl with -30 °C and winds of 20 to 120 km/h on a road that gets cut off, with no standard setting fitness criteria above 3,500 masl; and a technical requirement that is about product, not logistics — the feasibility study warns that 'sodium carbonate is of particular concern as insoluble deleterious elements will report to the product', with two cartridge filters in duty/standby and an ion-exchange circuit solely to clean the soda ash solution: whoever stores it takes on responsibility for the quality of the final carbonate, so moisture control, insolubles and batch traceability are the insurance policy, not an ornament.
Who you compete againstwho is already there and what share they take
Who is
already in
Market
split
Soda ash imports (unidentified traders)the bulk of Argentine lithium's supply

Imports are the reference supplier even though ALPAT produces: 600,000 t imported for lithium between 2016 and 2023 = 41% of Argentina's total imports of the compound prob; 34.18% of the country's entire import of it goes to LCE verif. Probable origin: the United States (92.12% of world reserves, USGS 2022) and Turkey (3.52%) verif. A non-refundable 9% tariff. NO trader identified by name: that is the stated gap in this map.

ALPAT — Álcalis de la Patagonia SAIC (Grupo Indalo)South America's only producer, in Río Negro

Punta Delgado, San Antonio Oeste, Río Negro — ~1,700 km from the salar in a straight line (more by road). Ammonia-soda process with assistance from Krebs Paris.

See the evidence
its own limestone from the La Calera and Paileman quarries (80 km, via the Tren Patagónico) and salt from the El Gualicho salt flat (48 km). 225,000 t/year of installed capacity and ~400 employees, and it supplies sodium carbonate to glass, powdered soap, silicates, water treatment and lithium carbonate — the official study names it explicitly among its customers. Production series declared by the company itself to the State: 170,000 t (2021) · 170,000 t (2022) · 210,000 t (2023), against 250,000 of nominal capacity verif; from 2024 onward the official table equates production to nominal (330,000 and then 550,000) verif, so that is company projection, not measured production. Stated investment plan: 300,000 t/year and then 500,000 t/year verif. What no version of the study covers is 2025-2026: in April 2026 a Río Negro legislator petitioned Economy and Trade to limit imports —Chinese ones in particular— in defense of the plant, citing 440 direct jobs, layoffs already recorded and threats to discontinue production prob. Translated: it produces, below its nominal capacity, under import pressure and far away.
The operator's own global procurement (Rio Tinto, Zijin)captive, high and rising — Rio Tinto controls 45 of the base's 65 ktpa

Sal de Vida planned to import 50% of its requirement through the Port of Antofagasta, CHILE (that half never touches Argentine customs); Livent reinstated the Pocitos-Antofagasta rail link 'used to ship product and import reagents'; Rio Tinto's '30 in 30' plan states 'program based contracting strategies'; Zijin runs 3Q with its own Chinese supply chain. The reagent can reach the puna without passing through an Argentine purchasing decision.

The four operators, in conditioning (redundant self-supply)~100% of on-site conditioning

This is the specific captive to break. Sal de Vida has a Reagent Storage (Area 3500) + Reagent and Consumable Preparation Building (Area 3500) with three separate storage areas —quicklime, caustic and sodium carbonate—, 4 forklifts with 2 dedicated exclusively to reagents and a fleet of 5 forklifts in Stage 1 that goes to 10 in Stage 2.

See the evidence
The four operators on the same salar replicate the same infrastructure. It is broken on price (sparing them the shed, the silo and the two forklifts in the next scale-up), not by regulation.
See the remaining 3 players
Large regional lime supplierregional benchmark; in Chile ~70% of lithium's lime

The lithium market demanded ~250,000 t of lime in 2023 and projects >800,000 t by 2027 prob. We could NOT document who delivers quicklime at the Salar del Hombre Muerto, or from which quarry: it is the most concrete intra-national substitution gap.

Long-haul carriers already under contractmost of the inbound freight; no firm named in the primary sources

Fénix moves ~40 trucks/day of inputs and product. The mining suppliers' chamber's roll listed in 2023 only 4 members in transport and 1 in foreign trade across 19 categories and 123 memberships. Transport was the most contested category of 2026: CAPROMITI threatened road blockades in Fiambalá because Zijin-Liex hired a carrier from Córdoba, and the Catamarca Transport Chamber joined in.

Salta bonded warehouse — the hub model Catamarca does not have0% in Catamarca

A Salta bonded warehouse where Eramine consolidated 100 big bags into MSC containers. Catamarca has no equivalent; hence the push for a Free Trade Zone in Tinogasta (agreement with the national government of September 2026; its law went back to the provincial Senate on 14-Oct-2026). The foreign-trade link had ONE (1) member in the entire 2023 roll of the mining suppliers' chamber.

The jobs it createsThis is the niche that creates the least employment per dollar billed (70-80% of the TAM is imported molecule, not labor) and the one that creates the MOST STABLE employment in the whole chain: it is opex of an operation with ~40 years of remaining mine life, not an 18-month construction job. La lectura completa para el que busca trabajo, en la hoja de este nicho para la gente →

How we
calculate it

The number is our own estimate. The calculation, step by step, is below.

The full calculation, step by step
Annualization window: NOT APPLICABLE — this niche has no window. It is opex: consumed every day across the ~40-year mine life, and the TAM is anchored on installed capacity × consumption ratio, not on capex divided by years. It is stated explicitly because Catamarca has three different ways of annualising (a canonical 3.5 years, an extended 5, and the 4 years of the fiscal-metering niche), and a perpetual TAM compares with none of them: it measures a flow that does not switch off, not a peak being spread.TWO separate TAMs, both bottom-up. (1) reagent delivered to the plant = carbonate base x USD/t LCE of reagents delivered-to-site.Base (only carbonate produced in Catamarca; this is not generic LCE): Fénix 30 ktpa post-1A -> 40 ktpa with Phase 1B (Rio Tinto 20-F; the act of State expresses it as 28,500 -> 38,000) + Sal de Vida 15 ktpa Stage 1 + Tres Quebradas 20 ktpa Phase 1 = 65 ktpa today / 75 ktpa committed nameplate (the floor that is published) / 115 ktpa only if the 40 ktpa of 3Q's Phase 2 are additional —RIGI resolution published on 29 July 2026—, which is a scenario and not a fact.Excluded: HMW (produces a 6% Li chloride concentrate by nanofiltration, does not crystallize carbonate -> consumes no carbonation soda ash) and Sal de Oro (a strip shared 50/50 with Salta, reported by Salta as its own; if half were imputed to it, +11.5 ktpa and the TAM rises to USD 114-182 M/year). Independent cross-check of the base: minister Murua projects ~65,000 t by Dec-2026 and 100,000 t/year within 2-3 years.Unit price (a band of three anchors): USD 1,314/t LCE of reagents with prices quoted 'delivery to site' Q4-2021 (Sal de Vida's NI 43-101, Table 21-2, primary source opened) as the floor; USD 1,918.35/t LCE = 40.9% of total spend, base year 2019 (Mining Secretariat, primary source opened) as the midpoint; and USD ~2,100/t implied by Rio Tinto Q2-2026 (reagents 42% FY2025 / 35% H1-2026 over a stated C1 of USD 5-8/kg) as the ceiling.Result: 65,000 x 1,314-2,100 = USD 85-137 M; 75,000 x 1,314-2,100 = USD 99-158 M -> the direct arithmetic gives USD 85-160 M/year; we publish the conservative reading, on real 2026 consumption and not at nominal capacity: USD 55-95 M/year, midpoint ~USD 70 M (40-50 kt of effective carbonate x USD 1,314-1,918/t), with USD 85-145 M/year at 2027-28 nameplate and a ceiling of ~USD 220 M/year with 3Q's Phase 2.Breakdown: soda ash 91,000-156,100 t/year (base x a ratio of 1.4 stoich. to the 2.081 actually observed in 2016-2020) x USD 485-600/t delivered to plant = USD 50-90 M/year, of which the nationalized CIF molecule (485/t + 9% tariff) is USD 48-83 M/year; lime + NaOH + HCl the rest, USD 25-60 M/year (a wide band because there is NO published lime ratio per t of LCE). (2) Last mile = tonnage x rate.Tonnage: soda ash 91-156 kt/year + an Explicit assumption of +40-70% tonnage for lime/NaOH/HCl = 130-265 kt/year, midpoint ~180 kt/year (check: 180 kt / 28 t per flatbed = ~6,400 trips/year = ~18 inbound trucks/day, against the ~40 trucks/day that Fénix moves today of inputs AND product).Rate: storage and conditioning USD 15-35/t (still a stated assumption) + Last mile with a new anchor (2026-07-25) of USD 30-65/t, midpoint ~USD 40/t, for the 145 km of gravel road from Antofagasta de la Sierra to the salar. It is built in two steps, each with its source: the paved base of fadeeac's reference rate (150 km = ARS 32,550/t in Mar-2026 = USD 22-23/t) x the asphalt-to-gravel jump measured by Salta's mining suppliers chamber (USD 3,000 against USD 1,800 per semi-trailer on the same pair, i.e. x1.67), widened to a x1.4-2.0 band because it is a single measurement, from another province, from an interested party and over a mixed route. The ceiling of 65 covers the 215 km entry from San Antonio de los Cobres. Door to door from Buenos Aires: USD 130-150/t —a tapered rate is NOT quoted by adding legs—. And the reference figure that still holds firm is the outbound leg: USD 133-134/t from site to FOB Angamos, including freight, handling, warehousing and customs clearance, with reagent backhaul stated in the same primary source. Inbound and outbound are NOT compared head to head: the outbound leg is in constant ~2021 dollars without escalation and carries four cost items the inbound leg does not have..Result: 130 kt x 55 = USD 7 M; 265 kt x 115 = USD 30 M -> USD 7-30 M/year, midpoint ~USD 12-15 M/year.What does not go into the number (no double counting): Sal de Oro and everything the source places in Salta; the outbound freight of the product and the camps, which since August 2026 each have an entry of their own; geomembranes, drilling and laboratory (niches of their own); MARA/Agua Rica's lime (20,000-80,000 t/year with an assumed flotation ratio, but the project is in advanced exploration without environmental approval: stated upside and NOT added); and the capex of the process plants.⚠️ THE CAPACITY AMBIGUITY THE ACT ITSELF LEAVES OPEN. The Tres Quebradas resolution, read in full, says «una planta de proceso y de la infraestructura asociada, diseñadas para alcanzar una capacidad de producción de cuarenta mil (40.000) toneladas anuales de carbonato de litio mediante el método de extracción directa» — and it does NOT say whether those 40,000 are the project total or whether they add to the ~20,000 of the earlier phase. We searched the full text for «fase», «segunda etapa», «ampliación», «adicional», «incremental» and «capacidad total»: zero matches. The two readings give different provincial capacities —75,000 against 115,000 tonnes a year—. The first is published as the floor and the second remains as an upper scenario, sealed as our own reading; the USD 220 M/year ceiling of this calculation hangs on that scenario and not on a fact. What would settle the doubt is the Secretaría de Minería technical report the act itself cites (IF-2026-67177094-APN-SM#MEC), which is not published. It is declared and left open. And there is a second open input: the approved plant uses direct extraction, which pushes soda ash consumption per tonne towards the low end of the 1.4 to 2.081 band used here, but we found no published consumption figure for an Argentine direct-extraction plant.

Concentration Extreme in the product and fragmented only in freight. The UIA-CAEM-BID report of May 2026 sums it up: domestic supply in 73 of 91 mining categories and a single domestic soda ash producer. That producer —ALPAT, in Río Negro— does produce: version 2 of the Mining Secretariat's official study describes it operating with 225,000 t/year installed and ~400 employees, and with a series declared by the company itself of 170,000 t in 2021 and 2022 and 210,000 t in 2023. The problem is not that it does not exist: it is that it sits at the other end of the country, and the same official study says that transport cost «weighs very heavily on the final cost of a tonne of sodium carbonate delivered to the salar area». So this is a market of one distant domestic producer plus imports, with the largest buyer (Rio Tinto, owner of Fénix and Sal de Vida) integrating its own imports through a foreign port and with on-site conditioning self-supplied redundantly by the four operators. The only layer with real competition and possible entry is the last mile: storage, bagging, quality control and the final 145-215 km of dirt road up to the salt flat.

The rule that moves it

Two rules of different rank move this niche: the local-content commitments written into the RIGI resolutions (95.34% of what is paid to suppliers at Hombre Muerto Oeste goes to local suppliers, 60% at Fénix) — which improve the climate but do not cover the operating spend where the reagent lives, and which moreover count goods and works, not services —, and the provincial Re.P.E.M., a secretariat resolution that demands two years of local roots and turns a joint venture with a local partner into the key to entry.

See the underlying reading

The underlying policy that opens up this demand. It is the same inference declared by the rules and the program pillars pushing in this direction.

the RIGI promise is kept + opening and deregulation
enables
Re.P.E.M.: Catamarca's mining local-content rule is a resolution, not a law
See the rule →
The Re.P.E.M. (Res. S.E.M. 498/2014) decides who can invoice a miner in Catamarca, and in this niche it hits differently than in the others: the reagent is recurring operating spend, so the roots barrier —domicile in the province with 2 years of seniority, 50% local partners, 70% Catamarca payroll and a semi-annual sworn statement— is paid once and then pays off every month.
See the full legal grounds
A joint venture with an already registered partner is the shortcut: you enter the registry without waiting the two years.

Where the number comes from

The band is USD 55-95 M/year on real 2026 consumption, with a midpoint of ~USD 70 M/year. At 2027-28 nominal capacity it rises to USD 85-145 M/year, and the ceiling reaches ~USD 220 M/year if Tres Quebradas' Phase 2 gets built

See the calculation, the variables and how it was validated

The TAM is built from three variables you can watch one at a time: how much carbonate the province produces, how much soda ash each tonne demands and how much the reagent costs delivered up there. Change one and the number is recalculated.

~40,000-50,000 t of effective carbonate in 2026 × ~USD 1,314-1,918/t of reagents delivered to plant=The band is USD 55-95 M/year on real 2026 consumption, with a midpoint of ~USD 70 M/year
Carbonate produced in Catamarca40,000-50,000 effective t/year in 2026 (committed nominal 65,000-75,000; upper scenario 115,000 thesis)annual review
Nominal capacity is Fénix (30,000 → 40,000 with Phase 1B) + Sal de Vida (15,000) + Tres Quebradas (20,000; the second-stage act approves a 40,000 plant and does not clarify whether they add up) = 65,000-75,000 t/year. The TAM is published on effective 2026 production and not on that nominal figure: the three plants are commissioning simultaneously and none starts at full tilt. It does not count Hombre Muerto Oeste, which produces lithium chloride and not carbonate, nor Sal de Oro, which is a strip shared with Salta. ⚠️ The act approves a plant of 40,000 tonnes a year and does not say whether they replace the first stage or are added to it —its full text was searched for «fase», «segunda etapa», «ampliación», «adicional», «incremental» and «capacidad total», with zero matches—. What is published is the floor: 75,000 tonnes per year, which is the nominal capacity already committed. The 115,000 scenario assumes the 40,000 are additional, and that is our reading thesis, not a statement of the act. It moves with every ramp-up and with every published RIGI resolution.
Soda ash per tonne of carbonate1.4-2,081 t/t (central ~1.75)annual review
The physical minimum of the reaction is 1.4 and actual consumption measured in Argentina between 2016 and 2020 was 2.081. The band exists because Fénix works with direct extraction and Tres Quebradas with adsorption: routes that evaporate less and may therefore need less reagent. No operation publishes its own consumption.
Price of the reagent delivered to plant~USD 1,314-1,918 per tonne of carbonate (upside sensitivity ~2,100)live data
Floor: Sal de Vida's feasibility study, with prices quoted delivered to site. Ceiling of the calculation: the USD 1,918 from the Mining Secretariat's official study. The ~USD 2,100 implied by Rio Tinto's report —where reagents were 42% of production cost— stays as a labeled sensitivity and NOT as an anchor, because that 42% runs over its whole brine portfolio, which includes Rincón (Salta) and Olaroz (Jujuy). Imported soda ash went from USD 260 to USD 485 per tonne between 2018 and 2023, with a 9% tariff on top.

Robustness check: by the other route —tonnes of soda ash times their price— you get USD 50-90 M/year from that input alone, plus USD 25-60 M/year of lime, caustic soda and hydrochloric acid: the two methods cross inside the band. And the calculation runs on real 2026 consumption, not on nominal capacity: with three plants commissioning simultaneously, effective production stays below nominal, which is why the 2027-28 nameplate scenario is published separately, at USD 85-145 M/year.

The number rests on a few variables. The formula shows how it moves when each one changes; and each variable carries its freshness seal — how often it is worth revisiting. estim

How solid the number is estim

The figure rests on two real prices, not on an assumption. The first is official: the Mining Secretariat measured that reagents are 40.9% of the spend of producing brine lithium in Argentina —USD 1,918 per tonne of carbonate— and that actual soda ash consumption is 2.081 tonnes per tonne of product. The second we opened ourselves in Sal de Vida's feasibility study: USD 1,314 per tonne of reagents, and there the document clarifies something decisive —the prices are quoted delivered to site, at 4,000 meters—. On those two anchors we multiply by the carbonate capacity the province has today (Fénix, Sal de Vida and Tres Quebradas), and we leave out Hombre Muerto Oeste because it produces chloride, not carbonate, and therefore does not consume the reagent. The annual total is our own estimate and we say so. The storage and final-leg rates are stated assumptions, anchored in the only published puna freight price that exists: USD 133 per tonne for the outbound leg to port, from the same document.

Coverage: ARCA's official list of authorized bonded warehouses —175 across the country, counted one by one— and CAPPROMIN's trade map, the provincial chamber of mining suppliers (123 memberships with a 2023 cut-off: 1 member in foreign trade, 1 in insurance and 12 in inputs) · Sep 14, 2026 · not reviewed: the Re.P.E.M., which is the mandatory provincial register, publishes the total number of registrants but not the list of names; and no operation publishes who supplies it today with soda ash and lime

How to cite this figure: Despegue (2026). Lithium process reagents and their last mile to the puna (Catamarca) · Catamarca. despegueargentina.com/en/catamarca/reactivos-soda-ash-litio · terms of use

Neighbouring markets2 markets in the same group, from USD 0,8 to USD 11 M a year

First step · free
The first read of your company

We look at what your company does and tell you whether we see a sign that it fits this market, with the evidence behind it. If we do not see one, we say so too and name the condition that would change it. One page as a dated PDF, within 48 working hours.
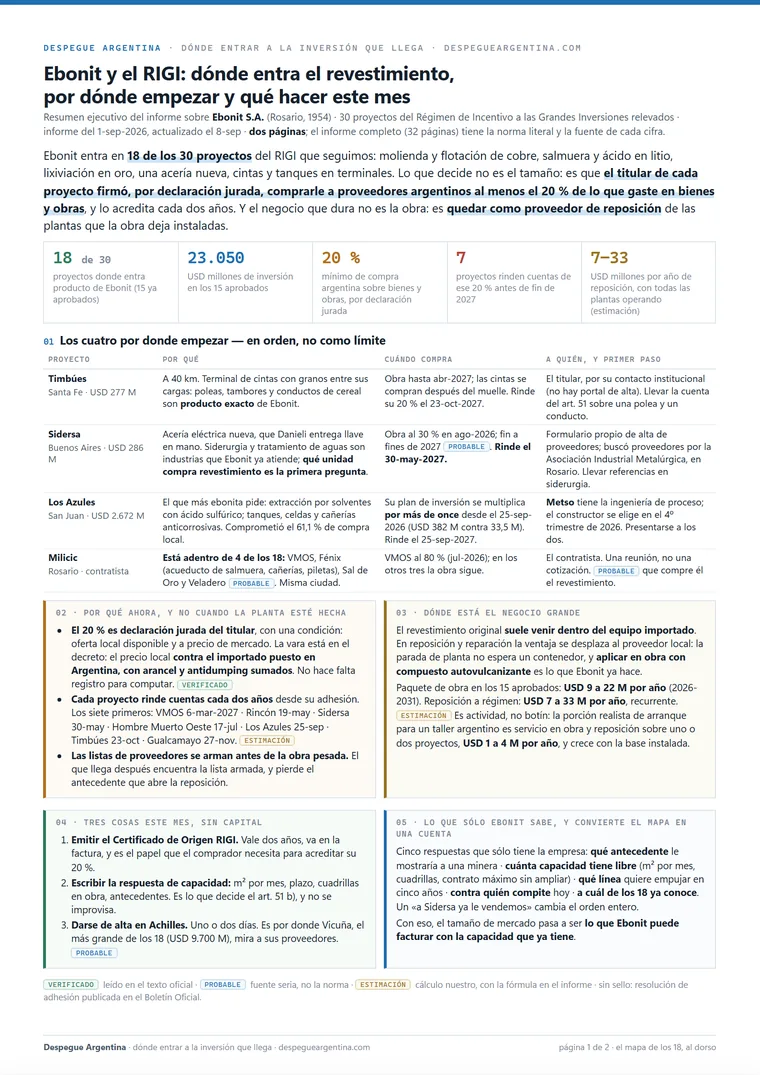
Not here for a company? Invest · Work (in Spanish) · Start a business (in Spanish) · Institutions
Page 1 of the example executive summaryOpen the report ↗A real analysis · a real company, open in full →
Ignacio Aredez
Analysis and curation: Ignacio Aredez
Head of Despegue
Method and track record →
  • 20+ years in technology, 15 of them in data and AI, for clients across Europe and the Americas
  • Certified in AI governance (ISO/IEC 42001)
  • Machine Learning (Google Cloud)
  • Registered expert with the European Commission
How to read the seals →
  verif primary source · prob primary source pending · unconf a source said it · estim our own calculation · thesis our reading · the date belongs to the datum, at the precision its source allows
This is not financial advice. The TAM is an estimate with a transparent method, not an official figure; the framing is labeled as thesis. Every figure carries its source. ← All opportunities in Catamarca